Hydrogen Storage Market
Hydrogen Storage Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711509 | Published On : November 04, 2026 |
Format : 


 | Author : Seema Bhateja
Hydrogen Storage Market Size
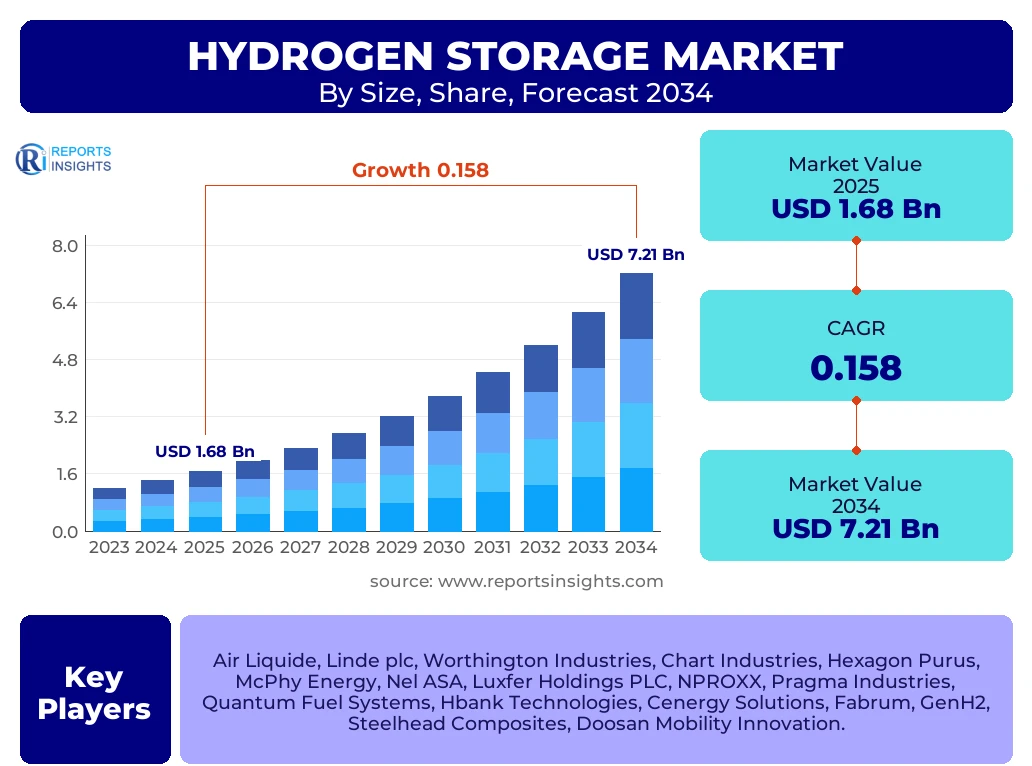
According to Reports Insights Consulting Pvt Ltd, The Hydrogen Storage Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 15.8% between 2025 and 2034. The market is estimated at USD 1.94 Billion in 2026 and is projected to reach USD 7.21 Billion by the end of the forecast period in 2034.
Key Hydrogen Storage Market Trends & Insights
The global hydrogen storage landscape is undergoing a paradigm shift, transitioning from traditional compressed gas solutions to sophisticated material-based and cryogenic liquid storage technologies. This evolution is necessitated by the rising demand for high-density storage in heavy-duty transportation and long-duration stationary energy storage systems. Market intelligence indicates a concentrated effort toward reducing the levelized cost of storage (LCOS) by optimizing carbon fiber usage in Type IV composite cylinders and advancing metal-organic frameworks (MOFs) for solid-state storage. Furthermore, the integration of hydrogen into existing natural gas infrastructure, often referred to as hydrogen blending, is serving as a catalyst for large-scale salt cavern storage projects across Europe and North America.
- Asia Pacific remains the largest region by value, driven by massive investments in fuel cell vehicle (FCEV) infrastructure in China, Japan, and South Korea.
- Europe is identified as the fastest-growing region, supported by the Hydrogen Backbone initiative and stringent decarbonization mandates across the industrial sector.
- Physical Storage (Compressed Gas and Liquefied Hydrogen) currently holds the largest market share, though Material-based Storage is witnessing the highest growth rate due to safety and density advantages.
- The Transportation segment is the leading end-user application, specifically focused on heavy-duty trucking and maritime shipping where traditional battery electric solutions face energy density limitations.
Key Takeaways Hydrogen Storage Market Size & Forecast
The hydrogen storage market is characterized by a high degree of technological innovation and capital-intensive infrastructure development. As the global energy transition accelerates, the ability to store hydrogen efficiently and safely at scale has become a critical bottleneck for the hydrogen economy. Stakeholders are increasingly focusing on the development of Type III and Type IV tanks to support the burgeoning FCEV market. Additionally, the forecast period suggests a significant uptick in the adoption of Liquid Organic Hydrogen Carriers (LOHC) for international trade, enabling the transport of hydrogen over long distances using existing petroleum infrastructure.
- China is the leading country in terms of installed storage capacity for hydrogen refueling stations, bolstered by state-led subsidies and industrial policy.
- The Industrial application segment is expected to see a surge in demand for large-scale geological storage, particularly in depleted oil and gas reservoirs and salt caverns.
- Technological advancements in Cryo-compressed hydrogen storage (CcH2) are bridging the gap between liquid and gaseous storage, offering superior volumetric density for commercial fleets.
- The market is seeing a move toward Vertical Integration, where energy companies are partnering with storage tank manufacturers to secure supply chains.
Hydrogen Storage Market Drivers Analysis
The primary driver for the hydrogen storage market is the aggressive global push toward net-zero emissions, which positions hydrogen as a versatile energy carrier for hard-to-abate sectors. Governments are providing unprecedented financial support, such as the Inflation Reduction Act in the United States and the Green Deal in Europe, which subsidize hydrogen production and infrastructure. This policy support reduces the investment risk for storage projects and encourages private equity participation. Additionally, the rapid decline in the cost of renewable energy facilitates the production of green hydrogen, subsequently increasing the demand for efficient storage solutions to manage the intermittent nature of wind and solar power.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Decarbonization of Heavy-Duty Transport | +4.2% | Global / EU focus | 2025 - 2034 |
| Government Subsidies & Policy Frameworks | +3.8% | USA (IRA), Germany, China | 2025 - 2030 |
| Scaling of Green Hydrogen Production | +3.5% | Australia, Middle East, Chile | 2027 - 2034 |
Hydrogen Storage Market Restraints Analysis
High capital expenditure remains a significant barrier to the widespread adoption of hydrogen storage technologies. The cost of advanced materials, particularly carbon fiber for high-pressure tanks and rare metals for chemical storage, inflates the overall system cost. Furthermore, the technical challenges associated with hydrogen’s low volumetric energy density and its tendency to cause embrittlement in standard steel pipes necessitate specialized and expensive alloys. Regulatory hurdles and a lack of standardized international safety codes also slow down the deployment of large-scale storage facilities, particularly in residential or urban areas.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Material and Manufacturing Costs | -2.5% | Global | 2025 - 2028 |
| Hydrogen Embrittlement & Infrastructure Complexity | -1.8% | Europe, North America | 2025 - 2034 |
Hydrogen Storage Market Opportunities Analysis
One of the most promising opportunities lies in the development of solid-state hydrogen storage using metal hydrides, which offers high safety profiles and energy densities suitable for portable and stationary applications. There is also a growing market for LOHC (Liquid Organic Hydrogen Carriers) which allows for the safe storage and transport of hydrogen at ambient temperatures and pressures. As the maritime industry looks to decarbonize, the demand for large-scale liquid hydrogen (LH2) storage on vessels and at ports presents a multi-billion dollar opportunity for engineering and cryogenic equipment manufacturers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Emergence of LOHC for Global Trade | +2.9% | Japan, South Korea, Middle East | 2028 - 2034 |
| Maritime and Aviation Sector Adoption | +2.1% | Global / Norway, UK | 2030 - 2034 |
Hydrogen Storage Market Challenges Impact Analysis
Safety perceptions and public acceptance of high-pressure hydrogen storage in proximity to populated areas remain a significant challenge. Addressing these concerns requires extensive safety testing, public education, and the development of fail-safe leak detection systems. Additionally, the lack of a comprehensive global hydrogen pipeline network means that storage must often be co-located with production or end-use, limiting the flexibility of the supply chain. Competition from battery electric vehicle (BEV) improvements also forces hydrogen storage providers to innovate faster to maintain a competitive advantage in the light-duty vehicle market.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Regulatory Fragmentations & Safety Standards | -1.5% | International | 2025 - 2030 |
| Competing Energy Storage Technologies | -1.2% | China, USA | 2025 - 2034 |
Hydrogen Storage Market - Updated Report Scope
This comprehensive report examines the global hydrogen storage ecosystem, providing a granular analysis of technological pathways, end-user adoption rates, and regional regulatory landscapes. The scope encompasses physical storage methods including compressed gas, cryogenic liquid, and cryo-compressed hydrogen, alongside material-based solutions such as metal hydrides, chemical storage, and sorbent materials. Our analysis provides strategic insights for stakeholders looking to navigate the transition from fossil-fuel-based storage to sustainable hydrogen solutions, with a detailed focus on the supply-demand dynamics across 20 countries.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.68 Billion |
| Market Forecast in 2034 | USD 7.21 Billion |
| Growth Rate | 15.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Air Liquide, Linde plc, Worthington Industries, Chart Industries, Hexagon Purus, McPhy Energy, Nel ASA, Luxfer Holdings PLC, NPROXX, Pragma Industries, Quantum Fuel Systems, Hbank Technologies, Cenergy Solutions, Fabrum, GenH2, Steelhead Composites, Doosan Mobility Innovation. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The hydrogen storage market is segmented into physical and material-based storage, with physical storage currently dominating due to its technological maturity. However, material-based storage is projected to experience a surge in demand as R&D efforts yield more stable and efficient metal hydride and LOHC solutions. Within the tank segment, Type IV cylinders—made from carbon fiber with a plastic liner—are becoming the industry standard for mobile applications due to their lightweight and high-pressure capabilities (up to 700 bar). The application landscape is bifurcated into transportation, which requires high volumetric density, and stationary storage, which prioritizes safety and cost over weight.
- By Storage Method:
- Compressed Gas (High-pressure tanks)
- Liquefied Hydrogen (Cryogenic cooling)
- Material-based (Adsorption, Chemical storage, Hydrides)
- By Tank Type:
- Type I (All metal, typically steel)
- Type II (Metal liner, hoop wrapped with composite)
- Type III (Metal liner, fully wrapped with composite)
- Type IV (Non-metal liner, fully wrapped with composite)
- By Application:
- Transportation (Passenger cars, Buses, Trucks, Trains, Ships)
- Stationary Power (Grid balancing, Backup power)
- Industrial (Refineries, Chemical processing)
- Portable Power (Electronics, Military applications)
Regional Highlights
The regional distribution of the hydrogen storage market reflects a mix of advanced technological infrastructure and strong policy mandates. The Asia-Pacific region currently holds the highest market share, primarily due to the aggressive adoption of fuel-cell passenger vehicles and buses in China and South Korea. These nations have built extensive networks of hydrogen refueling stations (HRS), necessitating massive investments in on-site storage solutions. Europe follows closely as the fastest-growing market, with Germany and the Netherlands leading the charge in large-scale industrial hydrogen clusters and underground storage projects aimed at securing seasonal energy reserves.
- North America: Driven by the expansion of hydrogen trucking corridors in California and federal support for regional hydrogen hubs across the United States.
- Europe: The epicentre of salt cavern storage and maritime hydrogen initiatives, with Germany being the largest national market.
- Asia Pacific: The global hub for high-pressure tank manufacturing and fuel cell vehicle deployment, led by China, Japan, and South Korea.
- Middle East: Emerging as a major exporter of hydrogen, focusing on large-scale liquid hydrogen and ammonia storage for international shipping.
- Latin America: Focused on green hydrogen production for export, with Chile leading in pilot storage projects for heavy-duty mining equipment.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Hydrogen Storage Market.- Air Liquide
- Linde plc
- Worthington Industries
- Chart Industries
- Hexagon Purus
- McPhy Energy
- Nel ASA
- Luxfer Holdings PLC
- NPROXX
- Pragma Industries
- Quantum Fuel Systems
- Hbank Technologies
- Cenergy Solutions
- Fabrum
- GenH2
- Steelhead Composites
- Doosan Mobility Innovation
- Faurecia (FORVIA)
- Toyota Motor Corporation
- PLASTIC OMNIUM
Frequently Asked Questions
What is the current primary method of hydrogen storage?
The primary method of hydrogen storage is compressed gas, typically stored in high-pressure tanks at 350 bar or 700 bar. This method is technologically mature and widely used in both stationary applications and fuel cell vehicles.
Why are Type IV tanks preferred over Type I for vehicles?
Type IV tanks are preferred for vehicles because they use a non-metallic liner (plastic) and a carbon fiber composite wrap, making them significantly lighter than Type I steel tanks. This weight reduction is crucial for vehicle efficiency and range.
What are the safety risks associated with hydrogen storage?
The main risks include hydrogen's high flammability, its ability to leak through small openings due to its small molecular size, and its tendency to cause embrittlement in certain metals. Modern storage systems mitigate these through advanced materials and sensors.
How does liquid hydrogen storage differ from compressed gas?
Liquid hydrogen storage involves cooling hydrogen to cryogenic temperatures (below -253°C) to increase its density. While it offers higher energy density than compressed gas, it requires energy-intensive liquefaction and specialized insulated tanks.
What role does underground storage play in the hydrogen economy?
Underground storage, particularly in salt caverns, provides the large-scale capacity needed for seasonal energy storage and grid stabilization. It allows for the storage of massive quantities of hydrogen produced from surplus renewable energy.
Author
S
Seema Bhateja is a Manger Energy and Power Research Industry with 7+ years of experience in the Energy and Power Industry. She specializes in energy market intelligence, power generation analysis, renewable energy assessment, demand forecasting, competitive benchmarking, grid infrastructure evaluation, regulatory landscape analysis, market sizing, and investment trend analysis across conventional and clean energy sectors. Her research integrates industry expertise with data-driven methodologies to help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, anticipate evolving market trends, and strengthen their competitive positioning in the global energy and power market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
