Healthcare Third Party Logistics Market
Healthcare Third Party Logistics Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711458 | Published On : November 02, 2026 |
Format : 


 | Author : Erika Grotto
Healthcare Third Party Logistics Market Size
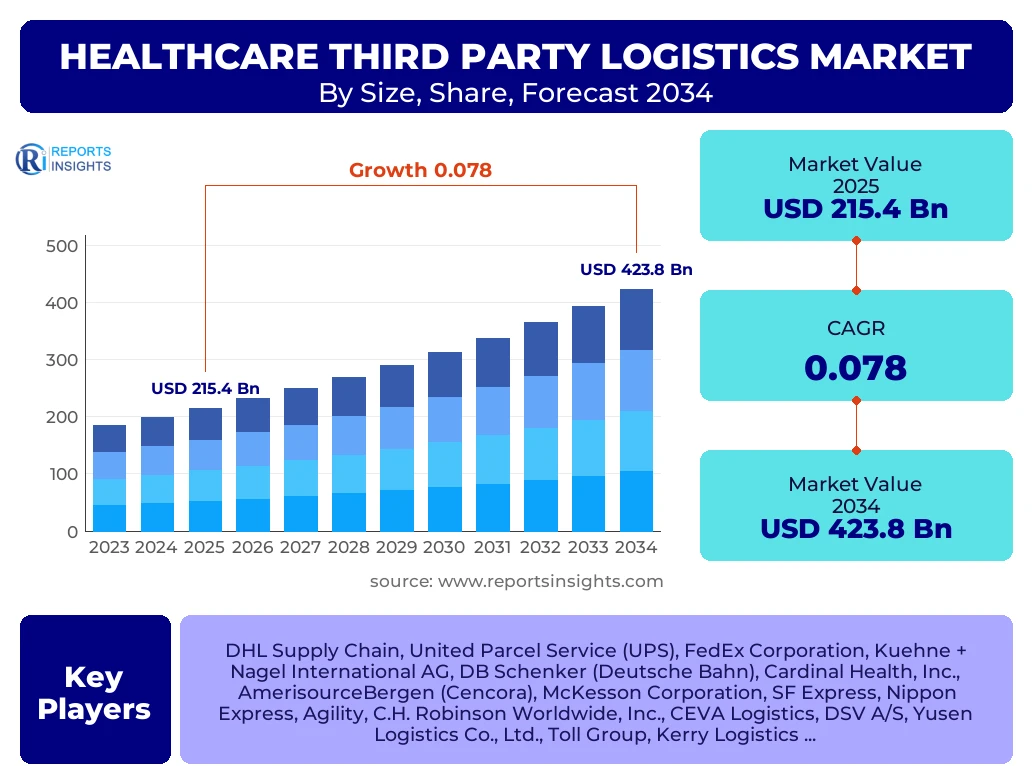
According to Reports Insights Consulting Pvt Ltd, The Healthcare Third Party Logistics Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.8% between 2025 and 2034. The market is estimated at USD 231.5 Billion in 2026 and is projected to reach USD 423.8 Billion by the end of the forecast period in 2034.
Key Healthcare Third Party Logistics Market Trends & Insights
The global healthcare third party logistics (3PL) landscape is undergoing a radical transformation driven by the integration of advanced digital technologies and the rising demand for specialized handling of biologics. Market intelligence indicates that stakeholders are increasingly prioritizing end-to-end visibility and real-time monitoring to ensure the integrity of temperature-sensitive pharmaceutical products. The shift toward personalized medicine and cell and gene therapies has necessitated more complex supply chain solutions, moving beyond traditional warehousing into highly specialized cryogenic storage and hyper-local distribution networks. Furthermore, the industry is witnessing a consolidation phase where large-scale logistics providers are acquiring niche healthcare logistics firms to bolster their regulatory compliance capabilities and cold-chain infrastructure. As pharmaceutical companies seek to reduce operational overhead, the outsourcing of non-core activities such as packaging, labeling, and reverse logistics has become a standard strategic maneuver, particularly in high-growth markets where infrastructure may be fragmented.
- Largest Region: North America remains the dominant market, accounting for over 38% of the global share, fueled by a robust pharmaceutical sector and stringent regulatory frameworks.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR during the forecast period due to rapid healthcare infrastructure expansion in China and India.
- Largest Segment by Share: The Pharmaceutical Logistics segment holds the majority share, driven by the massive volume of prescription drug distribution and the rise of biopharmaceuticals.
- Emerging Trend: Adoption of Blockchain and AI-driven predictive analytics for supply chain resilience and anti-counterfeiting measures.
Key Takeaways Healthcare Third Party Logistics Market Size & Forecast
The long-term outlook for the healthcare 3PL market remains highly positive, with a steady trajectory toward automation and sustainability. Large-scale enterprise players are focusing on decarbonizing their fleets and optimizing route efficiency to align with global ESG (Environmental, Social, and Governance) mandates. The market is characterized by high barriers to entry due to the complex regulatory requirements such as Good Distribution Practices (GDP) and the Drug Supply Chain Security Act (DSCSA). Strategic partnerships between healthcare providers and 3PL specialists are evolving from transactional relationships into long-term strategic alliances, where logistics providers take on significant roles in inventory management and regulatory reporting. The forecast period anticipates a significant surge in demand for last-mile delivery services, particularly for home-based healthcare and direct-to-patient pharmacy models, which require precise logistics execution and high levels of patient data privacy.
- Leading Country: The United States leads in total market value, supported by the presence of major pharmaceutical giants and advanced logistics infrastructure.
- Critical Growth Factor: The global expansion of the biologics and biosimilars market is the primary catalyst for specialized cold-chain logistics demand.
- Strategic Shift: Transition from "Just-in-Time" to "Just-in-Case" inventory models to mitigate the risks of global supply chain disruptions seen in recent years.
- Market Stability: High recurring revenue models for 3PL providers due to long-term contracts with medical device and pharmaceutical manufacturers.
Healthcare Third Party Logistics Market Drivers Analysis
The primary driver for the healthcare 3PL market is the escalating global demand for biopharmaceuticals and specialty drugs. Unlike traditional chemical-based medicines, biologics are highly sensitive to temperature and environmental conditions, requiring sophisticated cold-chain management that most manufacturers prefer to outsource to specialized logistics experts. The global rise in chronic diseases, such as diabetes and cardiovascular conditions, has led to an increased volume of daily pharmaceutical shipments, putting pressure on existing supply chains and necessitating the efficiency of 3PL providers. Furthermore, the globalization of the pharmaceutical trade has made it essential for companies to navigate diverse international regulatory environments, a task that 3PLs are better equipped to handle due to their local expertise and established networks.
Another significant driver is the increasing focus on cost reduction among pharmaceutical and medical device manufacturers. By outsourcing logistics, these companies can convert fixed costs into variable costs, allowing them to redirect capital toward Research and Development (R&D) and core manufacturing processes. The emergence of high-tech medical devices also requires specialized handling and white-glove delivery services, which 3PL providers have integrated into their service portfolios. Technology adoption, including the use of Internet of Things (IoT) sensors and cloud-based management systems, has further incentivized manufacturers to partner with 3PLs that offer superior data transparency and inventory accuracy.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Growth of Biopharmaceuticals and Cold Chain Demand | +2.4% | Global / Europe & North America | 2025 - 2034 |
| Cost Efficiency through Outsourcing Models | +1.8% | Global / Emerging Markets | 2025 - 2030 |
| Technological Integration (IoT & AI) | +1.5% | Global / Asia-Pacific | 2026 - 2034 |
Healthcare Third Party Logistics Market Restraints Analysis
Despite the growth, the market faces significant restraints, primarily stemming from the complex and evolving regulatory landscape. Different countries have varying standards for the storage and transportation of medical products, making it difficult for 3PL providers to maintain a uniform global operating procedure. Compliance with regulations like the DSCSA in the US or the EU Falsified Medicines Directive requires heavy investment in serialization and tracking technology, which can be a financial burden for smaller logistics providers. This regulatory pressure often leads to increased operational costs, which are then passed down the supply chain, potentially affecting the overall market growth rate.
Additionally, the high cost associated with establishing and maintaining specialized cold-chain infrastructure acts as a barrier. The specialized equipment needed for ultra-low temperature storage, such as that required for mRNA vaccines, involves high capital expenditure and ongoing maintenance costs. There is also a significant shortage of skilled labor capable of managing specialized healthcare logistics, which can lead to operational inefficiencies or errors that compromise product safety. Any failure in the cold chain can lead to massive financial losses and legal liabilities, making risk management a constant and costly concern for 3PL entities.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Global Regulatory Compliance | -1.1% | European Union / North America | 2025 - 2034 |
| High Capital Expenditure for Cold Chain | -0.8% | Global | 2025 - 2028 |
Healthcare Third Party Logistics Market Opportunities Analysis
One of the most promising opportunities in the healthcare 3PL market lies in the expansion into emerging economies. Countries in Latin America, Southeast Asia, and Africa are experiencing rapid healthcare infrastructure development and rising middle-class populations, leading to an increased demand for quality medicines. 3PL providers that can establish reliable, GDP-compliant networks in these regions stand to gain a first-mover advantage as local pharmaceutical production and international imports grow. The liberalization of healthcare markets in these regions is also encouraging global pharmaceutical companies to increase their footprint, creating a direct need for outsourced logistics support.
The rise of Direct-to-Patient (DTP) and Home Healthcare models presents another significant growth avenue. As healthcare shifts away from traditional hospital settings toward home-based care, the logistics of delivering drugs and medical equipment directly to a patient's doorstep becomes critical. This requires a different logistical approach than bulk hospital deliveries, focusing on smaller, more frequent shipments and high-level customer service. 3PL providers that develop specialized DTP solutions, including telehealth integration and sensitive medication handling, will find a lucrative and expanding niche within the broader healthcare logistics market.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Emerging Market Expansion (APAC & LATAM) | +2.1% | China, India, Brazil | 2026 - 2034 |
| Direct-to-Patient (DTP) Logistics Services | +1.7% | Global / North America | 2025 - 2034 |
Healthcare Third Party Logistics Market Challenges Impact Analysis
The healthcare 3PL sector is currently grappling with the challenge of supply chain volatility and geopolitical tensions. Disruptions in global trade routes can lead to significant delays in the delivery of critical medical supplies, which can have life-threatening consequences. Logistics providers must now invest heavily in contingency planning and diverse routing strategies to ensure business continuity. Furthermore, the rising threat of cyberattacks on logistics networks poses a serious risk, as the digitalization of the supply chain makes it vulnerable to data breaches that could expose sensitive patient information or disrupt the flow of essential medicines.
Another persistent challenge is the environmental impact of logistics operations. The healthcare industry is under increasing pressure to reduce its carbon footprint, but the energy-intensive nature of cold-chain storage and refrigerated transport makes this difficult. 3PL providers are challenged to find sustainable solutions, such as recyclable packaging and electric delivery vehicles, without compromising the strict temperature requirements of healthcare products. Balancing sustainability goals with the uncompromising safety standards of the healthcare sector remains a complex operational puzzle for most industry players.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Geopolitical Disruptions and Supply Chain Fragility | -0.9% | Global / Middle East & Europe | 2025 - 2030 |
| Cybersecurity Threats in Digital Logistics | -0.6% | Global | 2025 - 2034 |
Healthcare Third Party Logistics Market - Updated Report Scope
This comprehensive report provides a detailed examination of the global healthcare 3PL market, covering all major service types, application areas, and supply chain provider categories. It includes a rigorous analysis of market dynamics, competitive positioning, and future growth prospects across six major geographic regions. The scope encompasses pharmaceutical products, medical devices, and biotechnology applications, providing granular data on market size, share, and growth rates from 2020 through the forecast period ending in 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 215.4 Billion |
| Market Forecast in 2034 | USD 423.8 Billion |
| Growth Rate | 7.8% CAGR |
| Number of Pages | 265 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | DHL Supply Chain, United Parcel Service (UPS), FedEx Corporation, Kuehne + Nagel International AG, DB Schenker (Deutsche Bahn), Cardinal Health, Inc., AmerisourceBergen (Cencora), McKesson Corporation, SF Express, Nippon Express, Agility, C.H. Robinson Worldwide, Inc., CEVA Logistics, DSV A/S, Yusen Logistics Co., Ltd., Toll Group, Kerry Logistics, GEODIS. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The healthcare 3PL market is segmented based on service type, supply chain provider, and application, each reflecting different operational needs and growth drivers. The transportation segment is the largest within service types, as it involves the physical movement of goods across diverse geographies under strict time and temperature constraints. Warehousing and storage follow closely, with a growing emphasis on climate-controlled environments and strategic regional hubs. Value-added services, including secondary packaging and regulatory labeling, are the fastest-growing sub-segments as pharmaceutical companies look to streamline their downstream operations. From an application perspective, the pharmaceutical segment remains the primary revenue contributor, though the medical device segment is seeing significant growth due to the increasing complexity of diagnostic and surgical equipment requiring specialized handling.
- By Service Type:
- Warehousing and Storage (Cold Storage, Ambient Storage)
- Transportation (Air Freight, Sea Freight, Overland Transport)
- Value-added Services (Packaging, Labeling, Kitting, Reverse Logistics)
- By Supply Chain Provider:
- Third Party Logistics (3PL)
- Fourth Party Logistics (4PL)
- By Application:
- Pharmaceutical Logistics (Prescription, OTC, Biologics)
- Medical Device Logistics (Equipment, Consumables)
- Biotechnology and Life Sciences
Regional Highlights
- North America: Holds the largest market share. This is attributed to the presence of global pharmaceutical leaders and the early adoption of advanced tracking technologies. The U.S. remains the central hub for innovation in healthcare logistics.
- Europe: The second-largest market, characterized by very high regulatory standards (GDP compliance) and a mature logistics network. Germany, France, and the UK are the key drivers in this region.
- Asia-Pacific: Identified as the fastest-growing region. Massive investments in healthcare infrastructure in China and India, along with a growing manufacturing base for generic medicines and biosimilars, are fueling exponential demand for 3PL services.
- Latin America: Showing steady growth as multinational pharmaceutical companies expand their sales networks into Brazil and Mexico, requiring professional logistics partners.
- Middle East & Africa: Developing as a strategic transit hub for global healthcare trade, with countries like the UAE investing heavily in state-of-the-art cold-chain facilities.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Healthcare Third Party Logistics Market. These organizations are at the forefront of innovation, investing heavily in digital twins, automated warehouses, and sustainable transport solutions.
- DHL Supply Chain
- United Parcel Service (UPS) Healthcare
- FedEx Corporation
- Kuehne + Nagel International AG
- DB Schenker
- Cardinal Health, Inc.
- AmerisourceBergen (Cencora)
- McKesson Corporation
- SF Express
- Nippon Express
- Agility Logistics
- C.H. Robinson Worldwide, Inc.
- CEVA Logistics
- DSV A/S
- Yusen Logistics Co., Ltd.
- Toll Group
- Kerry Logistics
- GEODIS
- Mainfreight
- Bolloré Logistics
Frequently Asked Questions
What is the current market size of the Healthcare Third Party Logistics Market?
The market is estimated at USD 215.4 Billion in 2025 and is projected to reach approximately USD 423.8 Billion by 2034, growing at a CAGR of 7.8%.
Which region is expected to show the highest growth rate?
The Asia-Pacific region is expected to be the fastest-growing market due to rapid urbanization, increasing healthcare expenditure, and the expansion of pharmaceutical manufacturing in India and China.
What are the main drivers for the Healthcare 3PL market?
Key drivers include the rising demand for cold-chain logistics for biopharmaceuticals, the need for cost reduction through outsourcing, and the globalization of the pharmaceutical supply chain.
Who are the leading players in this market?
Major players include DHL Supply Chain, UPS Healthcare, FedEx, Kuehne + Nagel, and Cardinal Health, among others who specialize in GDP-compliant logistics services.
What role does technology play in the Healthcare 3PL market?
Technology is critical for real-time monitoring, data transparency, and regulatory compliance. IoT, AI, and Blockchain are being used to track temperature, optimize routes, and prevent the entry of counterfeit drugs into the supply chain.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
