Graphene Electronic Market
Graphene Electronic Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_708936 | Published On : September 11, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Graphene Electronic Market Size
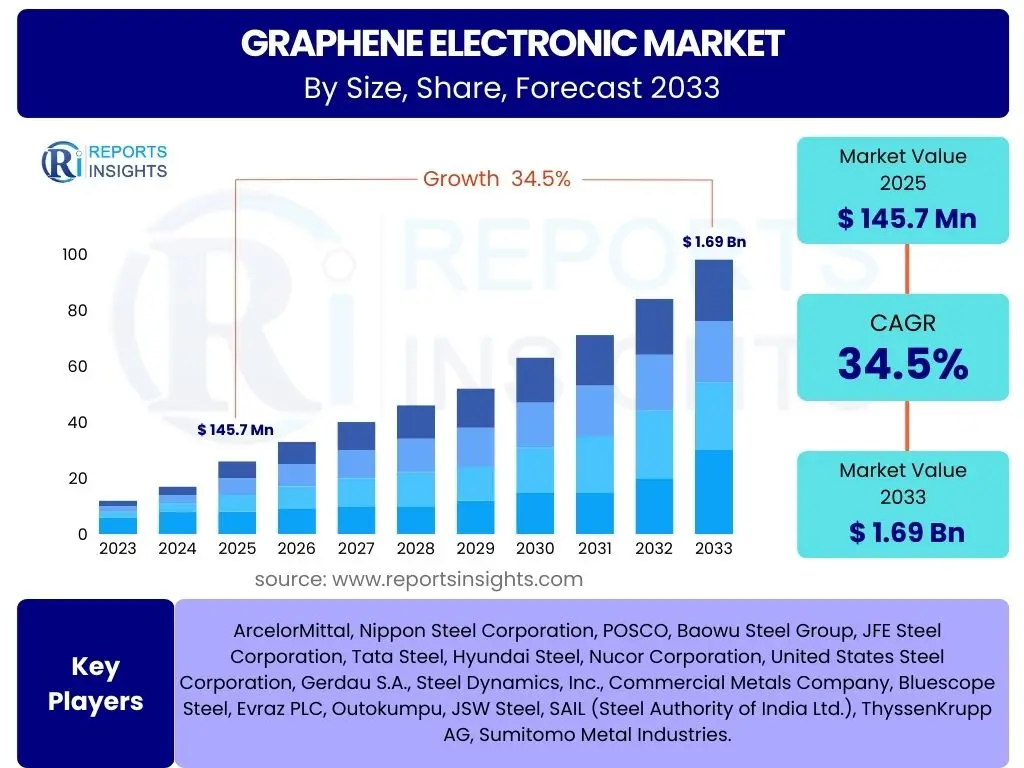
According to Reports Insights Consulting Pvt Ltd, The Graphene Electronic Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 37.5% between 2026 and 2034. The market is estimated at USD 1.58 Billion in 2026 and is projected to reach USD 21.42 Billion by the end of the forecast period in 2034.
Key Graphene Electronic Market Trends & Insights
The Graphene Electronic market is undergoing a transformative phase driven by the demand for next-generation semiconductors that surpass the physical limits of silicon. Industry analysis indicates that the integration of graphene in flexible displays and high-frequency communication devices is no longer a theoretical concept but a commercial reality. Stakeholders are increasingly focusing on scalable chemical vapor deposition (CVD) techniques to produce high-quality graphene films, which are essential for high-performance transistors and sensors. Current market intelligence suggests that the convergence of 5G/6G technology and Internet of Things (IoT) ecosystems is creating a fertile ground for graphene-based components due to their superior electron mobility and thermal management capabilities.
- Largest Region: Asia Pacific currently holds the largest market share, driven by massive investments in semiconductor manufacturing and consumer electronics hubs in China, South Korea, and Taiwan.
- Fastest Growing Region: North America is expected to witness the highest CAGR during the forecast period, fueled by intensive R&D activities in graphene-based quantum computing and defense electronics.
- Largest Segment by Share: Graphene-based sensors represent the largest product segment, owing to their widespread adoption in medical diagnostics and environmental monitoring.
- Emerging Trend: The shift toward flexible and wearable electronics is accelerating the demand for graphene-based transparent conductive films (TCFs) as an alternative to Indium Tin Oxide (ITO).
Key Takeaways Graphene Electronic Market Size & Forecast
The market trajectory for Graphene Electronic is characterized by exponential growth as manufacturing costs decrease and material purity increases. Comprehensive data synthesis reveals that the transition from pilot-scale production to industrial-scale manufacturing is the primary catalyst for the projected valuation. Key takeaways highlight that while consumer electronics remain the volume driver, the automotive sector is emerging as a critical high-value segment for graphene-enhanced power electronics and battery management systems. The forecast period will likely see a consolidation of key players focusing on intellectual property acquisition and strategic partnerships with end-users in the telecommunications and aerospace sectors.
- Dominant Country: China leads the global market in terms of both graphene production capacity and the number of patents filed related to Graphene Electronics applications.
- Technology Shift: There is a significant move toward hybrid silicon-graphene chips to leverage existing CMOS infrastructure while enhancing performance.
- Market Driver: The urgent need for efficient thermal management in miniaturized high-power electronics is a major factor pushing graphene adoption.
- Forecast Stability: Despite high initial costs, the long-term ROI provided by energy efficiency and device longevity is stabilizing the forecast outlook.
Graphene Electronic Market Drivers Analysis
The primary drivers of the Graphene Electronic market include the inherent limitations of silicon at sub-5nm scales and the rising demand for ultra-fast, energy-efficient electronic devices. As Moore’s Law slows down, graphene offers a viable alternative due to its exceptional carrier mobility, which can exceed 200,000 cm2/Vs. Furthermore, the global push for sustainability is driving interest in graphene’s ability to reduce power consumption in data centers and portable electronics.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Demand for Flexible and Wearable Electronics | +8.5% | South Korea, Japan, USA | 2025 - 2034 |
| Advancements in 5G and 6G Infrastructure | +7.2% | Global | 2026 - 2032 |
| Miniaturization of Semiconductor Components | +6.8% | Taiwan, China | 2025 - 2034 |
Graphene Electronic Market Restraints Analysis
Significant restraints include the high cost of high-quality graphene production and the technical challenges associated with the absence of a natural bandgap in graphene. The lack of a bandgap makes it difficult to turn graphene-based transistors "off," which is a fundamental requirement for digital logic circuits. Additionally, the complexity of integrating graphene into existing semiconductor fabrication lines without contamination remains a significant hurdle for mass adoption.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Technical Hurdles in Creating a Synthetic Bandgap | -5.4% | Global Research Hubs | 2025 - 2028 |
| High Capital Expenditure for CVD Equipment | -4.1% | Europe, North America | 2025 - 2030 |
Graphene Electronic Market Opportunities Analysis
Opportunities abound in the development of graphene-based biosensors for real-time health monitoring and the use of graphene in quantum computing architectures. The unique quantum Hall effect in graphene provides a stable platform for developing qubits that can operate at higher temperatures than current superconducting solutions. Furthermore, the replacement of ITO in touchscreens and photovoltaic cells presents a multi-billion dollar opportunity as graphene offers better mechanical flexibility and transparency.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Graphene-Based Quantum Computing Components | +9.3% | USA, Germany, UK | 2028 - 2034 |
| Integration in Electric Vehicle Power Modules | +7.5% | China, Germany | 2026 - 2034 |
Graphene Electronic Market Challenges Impact Analysis
The primary challenge lies in achieving large-scale uniformity and defect-free graphene layers consistently. Any structural defect or impurity significantly degrades the electronic properties of graphene, leading to performance variability. Moreover, the lack of standardized testing and quality control protocols across the global supply chain creates difficulties for end-users in validating the performance of graphene-enhanced components.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Scalability of Defect-Free Production | -3.8% | Global Manufacturing | Ongoing |
| Supply Chain Standardization Issues | -2.5% | Global | 2025 - 2027 |
Graphene Electronic Market - Updated Report Scope
This report provides a comprehensive analysis of the global Graphene Electronic landscape, covering material types, product categories, and diverse end-use industries. The scope extends to a detailed evaluation of the technological readiness levels (TRL) of various graphene applications, from laboratory prototypes to fully commercialized electronic components. The research includes competitive benchmarking and strategic analysis of patent landscapes to provide a holistic view of the market evolution through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.15 Billion |
| Market Forecast in 2034 | USD 21.42 Billion |
| Growth Rate | 37.5% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Samsung Electronics, IBM Corporation, Graphenea S.A., Applied Materials, Inc., BASF SE, Xerox Corporation, LG Electronics, Nokia, Grafoid Inc., Graphene Frontiers, Skeleton Technologies, CVD Equipment Corporation, NanoXplore Inc., Haydale Graphene Industries, Talga Group, Zen Graphene Solutions, First Graphene Ltd., Graphene Manufacturing Group (GMG). |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Graphene Electronic market is segmented based on product type, material, and end-user application. The segmentation reflects the diverse utility of graphene across different stages of electronic component manufacturing. High-performance computing and sensing technologies are the most dominant segments, while energy storage and flexible displays represent the fastest-growing niches. Each segment is analyzed for its growth potential, technological barriers, and adoption rates across various geographies.
- Product Type:
- Sensors: Including chemical, biological, and hall-effect sensors.
- Transistors: High-frequency and high-mobility GFETs.
- Transparent Conductive Films: Used in touchscreens and solar cells.
- Batteries and Supercapacitors: Graphene-enhanced electrodes for rapid charging.
- Material Type:
- Graphene Film: High-purity films produced via CVD for semiconductor applications.
- Graphene Oxide (GO): Widely used in sensors and water purification electronics.
- Graphene Nano-platelets (GNP): Cost-effective material for composites and conductive inks.
- End-Use Application:
- Consumer Electronics: Smartphones, wearables, and flexible displays.
- Healthcare: Implantable biosensors and diagnostic devices.
- Automotive: Power electronics for EVs and autonomous driving sensors.
- Aerospace & Defense: Lightweight EMI shielding and high-frequency radar components.
Regional Highlights
- Asia Pacific: Holds the largest market share (approx. 42% in 2025). China is the primary engine of growth due to its massive electronic manufacturing ecosystem and government subsidies for advanced materials. South Korea and Japan are leaders in integrating graphene into consumer electronics and display technologies.
- North America: The fastest-growing region with a projected CAGR of 39.2%. Growth is driven by top-tier research universities, significant venture capital investment, and the presence of major tech giants exploring graphene for AI hardware and quantum computing.
- Europe: A pioneer in graphene research through initiatives like the Graphene Flagship. The region focuses heavily on high-end industrial and automotive applications, particularly in Germany and the UK.
- Latin America & MEA: Emerging markets with growing interest in graphene for energy-efficient desalination and mining technologies, though currently representing a smaller share of the electronics-specific market.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Graphene Electronic Market.- Samsung Electronics
- IBM Corporation
- Graphenea S.A.
- Applied Materials, Inc.
- BASF SE
- Xerox Corporation
- LG Electronics
- Nokia
- Grafoid Inc.
- Graphene Frontiers
- Skeleton Technologies
- CVD Equipment Corporation
- NanoXplore Inc.
- Haydale Graphene Industries
- Talga Group
- Zen Graphene Solutions
- First Graphene Ltd.
- Graphene Manufacturing Group (GMG)
- Vorbeck Materials
- Global Graphene Group
Frequently Asked Questions
What is the current market size of the Graphene Electronic market?
The Graphene Electronic market is estimated to be valued at approximately USD 1.15 Billion in 2025, with rapid expansion expected as commercialization of GFETs and graphene sensors accelerates.
Why is graphene preferred over silicon in electronics?
Graphene offers significantly higher electron mobility, superior thermal conductivity, and extreme mechanical flexibility, allowing for faster, cooler, and flexible electronic devices that silicon cannot achieve at smaller scales.
Which application segment is expected to dominate the market?
The sensors segment currently dominates the market due to the high sensitivity and low power consumption of graphene-based biological and chemical sensors, followed closely by transparent conductive films.
What are the main challenges to mass-market Graphene Electronic?
The primary challenges include the lack of a natural energy bandgap for digital switching and the high cost and complexity of mass-producing defect-free, large-area graphene sheets.
Which region is the fastest-growing in the Graphene Electronic market?
North America is projected to be the fastest-growing region between 2025 and 2034, driven by intensive R&D in quantum computing, aerospace, and high-frequency communication electronics.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
