GCC Ceramic Tiles Market
GCC Ceramic Tiles Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711187 | Published On : October 15, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
GCC Ceramic Tiles Market Size
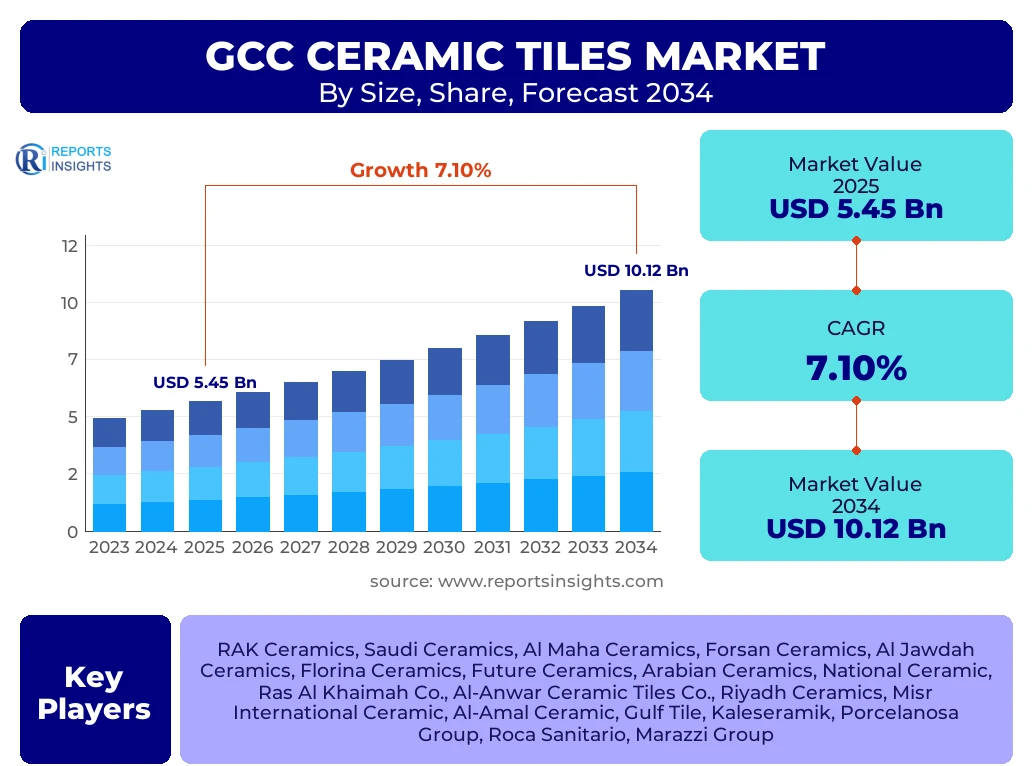
According to Reports Insights Consulting Pvt Ltd, The GCC Ceramic Tiles Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.1% between 2025 and 2034. The market is estimated at USD 5.84 Billion in 2026 and is projected to reach USD 10.12 Billion by the end of the forecast period in 2034.
Key GCC Ceramic Tiles Market Trends & Insights
The GCC Ceramic Tiles market is undergoing a structural transformation driven by large-scale infrastructure projects and a shift toward domestic manufacturing. Regional insights suggest that Saudi Arabia is the primary engine of growth, fueled by the Saudi Vision 2030 initiatives, which include giga-projects like NEOM and the Red Sea Project. Market analysis indicates a rising preference for high-value vitrified and porcelain tiles over traditional ceramic variants, as developers prioritize durability and aesthetic appeal for luxury commercial and residential spaces. Furthermore, the integration of 4.0 industrial technologies and digital printing has allowed local manufacturers to compete with high-end European imports by offering bespoke designs and textures that mimic natural stone and wood.
- Largest Region: Saudi Arabia currently holds the largest market share, accounting for over 45% of the total GCC consumption due to its massive construction pipeline and population growth.
- Fastest Growing Region: Qatar is anticipated to witness the fastest growth rate during the early forecast period, supported by ongoing infrastructure expansion and the diversification of its tourism and hospitality sectors.
- Largest Segment by Product: Floor tiles represent the largest segment in terms of volume and value, driven by extensive use in both residential and heavy-traffic commercial applications.
- Largest Segment by Application: The residential sector remains the leading application segment, though the commercial and institutional sectors are catching up rapidly due to the expansion of healthcare and educational facilities across the region.
- Technological Trend: The adoption of Large Format Slabs (LFS) is a significant trend, as they provide a seamless look and are increasingly favored for modern architectural projects.
Key Takeaways GCC Ceramic Tiles Market Size & Forecast
The GCC Ceramic Tiles market forecast is characterized by a strong emphasis on economic diversification away from oil, leading to unprecedented investments in the construction and real estate sectors. Users and stakeholders are increasingly focused on the resilience of the supply chain and the move toward sustainable building materials. The market is expected to witness significant consolidation as larger players leverage economies of scale to counter the rising costs of raw materials and energy. Overall, the regional outlook remains bullish, with infrastructure development serving as a permanent catalyst for demand throughout the next decade.
- Dominant Country: Saudi Arabia is the absolute leader in both production and consumption, positioning itself as the regional hub for ceramic manufacturing.
- Key Growth Driver: The rapid expansion of the hospitality industry in the UAE and Saudi Arabia is creating a sustained demand for premium-grade ceramic and porcelain products.
- Strategic Shift: There is a notable transition from importing low-cost tiles from Asia to sourcing locally manufactured, high-quality products to ensure timely project delivery and support national industry.
- Sustainability Focus: Increasing government regulations regarding green building standards are pushing manufacturers to adopt energy-efficient kilns and recycled water systems.
- Investment Climate: Foreign direct investment in the GCC’s manufacturing sector is expected to rise, particularly in the UAE and Oman, which are positioning themselves as export gateways for ceramic products.
GCC Ceramic Tiles Market Drivers Analysis
The primary driver for the GCC Ceramic Tiles market is the massive influx of government-led infrastructure and housing projects. Governments across the GCC are investing heavily in social infrastructure, including affordable housing units and public transport networks, to accommodate a growing expatriate and local population. This demand is further amplified by the expansion of the tourism sector, which necessitates the construction of thousands of new hotel rooms and entertainment venues.
Additionally, the shift toward "Made in GCC" initiatives is encouraging local production. Governments are providing subsidies and industrial land to ceramic manufacturers to reduce reliance on imports. This localization not only lowers transportation costs but also allows for better customization of products to suit the specific climatic conditions and cultural preferences of the Middle Eastern market.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Saudi Vision 2030 & Giga-Projects | +2.8% | Saudi Arabia | 2025 - 2034 |
| Urbanization and Housing Demand | +1.5% | UAE, Qatar, Kuwait | 2025 - 2030 |
| Hospitality and Tourism Expansion | +1.2% | UAE, Oman | 2026 - 2034 |
| Growth in Remodeling & Renovation | +0.9% | GCC-Wide | 2025 - 2034 |
GCC Ceramic Tiles Market Restraints Analysis
Despite the positive growth trajectory, the market faces significant restraints, particularly regarding the volatility of energy prices. Ceramic tile production is an energy-intensive process, and any fluctuations in natural gas or electricity tariffs directly impact the profit margins of local manufacturers. Additionally, the regional market is highly sensitive to global supply chain disruptions, which can lead to shortages of specific raw materials like high-grade clay and specialized chemicals used in glazing.
Another major restraint is the intense competition from low-cost imports from countries like China and India. While local governments have considered or implemented anti-dumping duties, the availability of cheaper alternatives continues to challenge the market share of premium GCC brands. Furthermore, the cyclical nature of the real estate market in some GCC countries can lead to periods of oversupply and price wars among manufacturers.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Energy Cost Fluctuations | -0.8% | GCC-Wide | 2025 - 2034 |
| Competition from Low-Cost Imports | -1.1% | UAE, Oman, Bahrain | 2025 - 2028 |
| Raw Material Supply Instability | -0.5% | GCC-Wide | 2026 - 2030 |
GCC Ceramic Tiles Market Opportunities Analysis
One of the most significant opportunities in the GCC Ceramic Tiles market lies in the development of sustainable and eco-friendly products. As green building certifications like LEED and Estidama become mandatory for new projects in the UAE and Qatar, there is a growing niche for tiles made from recycled materials and those that offer superior thermal insulation. Manufacturers who invest in carbon-neutral production processes are likely to gain a competitive edge in securing high-profile government contracts.
The rise of e-commerce and digital retail platforms also presents a unique opportunity for market expansion. While ceramic tiles were traditionally sold through physical showrooms, the emergence of B2B digital marketplaces is allowing manufacturers to reach developers and contractors more efficiently. Moreover, the export potential to neighboring African and South Asian markets remains high, as GCC-made tiles are increasingly recognized for their quality and durability.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Sustainable & Green Building Tiles | +1.4% | UAE, Saudi Arabia | 2026 - 2034 |
| Digitalization of Sales & B2B Platforms | +0.7% | GCC-Wide | 2025 - 2034 |
| Expansion into African Export Markets | +1.1% | Oman, UAE | 2027 - 2034 |
GCC Ceramic Tiles Market Challenges Impact Analysis
The primary challenge for the GCC Ceramic Tiles market is the increasing cost of regulatory compliance. As governments introduce stricter quality standards and environmental regulations, smaller manufacturers may struggle to upgrade their facilities, potentially leading to market consolidation. Additionally, the logistics of transporting heavy ceramic products across the region, despite improvements in rail networks, remains a cost challenge that affects the final retail price.
Furthermore, the high dependence on the construction sector means that any slowdown in regional infrastructure spending due to global economic factors or oil price dips can immediately impact tile demand. Ensuring a consistent skilled labor force for advanced manufacturing techniques and tile installation is also a persistent hurdle that the industry must address through better training and vocational programs.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Logistics & Transportation Costs | -0.4% | Saudi Arabia, Oman | 2025 - 2034 |
| Skilled Labor Shortages for Installation | -0.3% | Qatar, Kuwait | 2025 - 2030 |
| Strict Environmental Regulations | -0.6% | UAE, Saudi Arabia | 2026 - 2034 |
GCC Ceramic Tiles Market - Updated Report Scope
This report provides a comprehensive analysis of the GCC Ceramic Tiles market, covering production, consumption, and trade dynamics across all six member states. It delves into the granular details of product types, application areas, and end-user preferences, while providing a 10-year forecast to help stakeholders make informed investment decisions. The scope also includes a detailed evaluation of the competitive landscape and the impact of macro-economic factors on the industry's growth trajectory.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 5.45 Billion |
| Market Forecast in 2034 | USD 10.12 Billion |
| Growth Rate | 7.1% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | RAK Ceramics, Saudi Ceramics, Al Maha Ceramics, Forsan Ceramics, Al Jawdah Ceramics, Florina Ceramics, Future Ceramics, Arabian Ceramics, National Ceramic, Ras Al Khaimah Co., Al-Anwar Ceramic Tiles Co., Riyadh Ceramics, Misr International Ceramic, Al-Amal Ceramic, Gulf Tile, Kaleseramik, Porcelanosa Group, Roca Sanitario, Marazzi Group |
| Regions Covered | Middle East (GCC: Saudi Arabia, UAE, Qatar, Oman, Kuwait, Bahrain) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The GCC Ceramic Tiles market is segmented based on product type, application, end-user, and geography. Each segment is analyzed for its growth potential and contribution to the overall market revenue. The porcelain and vitrified segments are currently seeing the highest demand growth due to their superior performance in high-traffic and outdoor environments, which are common in the Middle Eastern climate. Floor tiles continue to dominate the application segment, while the residential sector remains the largest consumer of ceramic products.
- By Product Type:
- Ceramic Tiles (Glazed and Unglazed)
- Porcelain Tiles
- Vitrified Tiles
- Natural Stone Imitation Tiles
- By Application:
- Floor Tiles
- Wall Tiles
- Roofing Tiles and Others
- By End-User:
- Residential (New Construction & Replacement)
- Commercial (Hotels, Offices, Retail)
- Industrial (Factories, Warehouses)
- Institutional (Healthcare, Education, Public Infrastructure)
Regional Highlights
- Saudi Arabia: The largest market in the GCC, driven by the Vision 2030 initiatives and a massive surge in residential housing projects. It is also the primary manufacturing hub for the region.
- United Arab Emirates (UAE): The second-largest market, characterized by a demand for premium, high-aesthetic porcelain tiles for luxury real estate and hospitality projects in Dubai and Abu Dhabi.
- Qatar: Fastest growing in the short term due to post-World Cup infrastructure expansion and a renewed focus on the Qatar National Vision 2030.
- Oman: Emerging as a key exporter of ceramic tiles, utilizing its strategic location and local raw material availability to serve both GCC and international markets.
- Kuwait: Stable growth driven by long-term residential development plans and government-funded healthcare projects.
- Bahrain: A smaller but specialized market focused on high-quality niche products and renovation activities.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the GCC Ceramic Tiles Market.- RAK Ceramics (UAE)
- Saudi Ceramics (Saudi Arabia)
- Al Maha Ceramics (Oman)
- Forsan Ceramics (Saudi Arabia)
- Al Jawdah Ceramics (Saudi Arabia)
- Florina Ceramics (Saudi Arabia)
- Future Ceramics (Saudi Arabia)
- Arabian Ceramics (Saudi Arabia)
- National Ceramic (UAE)
- Ras Al Khaimah Co. (UAE)
- Al-Anwar Ceramic Tiles Co. (Oman)
- Riyadh Ceramics (Saudi Arabia)
- Misr International Ceramic (Egypt/GCC operations)
- Al-Amal Ceramic (GCC Distributor/Manufacturer)
- Gulf Tile (UAE)
- Kaleseramik (International Player with GCC footprint)
- Porcelanosa Group (International Player with GCC footprint)
- Roca Sanitario (International Player with GCC footprint)
- Marazzi Group (International Player with GCC footprint)
Frequently Asked Questions
What is the current market size of the GCC Ceramic Tiles industry?
The GCC Ceramic Tiles market is estimated to be worth USD 5.84 Billion in 2026, with a projected growth path leading to USD 10.12 Billion by 2034.
Which country in the GCC is the largest consumer of ceramic tiles?
Saudi Arabia is the largest consumer and producer of ceramic tiles in the GCC, accounting for nearly half of the total market share due to its extensive construction giga-projects.
What are the main drivers of growth in the GCC Ceramic Tiles market?
Key drivers include government-led infrastructure initiatives like Saudi Vision 2030, rapid urbanization, expansion of the hospitality and tourism sectors, and a shift toward local manufacturing.
What is the difference between porcelain and ceramic tiles in the GCC market?
Porcelain tiles are denser and more durable, making them ideal for high-traffic and outdoor areas in the harsh Middle Eastern climate, whereas ceramic tiles are generally more cost-effective for indoor residential wall and floor applications.
How is sustainability affecting tile manufacturing in the GCC?
Sustainability is driving manufacturers to adopt eco-friendly production methods, such as using recycled water and energy-efficient kilns, to comply with regional green building standards like LEED and Estidama.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
