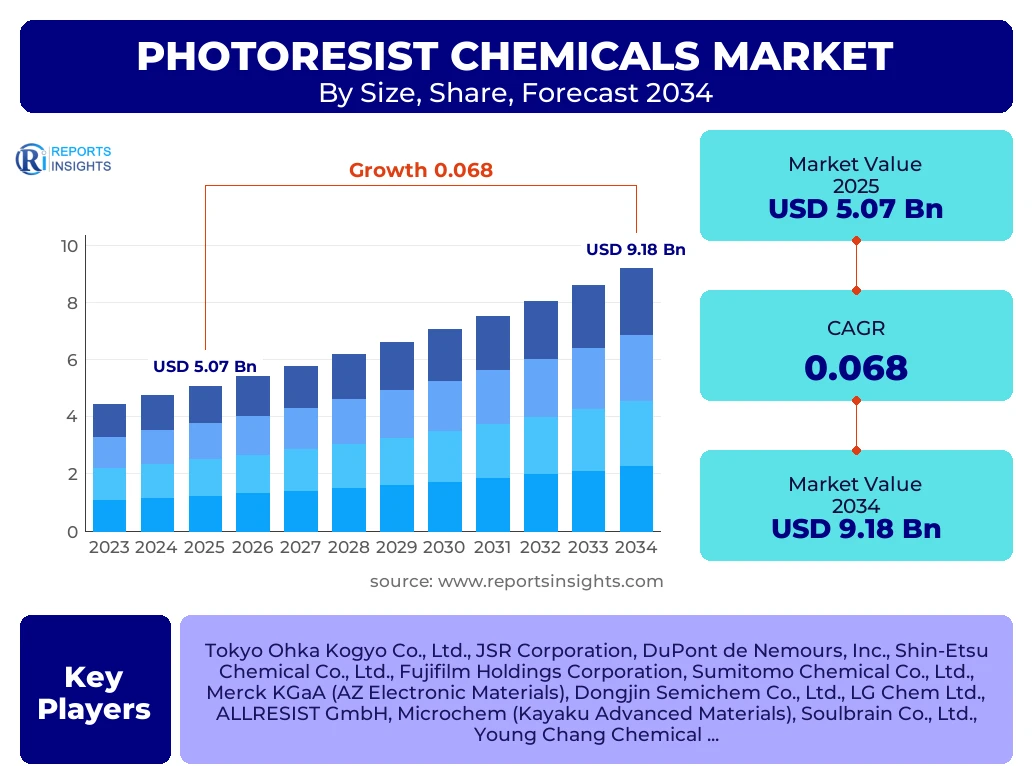
Photoresist Chemicals Market
Photoresist Chemicals Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711955 | Published On : November 22, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Photoresist Chemicals Market Size
According to Reports Insights Consulting Pvt Ltd, The Photoresist Chemicals Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.8% between 2025 and 2034. The market is estimated at USD 5.42 Billion in 2026 and is projected to reach USD 9.18 Billion by the end of the forecast period in 2034.
Key Photoresist Chemicals Market Trends & Insights
The global photoresist chemicals sector is currently navigating a transformative phase characterized by the rapid transition from Deep Ultraviolet (DUV) to Extreme Ultraviolet (EUV) lithography. This shift is primarily dictated by the semiconductor industrys relentless pursuit of miniaturization, aiming for sub-5nm and sub-3nm process nodes. Market intelligence suggests that the integration of artificial intelligence and machine learning in chip design is accelerating the demand for high-performance resists that offer superior resolution and sensitivity. Furthermore, the diversification of the global supply chain, moving beyond traditional hubs toward emerging manufacturing centers in Southeast Asia and India, is reshaping the competitive landscape and regional investment strategies.
- Largest Region: Asia Pacific remains the dominant force, accounting for over 55% of the total market share, driven by massive foundry operations in Taiwan, South Korea, and China.
- Fastest Growing Region: North America is poised for the most rapid growth due to the CHIPS Act and the resurgence of domestic advanced semiconductor manufacturing.
- Largest Segment: The Positive Photoresist segment holds the largest market share, valued for its higher thermal stability and superior resolution in complex circuit patterning.
- Key Technology Trend: The adoption of chemically amplified resists (CARs) and metal-oxide resists (MORs) is surging to meet the stringent requirements of EUV lithography systems.
Key Takeaways Photoresist Chemicals Market Size & Forecast
The trajectory of the Photoresist Chemicals market is intrinsically linked to the broader semiconductor fabrication materials index. Investors and stakeholders are increasingly focusing on the resilience of the specialty chemicals supply chain, particularly for high-purity monomers and photoacid generators. The forecast period highlights a robust expansion in the memory and logic sectors, with high-bandwidth memory (HBM) for AI servers acting as a primary volume driver for advanced photoresists.
- Taiwan: Leading country in terms of value, supported by the presence of the worlds largest contract chipmakers.
- South Korea: Major contributor to market volume, particularly in the KrF and ArF resist categories used for NAND and DRAM production.
- Sector Leadership: The semiconductor and IC segment is expected to maintain its lead over the PCB and LCD segments throughout the forecast period.
- Forecast Insight: By 2030, EUV photoresists are expected to represent approximately 25% of the total market revenue, up from single digits in the early 2020s.
Photoresist Chemicals Market Drivers Analysis
The market is propelled by a combination of technological advancements and structural shifts in the global electronics ecosystem. The surge in data center investments and the proliferation of high-performance computing (HPC) are necessitating more advanced lithography materials. Additionally, the electrification of the automotive sector, requiring sophisticated power management chips and sensors, provides a steady stream of demand for traditional g-line and i-line resists alongside advanced nodes.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advancements in EUV Lithography | +2.2% | Global (US, Taiwan, Netherlands) | 2025 - 2034 |
| Growth in AI and Data Center Infrastructure | +1.8% | North America & APAC | 2026 - 2032 |
| Expansion of 5G and IoT Connectivity | +1.4% | China & South Korea | 2025 - 2029 |
| Automotive Electronics Proliferation | +1.1% | Europe & Japan | 2027 - 2034 |
Photoresist Chemicals Market Restraints Analysis
Constraints within the market primarily revolve around the high complexity of chemical formulations and the stringent environmental regulations governing the use of Per- and Polyfluoroalkyl Substances (PFAS). These regulatory hurdles necessitate significant R&D expenditure to develop eco-friendly alternatives without compromising performance. Furthermore, the volatility in raw material prices, particularly for rare earth elements and specialized monomers, poses a threat to manufacturer margins.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Environmental (PFAS) Regulations | -1.2% | European Union & North America | 2025 - 2034 |
| Geopolitical Trade Tensions | -0.9% | US - China Corridor | 2025 - 2030 |
| High R&D and Manufacturing Costs | -0.7% | Global Market | Continuous |
Photoresist Chemicals Market Opportunities Analysis
Significant opportunities lie in the development of next-generation photoresists for advanced packaging techniques such as 2.5D and 3D stacking. As traditional Moore’s Law scaling becomes more challenging, the industry is looking toward heterogeneous integration, which requires specialized chemicals for redistribution layers (RDL) and through-silicon vias (TSV). Additionally, the emerging field of quantum computing and the push for domestic semiconductor self-sufficiency in various regions present untapped market potential for agile chemical suppliers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advanced Packaging (3D IC/Chiplets) | +1.9% | Taiwan, US, Japan | 2026 - 2034 |
| Development of Metal-Oxide Resists | +1.5% | South Korea & US | 2027 - 2034 |
| Regional Market Localisation (India/Vietnam) | +1.2% | APAC Emerging Markets | 2028 - 2034 |
Photoresist Chemicals Market Challenges Impact Analysis
The primary challenge remains the technical ceiling of current resist chemistries in the face of stochastic effects and line-edge roughness (LER) at extremely small scales. Achieving the balance between sensitivity, resolution, and roughness (the RLS trade-off) is a persistent hurdle for material scientists. Moreover, the long qualification cycles for new chemicals in semiconductor fabrication mean that market entry for new players is exceptionally difficult and capital-intensive.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| The RLS (Resolution, LER, Sensitivity) Trade-off | -1.1% | Advanced Node Manufacturers | 2025 - 2034 |
| Long Product Qualification Cycles | -0.8% | Global Tier-1 Suppliers | Ongoing |
| Shortage of High-Purity Raw Materials | -0.6% | Global Supply Chain | 2025 - 2028 |
Photoresist Chemicals Market - Updated Report Scope
This report provides an exhaustive analysis of the global photoresist chemicals market, covering the entire value chain from raw material suppliers to end-use semiconductor fabrication plants. The scope encompasses detailed volumetric and value-based forecasts, competitive intelligence, and a deep dive into the technological shifts impacting chemical formulations. Particular emphasis is placed on the regulatory landscape and the transition toward sustainable chemical manufacturing practices within the electronics industry.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 5.07 Billion |
| Market Forecast in 2034 | USD 9.18 Billion |
| Growth Rate | 6.8% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Tokyo Ohka Kogyo Co., Ltd., JSR Corporation, DuPont de Nemours, Inc., Shin-Etsu Chemical Co., Ltd., Fujifilm Holdings Corporation, Sumitomo Chemical Co., Ltd., Merck KGaA (AZ Electronic Materials), Dongjin Semichem Co., Ltd., LG Chem Ltd., ALLRESIST GmbH, Microchem (Kayaku Advanced Materials), Soulbrain Co., Ltd., Young Chang Chemical, Eternal Materials Co., Ltd., Chang Chun Group |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on the photochemical properties of the resists and the specific wavelength of light used during the exposure process. The transition from broadband i-line and g-line to excimer laser wavelengths (KrF and ArF) has been the cornerstone of the industry's growth for two decades. However, the current focus is on the EUV segment, which, despite its smaller current volume, commands significant value due to the extreme technical specifications required. Application-wise, the semiconductor and IC segment dominates, but the PCB segment remains a vital contributor, especially with the rise of High-Density Interconnect (HDI) boards.
- By Type:
- Positive Photoresist (Dominant segment due to resolution benefits)
- Negative Photoresist (Widely used in MEMS and specific PCB applications)
- By Chemistry:
- EUV (Extreme Ultraviolet - Fastest growing)
- ArF Immersion (193nm - High-volume advanced manufacturing)
- ArF Dry (Standard advanced node lithography)
- KrF (248nm - Mainstay for memory and mid-range logic)
- G-line & I-line (Broadband - Used for mature nodes and power chips)
- By Application:
- Semiconductors & ICs (Primary value driver)
- Printed Circuit Boards (PCBs) (Steady demand from consumer electronics)
- Liquid Crystal Displays (LCDs) (Significant use in large-area electronics)
- Others (MEMS, Sensors, Nanolithography)
Regional Highlights
The regional distribution of the Photoresist Chemicals market is heavily skewed toward the semiconductor manufacturing clusters of East Asia. Taiwan stands as the epicenter of the market, hosting the world's most advanced fabs that require high-purity EUV and ArF resists. South Korea follows closely, with a massive demand footprint generated by the memory giants. In China, the market is expanding rapidly as the government pushes for a localized electronic materials supply chain to mitigate geopolitical risks. Meanwhile, the United States is witnessing a resurgence in investment, with several major logic and memory fabrication plants under construction, which will significantly drive demand for advanced photoresists by the late 2020s. Europe remains a key center for research and development, particularly with the presence of ASML and leading chemical suppliers in Germany and the Netherlands.
- Asia Pacific: Currently the largest market, accounting for over half of global revenue, with Taiwan and South Korea leading in technology adoption.
- North America: Fastest-growing region due to strategic re-shoring of semiconductor manufacturing and heavy investment in R&D for next-gen lithography.
- Europe: A hub for lithography innovation and specialty chemical production, with a strong focus on automotive and industrial chip segments.
- China: Experiencing the highest growth rate in g-line and i-line resists as it expands its domestic legacy node production capacity.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Photoresist Chemicals Market.- Tokyo Ohka Kogyo Co., Ltd. (Japan)
- JSR Corporation (Japan)
- DuPont de Nemours, Inc. (USA)
- Shin-Etsu Chemical Co., Ltd. (Japan)
- Fujifilm Holdings Corporation (Japan)
- Sumitomo Chemical Co., Ltd. (Japan)
- Merck KGaA (Germany)
- Dongjin Semichem Co., Ltd. (South Korea)
- LG Chem Ltd. (South Korea)
- Allresist GmbH (Germany)
- Kayaku Advanced Materials, Inc. (USA)
- Soulbrain Co., Ltd. (South Korea)
- Young Chang Chemical (South Korea)
- Eternal Materials Co., Ltd. (Taiwan)
- Chang Chun Group (Taiwan)
- San-Apro Ltd. (Japan)
- Daikin Industries, Ltd. (Japan)
- Toyo Gosei Co., Ltd. (Japan)
Frequently Asked Questions
What is the primary driver for the growth of the Photoresist Chemicals Market through 2034?
The primary driver is the global expansion of semiconductor manufacturing capacity, specifically for advanced nodes using EUV lithography to support AI, 5G, and high-performance computing applications.
Which type of photoresist is expected to dominate the market share?
Positive photoresists are expected to maintain dominance due to their superior resolution and thermal stability, which are critical for the intricate patterning required in modern integrated circuits.
How are environmental regulations affecting the photoresist chemical industry?
Stricter regulations on PFAS and other hazardous chemicals are forcing manufacturers to invest heavily in the research and development of sustainable, "green" photoresist formulations that meet environmental standards without losing performance.
Why is the Asia Pacific region so influential in this market?
Asia Pacific is the global hub for semiconductor fabrication, housing major foundry and IDM players in Taiwan, South Korea, and China, which collectively account for the vast majority of photoresist chemical consumption.
What role does EUV lithography play in the future of the market?
EUV lithography is the critical technology for manufacturing sub-7nm chips. The transition to EUV necessitates the use of high-value, specialized photoresists, making it the most significant growth area for revenue in the industry.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
