Gas Detection Equipment Market
Gas Detection Equipment Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_703560 | Published On : September 07, 2026 |
Format : 


 | Author : Jonathan Sikka
Gas Detection Equipment Market Size
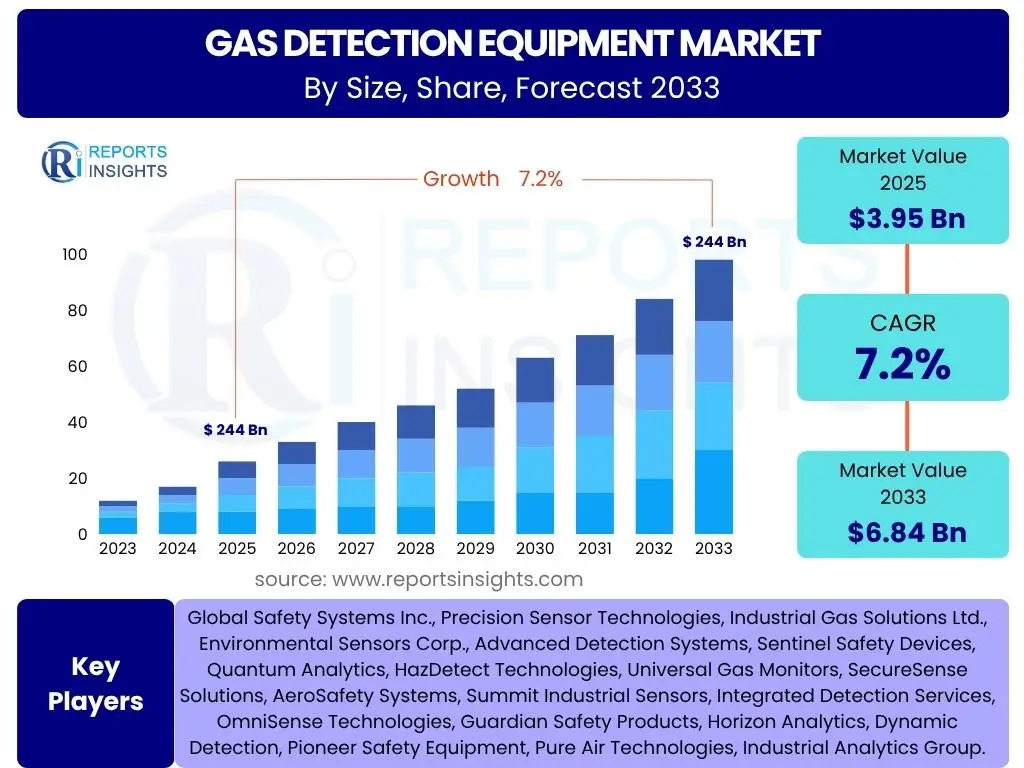
According to Reports Insights Consulting Pvt Ltd, The Gas Detection Equipment Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.8% between 2026 and 2034. The market is estimated at USD 5.34 Billion in 2026 and is projected to reach USD 9.76 Billion by the end of the forecast period in 2034.
Key Gas Detection Equipment Market Trends & Insights
The global landscape for gas detection equipment is undergoing a profound transformation driven by the integration of Industrial Internet of Things (IIoT) and wireless connectivity. Enterprises are increasingly shifting from standalone, reactive detection systems to integrated, cloud-based monitoring ecosystems that provide real-time data visualization and predictive maintenance capabilities. This shift is particularly evident in large-scale industrial facilities where the cost of downtime and the risk of catastrophic failure necessitate high-precision, low-latency monitoring solutions. Furthermore, the miniaturization of sensor technology has enabled the development of high-performance portable detectors that offer enhanced ergonomics without compromising on accuracy or battery life.
Market intelligence indicates that the convergence of artificial intelligence and sensor fusion is becoming a primary differentiator for leading equipment manufacturers. By utilizing machine learning algorithms to filter out cross-interfering gases and environmental noise, modern detectors provide higher reliability and fewer false alarms. The demand for multi-gas detection systems—capable of identifying combustible, toxic, and oxygen-depleting gases simultaneously—remains a dominant trend in high-risk sectors such as oil and gas, chemical processing, and wastewater treatment. Additionally, regional insights suggest that infrastructure modernization in emerging economies is accelerating the adoption of fixed gas detection systems in commercial and residential applications.
- Largest Region: North America currently holds the largest market share, driven by stringent workplace safety regulations enforced by OSHA and the high concentration of shale gas exploration activities.
- Fastest Growing Region: Asia Pacific is the fastest-growing region due to rapid industrialization, increasing investments in smart city projects, and expanding manufacturing hubs in China, India, and Southeast Asia.
- Largest Segment: Fixed Gas Detection Equipment remains the largest product segment by value, supported by extensive infrastructure projects and mandatory installation requirements in industrial plants.
- Leading Technology: Infrared (IR) and Electrochemical sensor technologies continue to lead the market share owing to their reliability, longevity, and high sensitivity to specific hazardous gases.
Key Takeaways Gas Detection Equipment Market Size & Forecast
The market trajectory for gas detection equipment remains robust, underpinned by a global tightening of occupational health and safety standards. Organizations are allocating significant capital expenditures toward upgrading legacy safety systems to comply with modern ESG (Environmental, Social, and Governance) mandates. The forecast period highlights a significant transition toward "Safety-as-a-Service" models, where companies utilize subscription-based monitoring and maintenance programs to manage their gas detection fleets. This model reduces initial capital outlays and ensures that equipment is always calibrated and functionally compliant with local safety codes.
Geopolitically, the focus on energy security and the expansion of Liquefied Natural Gas (LNG) terminals across Europe and North America are creating localized surges in demand for explosion-proof detection systems. The rise of the hydrogen economy is another critical factor, as specialized detectors for hydrogen (H2) are becoming essential in newly established production and storage facilities. Stakeholders should anticipate a steady increase in market valuation as technological advancements reduce the total cost of ownership, making high-end detection solutions accessible to small and medium-sized enterprises (SMEs).
- Sustainability Focus: Increasing focus on reducing methane leaks in the oil and gas sector to meet global emissions targets is a primary growth engine.
- Technological Synergy: Integration with Building Management Systems (BMS) and Fire Alarm Systems is enhancing the utility of fixed detectors in commercial real estate.
- Portable Dominance: The rising popularity of single-gas and multi-gas portable detectors for personal protection in confined space entry operations.
- Regional Leadership: The United States, Germany, China, and Saudi Arabia represent the most lucrative national markets for high-precision gas sensing equipment.
Gas Detection Equipment Market Drivers Analysis
The primary growth catalyst for the gas detection equipment market is the increasingly stringent regulatory framework governing industrial safety and environmental protection. Agencies such as OSHA in the United States and the Health and Safety Executive (HSE) in the UK continue to update mandates for hazardous gas monitoring, compelling industries to adopt the latest detection technologies. Furthermore, the rapid expansion of the chemical and petrochemical industries in developing regions necessitates extensive safety infrastructure to mitigate the risk of toxic leaks and explosive atmospheres.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Occupational Safety Regulations | +2.5% | Global (Strongest in North America & Europe) | 2025 - 2034 |
| Expansion of Oil & Gas Exploration | +1.8% | Middle East, North America, Russia | 2025 - 2030 |
| Integration of IIoT and Wireless Monitoring | +2.1% | USA, Germany, Japan, South Korea | 2026 - 2034 |
| Rise of Hydrogen Fuel Production | +1.4% | Europe, Japan, Australia | 2028 - 2034 |
Gas Detection Equipment Market Restraints Analysis
Despite strong growth, the market faces challenges related to high initial procurement and installation costs, particularly for sophisticated fixed detection systems with integrated wireless networking. Additionally, the need for frequent calibration and maintenance can be a significant operational burden for smaller companies, leading to longer replacement cycles. Technical limitations, such as sensor cross-sensitivity and vulnerability to harsh environmental conditions like extreme humidity or high temperature, can also hinder the adoption of certain detector types in specialized industrial settings.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Specialized IR and Laser Sensors | -1.1% | Developing Economies | 2025 - 2030 |
| Technical Limitations & False Alarms | -0.8% | Global Industrial Sectors | 2025 - 2034 |
| Short Lifespan of Electrochemical Sensors | -0.6% | Global | 2025 - 2034 |
Gas Detection Equipment Market Opportunities Analysis
The ongoing transition toward "Smart Factories" and Industry 4.0 presents a significant opportunity for manufacturers to offer predictive analytics and remote monitoring services alongside hardware. The burgeoning sector of green hydrogen production requires specialized, high-sensitivity detection equipment that can operate in unique environments. Moreover, the increasing public awareness of indoor air quality (IAQ) is opening new revenue streams in the residential and commercial HVAC markets, where gas sensors are used to monitor carbon dioxide, volatile organic compounds (VOCs), and carbon monoxide levels.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Safety-as-a-Service Models | +2.2% | North America, Europe | 2026 - 2034 |
| Smart City & Infrastructure Projects | +1.9% | China, India, Saudi Arabia, UAE | 2027 - 2034 |
| Indoor Air Quality Monitoring in Smart Buildings | +1.5% | Global Metro Cities | 2025 - 2034 |
Gas Detection Equipment Market Challenges Impact Analysis
Supply chain volatility remains a persistent challenge, particularly concerning the sourcing of semiconductor components and specialized chemicals required for sensor manufacturing. Furthermore, the lack of standardized communication protocols for wireless gas detection systems can lead to interoperability issues when integrating equipment from multiple vendors into a single facility management system. Cybersecurity risks associated with cloud-connected safety devices also represent a critical challenge that manufacturers must address to gain the trust of highly sensitive industrial operators.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Semiconductor Supply Chain Disruptions | -0.9% | Global Manufacturers | 2025 - 2027 |
| Interoperability and Standardization Issues | -0.7% | Industrial Automation Markets | 2025 - 2034 |
| Cybersecurity Vulnerabilities in IoT Devices | -0.5% | Advanced Industrial Markets | 2026 - 2034 |
Gas Detection Equipment Market - Updated Report Scope
This comprehensive report provides a detailed quantitative and qualitative analysis of the global gas detection equipment market, covering historical performance and future projections across all major segments and geographies. It includes deep dives into sensor technologies, product configurations, and end-user industries to provide stakeholders with actionable intelligence for strategic decision-making.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 4.95 Billion |
| Market Forecast in 2034 | USD 9.76 Billion |
| Growth Rate | 7.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Honeywell International Inc., MSA Safety Incorporated, Drägerwerk AG & Co. KGaA, Emerson Electric Co., ABB Ltd., Siemens AG, Industrial Scientific Corporation (Fortive), Riken Keiki Co., Ltd., Thermo Fisher Scientific Inc., Hanwei Electronics Group Corporation, GfG Gesellschaft für Gerätebau mbH, Teledyne Gas & Flame Detection, New Cosmos Electric Co., Ltd., Crowcon Detection Instruments Ltd., Trolex Ltd., United Electric Controls, Sensit Technologies, Bacharach Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The gas detection equipment market is segmented based on product configuration, gas type, sensing technology, and end-use vertical. This granular approach allows for a precise understanding of where the highest demand resides. Fixed gas detectors currently command the largest share of the market, as they are integral to the permanent safety infrastructure of manufacturing plants and energy facilities. However, portable detectors are seeing rapid growth due to their increasing use in personal protective equipment (PPE) for workers entering hazardous or confined spaces. By technology, electrochemical sensors are the most common due to their versatility in detecting toxic gases, while infrared sensors are gaining traction for flammable gas detection due to their long life and low maintenance requirements.
- Product Type:
- Fixed Gas Detectors
- Portable Gas Detectors
- Gas Type:
- Flammable Gases
- Toxic Gases (H2S, CO, NH3, SO2)
- Oxygen Displacement
- Volatile Organic Compounds (VOCs)
- Technology:
- Electrochemical
- Infrared (Point & Open Path)
- Catalytic Bead (Pellistor)
- Photoionization (PID)
- Tunable Laser Diode Absorption Spectroscopy (TDLAS)
- Semiconductor
- End-Use Industry:
- Oil & Gas (Upstream, Midstream, Downstream)
- Chemical & Petrochemical
- Mining & Metallurgy
- Water & Wastewater Treatment
- Power Generation (Nuclear, Thermal, Renewables)
- Manufacturing & Food Processing
- Healthcare & Laboratories
- Residential & Commercial Safety
Regional Highlights
North America remains the dominant force in the gas detection market, largely due to the rigorous safety standards set by OSHA and the EPA, combined with a highly developed oil and gas infrastructure. The United States and Canada are seeing significant investment in methane emission reduction technologies. In Europe, the market is driven by environmental directives and the rapid development of hydrogen energy networks, particularly in Germany, the UK, and the Scandinavian countries. The ATEX and IECEx certifications remain critical hurdles and drivers for high-specification equipment in these regions.
The Asia Pacific region is the fastest-growing market, propelled by the massive industrial expansion in China, India, and Vietnam. Increasing government focus on workplace safety and the growth of the semiconductor and chemical industries are key drivers here. In the Middle East, the continued focus on maximizing hydrocarbon production efficiency and the construction of massive new desalination and petrochemical plants in Saudi Arabia and the UAE provide a stable and high-value market for fixed detection systems.
- North America: Largest market share; focus on shale gas and advanced wireless safety networks.
- Europe: Leading in environmental sensing and hydrogen-specific detection technology.
- Asia Pacific: Highest growth rate; driven by rapid industrialization and smart city infrastructure.
- Middle East & Africa: Significant demand for explosion-proof and high-reliability systems in the energy sector.
- Latin America: Growing demand in mining and offshore oil exploration in Brazil and Chile.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Gas Detection Equipment Market.- Honeywell International Inc.
- MSA Safety Incorporated
- Drägerwerk AG & Co. KGaA
- Emerson Electric Co.
- ABB Ltd.
- Siemens AG
- Industrial Scientific Corporation
- Riken Keiki Co., Ltd.
- Thermo Fisher Scientific Inc.
- Hanwei Electronics Group Corporation
- GfG Gesellschaft für Gerätebau mbH
- Teledyne Gas & Flame Detection
- New Cosmos Electric Co., Ltd.
- Crowcon Detection Instruments Ltd.
- Trolex Ltd.
- United Electric Controls
- Sensit Technologies
- Bacharach Inc.
- Gas Measurement Instruments Ltd.
- Ion Science Ltd.
Frequently Asked Questions
What is driving the growth of the Gas Detection Equipment Market through 2034?
Growth is primarily driven by increasingly strict global occupational safety regulations, the integration of IIoT for real-time monitoring, and a heightened focus on environmental sustainability, particularly regarding methane leak detection in the energy sector.
Which technology is most preferred for toxic gas detection?
Electrochemical sensors are the preferred technology for toxic gas detection because they offer high sensitivity, low power consumption, and the ability to detect a wide range of gases such as carbon monoxide, hydrogen sulfide, and chlorine.
How is the rise of the hydrogen economy affecting the market?
The hydrogen economy is creating a new demand for specialized detection systems because hydrogen is highly flammable and difficult to detect with traditional sensors. This is leading to the development of specialized laser and semiconductor sensors.
What are the benefits of wireless gas detection systems over wired systems?
Wireless systems significantly reduce installation costs, offer greater flexibility for deployment in remote or hard-to-access areas, and allow for rapid scalability and integration with cloud-based data management platforms.
Which region is expected to offer the most significant growth opportunities?
Asia Pacific is expected to offer the most significant growth opportunities due to rapid industrialization, expanding manufacturing sectors, and increasing government investments in safety infrastructure across China, India, and Southeast Asian nations.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
