Flip Chip Market
Flip Chip Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711661 | Published On : November 11, 2026 |
Format : 


 | Author : Shamin Verma
Flip Chip Market Size
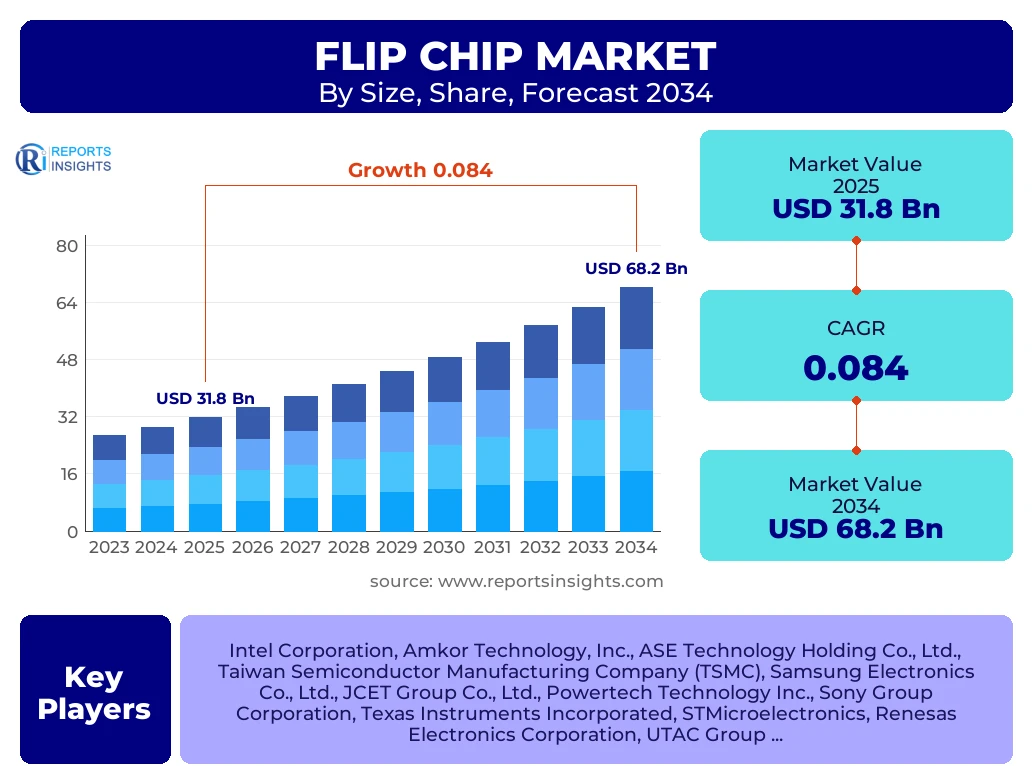
According to Reports Insights Consulting Pvt Ltd, The Flip Chip Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.4% between 2025 and 2034. The market is estimated at USD 34.5 Billion in 2026 and is projected to reach USD 68.2 Billion by the end of the forecast period in 2034.
Key Flip Chip Market Trends & Insights
The Flip Chip market is currently undergoing a transformative phase characterized by the shift toward high-density interconnects and the rapid adoption of copper pillar technology. As semiconductor nodes shrink toward 3nm and below, traditional wire bonding reaches its physical limits, making Flip Chip packaging essential for maintaining signal integrity and power efficiency. The integration of Flip Chip technology within Advanced Driver Assistance Systems (ADAS) and high-performance computing (HPC) environments is driving a new wave of structural demand. Market participants are increasingly focusing on thermal management solutions and the miniaturization of bumps to facilitate the next generation of artificial intelligence (AI) accelerators and 5G infrastructure components. Strategic benchmarking reveals a move toward heterogeneous integration, where multiple dies are packaged using Flip Chip interconnects to optimize performance per watt.
- Largest Region: Asia Pacific remains the dominant regional market, accounting for over 60% of the global share due to the concentration of semiconductor foundries and OSAT providers in Taiwan, China, and South Korea.
- Fastest Growing Region: North America is poised for the highest growth rate during the forecast period, driven by massive investments in domestic semiconductor manufacturing and the presence of leading AI chip designers.
- Largest Segment: The Flip Chip Ball Grid Array (FC-BGA) segment holds the largest market share, serving as the standard packaging format for high-performance processors and graphics units.
- Technological Shift: Copper Pillar bumping is rapidly outpacing traditional solder bumping as the preferred interconnect method due to its superior pitch density and thermal characteristics.
Key Takeaways Flip Chip Market Size & Forecast
The global Flip Chip market trajectory is fundamentally linked to the proliferation of data-intensive applications and the electrification of the automotive sector. Analysts observe that the transition from 4G to 5G has significantly increased the silicon content per device, necessitating more efficient packaging solutions like Flip Chip to handle higher frequencies and heat dissipation. Furthermore, the rise of "Chiplet" architectures is reinforcing the necessity of Flip Chip interconnects as a primary building block for modular semiconductor design. The forecast suggests that while consumer electronics will remain a high-volume driver, the enterprise server and automotive segments will contribute the highest value-added growth over the next decade.
- Market Leadership: Taiwan continues to lead the global landscape, hosting the world's most advanced flip-chip assembly lines and specialized bumping services.
- Growth Engine: The automotive electronics sector is expected to witness a CAGR exceeding 10% within the Flip Chip market, fueled by the demand for sophisticated Infotainment and autonomous driving chips.
- Infrastructure Demand: Cloud service providers' expansion of data centers is creating a sustained demand for high-end FC-BGA packages.
- Supply Chain Resilience: There is a notable trend toward regionalizing the supply chain, with significant subsidies in the US and Europe encouraging the establishment of advanced packaging facilities closer to end-users.
Flip Chip Market Drivers Analysis
The primary driver for the Flip Chip market is the relentless demand for high-performance computing power in the era of Generative AI. As AI models become more complex, the hardware required to train them demands massive bandwidth and low latency, which Flip Chip technology provides through shorter interconnect paths compared to wire bonding. Additionally, the miniaturization of consumer electronics, specifically wearables and flagship smartphones, necessitates the compact form factor offered by Flip Chip CSP (Chip Scale Packaging). The transition toward 5G networks further accelerates this trend, as the technology requires chips that can operate at high frequencies with minimal signal loss.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of AI Data Centers | +2.8% | United States, China | 2025 - 2034 |
| Automotive Electrification & ADAS | +2.1% | Germany, Japan, South Korea | 2026 - 2034 |
| 5G Telecommunications Rollout | +1.5% | Global | 2025 - 2030 |
| Consumer Electronics Miniaturization | +1.2% | China, Vietnam, India | 2025 - 2034 |
Flip Chip Market Restraints Analysis
Despite the robust growth, the market faces significant restraints primarily centered on the high initial capital expenditure required for advanced packaging equipment. The complexity of the flip-chip assembly process, which requires high-precision placement and sophisticated cleaning cycles, leads to higher production costs compared to traditional methods. Furthermore, the volatility in raw material prices, particularly for high-purity copper and specialized underfill materials, can squeeze the profit margins of OSAT (Outsourced Semiconductor Assembly and Test) providers. Technical limitations regarding thermal mismatch between the chip and the substrate also pose ongoing engineering challenges that can delay product time-to-market.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Capital Expenditure (CAPEX) | -1.4% | Global (Impacts SME players) | 2025 - 2028 |
| Complexity in Substrate Manufacturing | -0.9% | Japan, Taiwan | 2025 - 2034 |
| Raw Material Price Volatility | -0.6% | Global | 2025 - 2034 |
Flip Chip Market Opportunities Analysis
The emergence of the "Internet of Everything" (IoE) presents a substantial opportunity for the Flip Chip market, as billions of edge devices require energy-efficient and compact processing units. There is also a significant opening in the development of lead-free and environment-friendly bumping materials, driven by stringent global environmental regulations. Moreover, the integration of Flip Chip with 2.5D and 3D packaging technologies offers a pathway for manufacturers to deliver unprecedented performance gains, especially for high-bandwidth memory (HBM) and logic stacking. Strategic partnerships between foundries and OSATs to create integrated "Turnkey" solutions are expected to unlock new revenue streams.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of Chiplet Architecture | +2.5% | United States, Taiwan | 2026 - 2034 |
| Edge Computing and IoT Devices | +1.8% | Global | 2027 - 2034 |
| Next-Gen Power Electronics (GaN/SiC) | +1.3% | Europe, Japan | 2025 - 2034 |
Flip Chip Market Challenges Impact Analysis
One of the most pressing challenges in the Flip Chip market is the thermal management of high-power density chips. As chips get smaller and more powerful, dissipating the heat generated at the flip-chip joints becomes increasingly difficult, potentially leading to reliability issues. Additionally, the industry faces a shortage of skilled labor capable of managing advanced lithography and bonding processes. Competitive pressure from alternative packaging technologies, such as Fan-Out Wafer-Level Packaging (FOWLP), also forces Flip Chip players to constantly innovate to maintain their market relevance. Finally, geopolitical tensions affecting the semiconductor supply chain remain a critical challenge for global capacity planning.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Thermal Dissipation at Fine Pitches | -1.1% | Global | 2025 - 2034 |
| Supply Chain Geopolitical Risks | -0.8% | APAC, North America | 2025 - 2030 |
| Competition from FOWLP Technology | -0.7% | Global | 2026 - 2034 |
Flip Chip Market - Updated Report Scope
The Flip Chip market report provides a granular analysis of the global landscape, encompassing the entire value chain from wafer bumping to final assembly and testing. It evaluates the impact of macroeconomic factors, such as inflation and trade policies, on market growth. The scope includes a detailed breakdown of different bumping technologies, packaging formats, and their specific adoption rates across key industry verticals. This report serves as a strategic roadmap for stakeholders looking to navigate the complexities of the semiconductor packaging industry over the next decade, offering data-backed insights into emerging technologies and regional investment hotspots.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 31.8 Billion |
| Market Forecast in 2034 | USD 68.2 Billion |
| Growth Rate | 8.4% CAGR |
| Number of Pages | 274 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Intel Corporation, Amkor Technology, Inc., ASE Technology Holding Co., Ltd., Taiwan Semiconductor Manufacturing Company (TSMC), Samsung Electronics Co., Ltd., JCET Group Co., Ltd., Powertech Technology Inc., Sony Group Corporation, Texas Instruments Incorporated, STMicroelectronics, Renesas Electronics Corporation, UTAC Group, Chipbond Technology Corporation, Nepes Corporation, Fujitsu Limited, Qualcomm Incorporated, United Microelectronics Corporation (UMC). |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Flip Chip market is segmented based on the bumping process, packaging type, and end-use application. The move toward fine-pitch requirements has made Copper Pillar the fastest-growing sub-segment, as it allows for smaller bumps and better electrical performance. In terms of packaging technology, FC-BGA remains the workhorse for high-end computing, while FC-CSP is dominant in mobile devices due to its small footprint. The application landscape is diversifying, with automotive electronics emerging as a significant growth pillar alongside the traditional dominance of IT and telecommunications.
- By Wafer Bumping Process:
- Copper Pillar
- Solder Bumping
- Gold Bumping
- Tin-Lead Bumping
- By Packaging Technology:
- Flip Chip Ball Grid Array (FC-BGA)
- Flip Chip Chip Scale Package (FC-CSP)
- Flip Chip Land Grid Array (FC-LGA)
- Flip Chip Pin Grid Array (FC-PGA)
- By Product Type:
- Microprocessors (CPUs/GPUs)
- Memory (DRAM/NAND)
- Power Management ICs (PMICs)
- RF Devices
- Image Sensors
- By End-Use Industry:
- Consumer Electronics (Smartphones, Tablets, Laptops)
- IT & Telecommunications (Servers, Network Infrastructure)
- Automotive (ADAS, Infotainment, EV Powertrains)
- Industrial & Medical Devices
- Aerospace & Defense
Regional Highlights
The regional analysis of the Flip Chip market reveals a highly concentrated production base in Asia Pacific, contrasting with a strong design and demand hub in North America. Taiwan remains the epicenter of the market, driven by the synergy between advanced foundries and dedicated packaging houses. Mainland China is rapidly expanding its domestic OSAT capacity, supported by government initiatives to achieve semiconductor self-sufficiency. In North America, the market is bolstered by the presence of major fabless companies and a surge in high-performance computing infrastructure. Europe’s market is heavily influenced by its strong automotive sector, where Flip Chip technology is increasingly utilized for power electronics and safety-critical sensors. Japan maintains a leadership position in specialized materials and high-precision equipment essential for Flip Chip manufacturing.
- Asia Pacific: Holds the largest market share (approx. 62%) and is the hub for mass manufacturing and OSAT services.
- North America: The fastest-growing region with a projected CAGR of 9.1%, driven by AI-led data center expansions.
- Europe: Leading in the adoption of Flip Chip for automotive and industrial IoT applications, particularly in Germany and France.
- Taiwan: Remains the single largest country contributor to market value due to its advanced packaging ecosystem.
- South Korea: A major player in memory-centric flip-chip packaging, supporting the global HBM and DRAM markets.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Flip Chip Market.- Intel Corporation
- Amkor Technology, Inc.
- ASE Technology Holding Co., Ltd.
- Taiwan Semiconductor Manufacturing Company (TSMC)
- Samsung Electronics Co., Ltd.
- JCET Group Co., Ltd.
- Powertech Technology Inc.
- Sony Group Corporation
- Texas Instruments Incorporated
- STMicroelectronics
- Renesas Electronics Corporation
- UTAC Group
- Chipbond Technology Corporation
- Nepes Corporation
- Fujitsu Limited
- Qualcomm Incorporated
- United Microelectronics Corporation (UMC)
- King Yuan Electronics Co., Ltd. (KYEC)
- ChipMOS Technologies Inc.
Frequently Asked Questions
The following section addresses the most common inquiries regarding the Flip Chip market dynamics, technological shifts, and investment outlook.
What is driving the transition from wire bonding to flip chip packaging?
The transition is primarily driven by the need for higher interconnect density, better electrical performance, and superior thermal management. Flip Chip allows for connections across the entire surface of the die rather than just the edges, significantly reducing inductance and enabling smaller device footprints.
Why is Copper Pillar bumping gaining popularity over traditional solder bumping?
Copper Pillar bumping offers a much finer pitch, allowing for more I/Os in a smaller area. It also provides better thermal conductivity and higher electromigration resistance, making it ideal for high-power applications like AI processors and 5G chipsets.
Which industry vertical is expected to see the fastest growth in Flip Chip adoption?
While consumer electronics remains the largest volume user, the Automotive sector is expected to see the fastest growth rate. This is due to the increasing integration of semiconductors in electric vehicles and the high reliability required for autonomous driving systems.
How do geopolitical tensions affect the global Flip Chip supply chain?
Geopolitical tensions have led to a push for regionalization. Countries are offering subsidies (like the CHIPS Act) to encourage the building of advanced packaging facilities domestically to reduce reliance on a few concentrated hubs in East Asia and secure the supply chain for critical technologies.
What are the main technical challenges in scaling Flip Chip technology?
The primary challenges include managing the thermal expansion mismatch between the silicon die and the organic substrate, ensuring underfill reliability in very narrow gaps, and maintaining high yields as the bump pitch continues to shrink below 40 microns.
Author
S
Shamin Verma is a Senior Analyst Semiconductor and Electronics Research with over 7+ years of experience in the Semiconductor and Electronics Industry. She specializes in semiconductor market intelligence, electronics supply chain analysis, wafer fabrication trends, competitive benchmarking, demand forecasting, component pricing analysis, emerging technology assessment, integrated circuit market evaluation, and industry ecosystem research. Her expertise in translating complex market data into strategic insights enables organizations to make informed business decisions, identify high-growth opportunities, optimize operational planning, anticipate evolving technology trends, and strengthen their competitive positioning in the global semiconductor and electronics market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
