Fire Protection System Market
Fire Protection System Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711486 | Published On : November 03, 2026 |
Format : 


 | Author : Jonathan Sikka
Fire Protection System Market Size
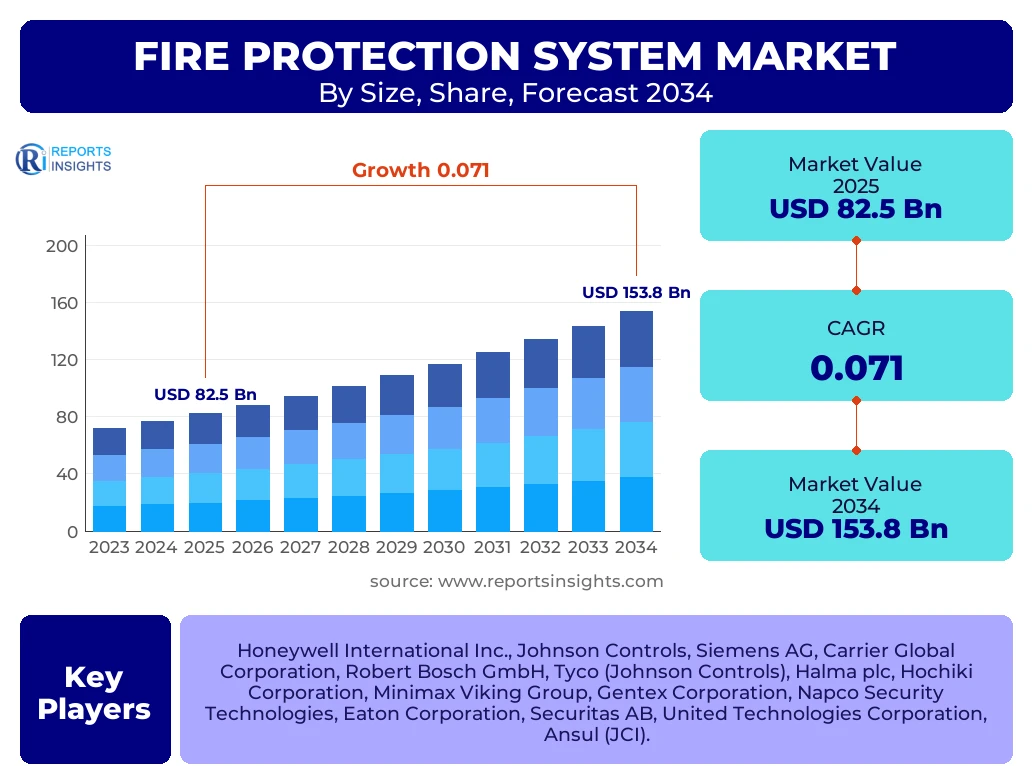
According to Reports Insights Consulting Pvt Ltd, The Fire Protection System Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.1% between 2025 and 2034. The market is estimated at USD 88.4 Billion in 2026 and is projected to reach USD 153.8 Billion by the end of the forecast period in 2034.
The global fire protection system market is undergoing a period of significant transformation driven by the rapid integration of digital technologies and the heightening of global safety standards. As urban centers expand and the complexity of industrial infrastructure increases, the demand for sophisticated detection and suppression mechanisms has shifted from a regulatory compliance necessity to a core component of enterprise risk management. The convergence of the Internet of Things (IoT) with fire safety hardware is enabling real-time monitoring and predictive maintenance, which significantly reduces the likelihood of catastrophic failure and operational downtime.
Recent valuations indicate that the commercial and industrial sectors remain the primary contributors to market revenue, fueled by large-scale investments in smart buildings and hazardous manufacturing environments. Additionally, the transition toward sustainable and eco-friendly fire suppression agents is reshaping the competitive landscape. Stakeholders are increasingly prioritizing systems that offer not only high reliability but also minimal environmental impact, aligning fire safety protocols with broader corporate ESG (Environmental, Social, and Governance) objectives.
Key Fire Protection System Market Trends & Insights
The fire protection sector is characterized by a shift toward intelligent, interconnected systems that leverage cloud computing and big data analytics to enhance situational awareness. Regional insights suggest that while North America continues to lead in terms of technological adoption and stringent enforcement of NFPA codes, the Asia-Pacific region is emerging as the fastest-growing market due to massive infrastructure development in China and India. Competitive benchmarking reveals that top-tier companies are focusing on modular system designs and wireless detection technologies to cater to the retrofitting needs of aging urban structures without extensive rewiring costs.
- Fastest Growing Region: Asia-Pacific, driven by rapid urbanization and stringent new safety mandates in emerging economies.
- Largest Market Share: North America, supported by a mature regulatory environment and high adoption of advanced smoke detection and suppression technologies.
- Dominant Product Segment: Fire Detection Systems, specifically multi-sensor detectors that integrate heat, smoke, and CO sensing capabilities.
- Leading Application: Commercial sector, encompassing high-rise offices, retail complexes, and healthcare facilities.
- Emerging Technology: Voice Evacuation Systems and AI-driven predictive fire analytics platforms.
Key Takeaways Fire Protection System Market Size & Forecast
The market trajectory is heavily influenced by the global movement toward smart city initiatives and the automation of industrial processes. Investors and stakeholders are observing a significant uptick in the demand for integrated fire protection suites that communicate directly with building management systems (BMS). This integration allows for automated emergency responses, such as elevator grounding and HVAC shutdown, which are critical for occupant safety during a fire event. Furthermore, the forecast period suggests a move away from traditional water-based sprinklers in sensitive environments like data centers, in favor of clean agent suppression systems.
- The global market value is expected to exceed USD 150 billion by 2034, representing a robust investment landscape for technology providers.
- Clean agent fire suppression systems are witnessing the highest CAGR within the suppression category due to the growth of hyperscale data centers.
- The United States and China remain the most influential sovereign markets, together accounting for nearly 40 percent of global demand.
- Maintenance and managed services are becoming a recurring revenue goldmine as enterprises outsource fire safety audits and system health checks.
- The residential sector is poised for accelerated growth as smart home fire alarms become more affordable and accessible to the general public.
Fire Protection System Market Drivers Analysis
The primary catalysts for market expansion include the tightening of international building codes and the mandatory installation of advanced fire safety equipment in high-occupancy buildings. Additionally, the rise of the industrial internet of things (IIoT) has created a demand for specialized fire protection in automated warehouses and energy storage facilities.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global Adoption of Smart Building Technologies | +2.1% | Global / North America & Europe | 2025-2034 |
| Stringent Government Regulations & Safety Mandates | +1.8% | Asia-Pacific (India, China) | 2025-2030 |
| Rise in Data Center Construction | +1.5% | Global / MEA & North America | 2026-2034 |
Fire Protection System Market Restraints Analysis
High initial capital expenditure for the installation of advanced fire suppression and detection systems remains a significant barrier, particularly for small and medium-sized enterprises (SMEs). Furthermore, the lack of standardized regulatory frameworks across different developing nations complicates the operations of global fire safety equipment manufacturers.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Installation and Maintenance Costs | -1.2% | Global / Emerging Markets | 2025-2034 |
| Technical Complexity in Integrating Legacy Systems | -0.9% | Europe / North America | 2025-2029 |
Fire Protection System Market Opportunities Analysis
The retrofitting of aging commercial buildings with wireless fire detection systems presents a massive opportunity for growth. Additionally, the development of eco-friendly suppression agents that comply with the Kigali Amendment and other environmental protocols provides a competitive edge for innovative manufacturers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into the Residential Smart Home Market | +1.4% | Global / Western Europe | 2027-2034 |
| Development of Wireless & IoT-Enabled Detectors | +1.2% | Asia-Pacific / Southeast Asia | 2025-2032 |
Fire Protection System Market Challenges Impact Analysis
Ensuring the interoperability of fire protection systems with third-party building management software remains a technical hurdle. Moreover, the vulnerability of connected fire safety devices to cyber threats is a rising concern that necessitates the implementation of robust cybersecurity protocols within fire safety hardware.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity Risks in Connected Systems | -0.7% | North America / Europe | 2025-2034 |
| Inconsistency in Global Fire Safety Standards | -0.5% | Global / Latin America | 2025-2030 |
Fire Protection System Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the hardware, software, and services associated with fire safety. It covers the entire value chain from component manufacturing to system design, installation, and long-term maintenance across residential, commercial, and heavy industrial applications globally.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 82.5 Billion |
| Market Forecast in 2034 | USD 153.8 Billion |
| Growth Rate | 7.1% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Honeywell International Inc., Johnson Controls, Siemens AG, Carrier Global Corporation, Robert Bosch GmbH, Tyco (Johnson Controls), Halma plc, Hochiki Corporation, Minimax Viking Group, Gentex Corporation, Napco Security Technologies, Eaton Corporation, Securitas AB, United Technologies Corporation, Ansul (JCI). |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on product type, services, and diverse application verticals. Fire suppression remains a high-value segment due to the mechanical complexity and chemical engineering involved, while fire detection is the high-volume segment driven by widespread adoption across all building types. Services are increasingly becoming the focal point for market players as they seek to build long-term relationships with clients through inspection and compliance management.
- Fire Detection Systems: Includes multi-criteria detectors, aspiration smoke detectors (ASD), and heat detectors used for early-stage identification.
- Fire Suppression Systems: Encompasses automatic sprinkler systems, water mist systems, foam-based suppression, and clean agent gas systems (FM-200, Novec 1230).
- Fire Analysis and Software: Focuses on fire modeling, simulation software, and emergency communication systems.
- Managed Services: Covering annual maintenance contracts (AMC), cloud monitoring, and professional fire safety training.
- Vertical Applications: Segmented into commercial, industrial, residential, and transport infrastructure.
Regional Highlights
- North America: The largest market share holder, driven by the strict enforcement of NFPA codes and the massive presence of technology leaders. The U.S. remains the primary driver of high-end fire safety technology.
- Asia-Pacific: The fastest-growing region with a CAGR of over 8.5%. Rapid industrialization in China, India, and Vietnam, coupled with new government building safety mandates, is fueling demand.
- Europe: A mature market focused on energy-efficient fire safety and strict EN54 standards. Germany and the UK lead in high-precision detection system adoption.
- Middle East & Africa: Driven by massive infrastructure projects like NEOM and the expansion of the oil and gas sector which requires specialized industrial fire suppression.
- Latin America: Growth is steady, primarily led by Brazil and Mexico where industrial safety regulations are becoming more aligned with international standards.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Fire Protection System Market.- Honeywell International Inc.
- Johnson Controls
- Siemens AG
- Carrier Global Corporation
- Robert Bosch GmbH
- Halma plc
- Hochiki Corporation
- Minimax Viking Group
- Gentex Corporation
- Napco Security Technologies
- Eaton Corporation
- Securitas AB
- United Technologies Corporation
- Ansul (Johnson Controls)
- Potter Electric Signal Company
- Gielle Srl
- Nohmi Bosai Ltd.
- Fike Corporation
- Victaulic Co.
- Viking Group Inc.
Frequently Asked Questions
What is the projected market size of the Fire Protection System Market by 2034?
The market is projected to reach USD 153.8 Billion by 2034, growing at a steady CAGR of 7.1% from 2026 onwards.
Which region is expected to witness the highest growth in the fire safety sector?
The Asia-Pacific region is expected to witness the highest growth due to rapid urbanization, increasing industrial investments, and the implementation of stricter fire safety regulations in countries like China and India.
What are the primary drivers for the Fire Protection System Market?
Key drivers include the rise of smart building projects, mandatory safety regulations by governments, and the increasing need for specialized fire suppression in high-value environments like data centers and oil refineries.
How is IoT impacting the fire protection industry?
IoT is enabling smart, connected fire systems that offer real-time alerts, remote monitoring, and predictive maintenance, allowing building managers to address potential issues before they lead to system failure.
Why is there a shift toward clean agent fire suppression systems?
Clean agents are preferred in sensitive environments because they extinguish fires without leaving residue or damaging electronics, making them ideal for data centers, museums, and laboratories.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
