Industrial Refrigeration System Market
Industrial Refrigeration System Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_705284 | Published On : October 10, 2026 |
Format : 


 | Author : Jonathan Sikka
Industrial Refrigeration System Market Size
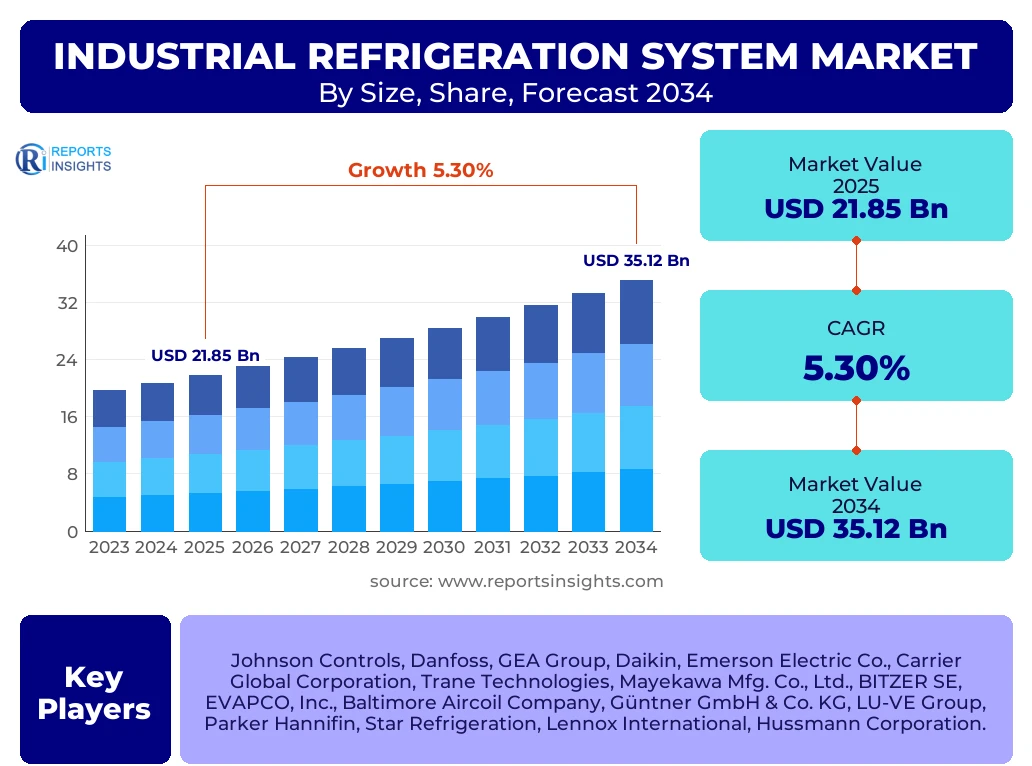
According to Reports Insights Consulting Pvt Ltd, The Industrial Refrigeration System Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.3% between 2025 and 2034. The market is estimated at USD 23.01 Billion in 2026 and is projected to reach USD 35.12 Billion by the end of the forecast period in 2034.
Key Industrial Refrigeration System Market Trends & Insights
The global industrial refrigeration landscape is undergoing a significant transformation driven by the transition toward natural refrigerants and the integration of digital monitoring technologies. Stakeholders are increasingly prioritizing energy-efficient solutions to comply with stringent environmental regulations, such as the Kigali Amendment and the EU F-gas Regulation. The shift from synthetic hydrofluorocarbons (HFCs) to natural alternatives like ammonia (NH3), carbon dioxide (CO2), and hydrocarbons is a dominant trend, particularly in developed economies. Furthermore, the rise of the cold chain logistics sector, fueled by the global expansion of the e-commerce grocery market and the pharmaceutical industry's need for temperature-controlled storage, is acting as a primary catalyst for market growth.
Competitive benchmarking reveals that leading players are focusing on modular and plug-and-play refrigeration units to reduce installation time and complexity. Regional insights indicate that the Asia-Pacific region is the primary engine of growth, supported by rapid industrialization and government initiatives to minimize post-harvest food losses. Meanwhile, North America and Europe are focusing on retrofitting existing systems with advanced controls and IoT-enabled predictive maintenance tools to optimize operational costs. The convergence of automation and refrigeration is creating a more resilient and transparent supply chain, allowing for real-time tracking of thermal conditions across various industrial applications.
- Largest Region: Asia-Pacific (APAC) remains the largest market due to its massive food processing industry and expanding cold storage infrastructure in China and India.
- Fastest-Growing Region: Asia-Pacific is also projected to be the fastest-growing region, driven by rising disposable incomes and changing dietary habits.
- Largest Segment by Share: The Food and Beverage application segment holds the largest market share, as it is the most intensive user of large-scale cooling systems.
- Refrigerant Trend: Ammonia (NH3) continues to be the leading refrigerant in terms of volume and efficiency for heavy-duty industrial applications.
Key Takeaways Industrial Refrigeration System Market Size & Forecast
The long-term outlook for the Industrial Refrigeration System market remains robust, with a clear trajectory toward sustainability and technological sophistication. Analysts emphasize that the market's expansion is not merely a result of increased demand for cooling but a fundamental shift in how industries manage thermal energy. The integration of high-stage and low-stage compressors, advanced condensers, and intelligent evaporators is enabling facilities to achieve higher Coefficients of Performance (COP). Forecasts suggest that the chemical and pharmaceutical sectors will provide significant tailwinds, as the production of specialty chemicals and biologics requires precise and reliable temperature control mechanisms that only industrial-grade systems can provide.
- Leading Country: China is the dominant player in terms of both production and consumption of industrial refrigeration components.
- Investment Focus: Heavy investments are being channeled into CO2-transcritical systems, which are gaining popularity in medium-to-large capacity applications.
- Regulatory Influence: Global phase-down schedules for high-GWP (Global Warming Potential) refrigerants are forcing a total overhaul of legacy systems.
- Technological Shift: The adoption of variable speed drives (VSDs) in compressors is becoming standard practice to enhance energy efficiency during part-load operations.
- Market Stability: The essential nature of refrigeration in food safety and healthcare ensures high market resilience even during periods of economic volatility.
Industrial Refrigeration System Market Drivers Analysis
The primary drivers for the industrial refrigeration market include the burgeoning global cold chain industry and the increasing demand for processed and frozen foods. As urbanization accelerates, the distance between food production sites and urban consumers increases, necessitating advanced refrigeration infrastructure. Additionally, the pharmaceutical industry’s reliance on cold-chain logistics for vaccines and sensitive biologics is a critical driver. The ongoing technological evolution in compressor design and heat exchanger efficiency is also encouraging end-users to upgrade their systems to reduce long-term electricity consumption and operational overhead.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Global Cold Chain Logistics | +1.8% | Global (High in India & SE Asia) | 2025 - 2034 |
| Adoption of Natural Refrigerants (NH3, CO2) | +1.5% | Europe and North America | 2025 - 2030 |
| Growth in Pharmaceutical Cold Storage | +1.2% | Global (High in USA & Germany) | 2025 - 2034 |
Industrial Refrigeration System Market Restraints Analysis
The high initial capital investment required for setting up industrial-scale refrigeration plants remains a significant barrier, particularly for small and medium-sized enterprises (SMEs) in developing regions. Furthermore, the complexity of maintaining systems that use natural refrigerants like ammonia, which is toxic and flammable, necessitates highly skilled labor and strict adherence to safety protocols. Regulatory uncertainties in some regions regarding the specific timelines for refrigerant phase-outs can also lead to delayed investment decisions by industrial operators who are hesitant to commit to a specific technology path.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Capital and Installation Costs | -0.9% | Developing Economies (Africa, SE Asia) | 2025 - 2034 |
| Shortage of Skilled Technical Workforce | -0.6% | North America and Europe | 2025 - 2029 |
Industrial Refrigeration System Market Opportunities Analysis
Emerging opportunities in the market are centered around the development of "Smart Refrigeration" solutions powered by Artificial Intelligence (AI) and Machine Learning (ML). These systems can predict equipment failure and optimize defrost cycles, leading to massive energy savings. Additionally, the rising trend of district cooling and the integration of heat pumps with refrigeration systems (waste heat recovery) present lucrative avenues for growth. Manufacturers who can offer integrated, low-GWP solutions that combine heating and cooling functions are expected to capture a larger share of the industrial market in the coming decade.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| IoT-Enabled Predictive Maintenance | +1.4% | Global | 2026 - 2034 |
| Waste Heat Recovery Systems | +1.1% | Europe (Nordic Countries) | 2025 - 2034 |
Industrial Refrigeration System Market Challenges Impact Analysis
One of the most pressing challenges is the strict environmental compliance landscape, which varies significantly from one jurisdiction to another, complicating global product standardization. Additionally, the industrial refrigeration sector faces challenges related to energy price volatility, as these systems are highly energy-intensive. Balancing the need for high cooling capacity with the goal of reducing carbon footprints requires constant innovation. Furthermore, the threat of cyber-attacks on industrial control systems (ICS) is an emerging challenge as refrigeration plants become more interconnected and reliant on cloud-based management software.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Global Environmental Regulations | -0.5% | EU and North America | 2025 - 2030 |
| Cybersecurity Risks in Connected Systems | -0.3% | Developed Markets | 2027 - 2034 |
Industrial Refrigeration System Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the components, refrigerants, and applications that define the industrial refrigeration sector. It provides a granular breakdown of the market dynamics across six major geographical regions, highlighting the unique regulatory and economic factors influencing each territory. The research methodology combines primary interviews with industry veterans and secondary data analysis from trade associations and financial reports to ensure high accuracy. The report aims to provide a comprehensive roadmap for stakeholders to identify high-growth segments and navigate the evolving technological landscape over the next nine years.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 21.85 Billion |
| Market Forecast in 2034 | USD 35.12 Billion |
| Growth Rate | 5.3% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Johnson Controls, Danfoss, GEA Group, Daikin, Emerson Electric Co., Carrier Global Corporation, Trane Technologies, Mayekawa Mfg. Co., Ltd., BITZER SE, EVAPCO, Inc., Baltimore Aircoil Company, Güntner GmbH & Co. KG, LU-VE Group, Parker Hannifin, Star Refrigeration, Lennox International, Hussmann Corporation. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The industrial refrigeration market is categorized primarily by component, refrigerant type, and end-user application. The compressor segment is the most significant within components, as it represents the "heart" of the system and accounts for a substantial portion of the total system cost and energy consumption. Within refrigerants, the ammonia segment dominates large-scale industrial plants due to its superior thermodynamic properties and zero global warming potential. However, the CO2 segment is experiencing rapid growth in the "subcritical" and "transcritical" categories, especially for applications where ammonia's toxicity is a concern. The food and beverage sector remains the largest application segment, encompassing meat and poultry processing, dairy production, and beverage carbonation and cooling.
- By Component:
- Compressors (Reciprocating, Screw, Centrifugal)
- Condensers (Evaporative, Air-cooled, Water-cooled)
- Evaporators
- Controls and Monitoring Systems
- Other (Vessels, Pumps, Valves)
- By Refrigerant Type:
- Ammonia (NH3)
- Carbon Dioxide (CO2)
- Hydrofluorocarbons (HFCs)
- Hydrofluoroolefins (HFOs)
- Others (Hydrocarbons, Water)
- By Application:
- Food and Beverage (Meat, Poultry, Dairy, Beverages, Fruits, Vegetables)
- Chemical and Petrochemical Processing
- Pharmaceutical and Life Sciences
- Oil and Gas (Liquefaction, Refining)
- Power Generation
- Others
Regional Highlights
The Asia-Pacific region is currently the epicenter of the industrial refrigeration market, accounting for over 35% of the total market share. This dominance is attributed to the massive population base and the rapid development of the middle class in China, India, and Southeast Asian nations. These demographic shifts are driving demand for high-quality frozen foods and temperature-sensitive pharmaceutical products. Furthermore, governments in this region are providing subsidies for the construction of modern cold storage warehouses to reduce post-harvest waste and improve food security.
North America and Europe follow closely, with their market dynamics defined by replacement demand and strict environmental regulations. In Europe, the F-gas regulation is a major catalyst, forcing companies to move away from HFCs toward natural refrigerants. This has made Europe a leader in the adoption of CO2-based systems. In North America, the modernization of aging food processing facilities and the expansion of logistics hubs in the United States and Canada are supporting market growth. The Middle East and Africa are also showing potential, particularly in the oil and gas and desalination sectors, where industrial cooling is vital for operational processes.
- Asia-Pacific: Largest market share and highest growth rate due to rapid industrialization and food chain expansion.
- North America: Significant market for advanced control systems and energy-efficient retrofitting solutions.
- Europe: Leading the transition toward CO2 and ammonia systems due to stringent environmental laws.
- Middle East: Demand driven by extreme ambient temperatures and intensive oil and gas processing requirements.
- Latin America: Growing export-oriented agricultural sector driving the need for sophisticated cooling plants.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Industrial Refrigeration System Market.- Johnson Controls International plc
- Danfoss A/S
- GEA Group Aktiengesellschaft
- Daikin Industries, Ltd.
- Emerson Electric Co.
- Carrier Global Corporation
- Trane Technologies plc
- Mayekawa Mfg. Co., Ltd.
- BITZER SE
- EVAPCO, Inc.
- Baltimore Aircoil Company
- Güntner GmbH & Co. KG
- LU-VE Group
- Parker Hannifin Corporation
- Star Refrigeration Ltd
- Lennox International Inc.
- Hussmann Corporation
- Ingersoll Rand Inc.
- Alfa Laval AB
- Rivacold srl
Frequently Asked Questions
What is the current market size of the Industrial Refrigeration System Market?
The market is estimated at USD 21.85 Billion in 2025 and is projected to reach USD 35.12 Billion by 2034, growing at a CAGR of 5.3%.
Which refrigerant type is expected to dominate the market?
Ammonia remains the dominant refrigerant for large-scale industrial applications due to its high efficiency and zero GWP, though CO2 is gaining rapid market share in medium-capacity systems.
How is the IoT impacting the industrial refrigeration sector?
IoT enables real-time monitoring and predictive maintenance, allowing operators to detect inefficiencies or potential failures before they occur, thus reducing downtime and energy costs.
What are the primary growth drivers for the APAC region?
Growth in APAC is driven by the expansion of the cold chain infrastructure, government support for food safety, and the rising demand for processed food products in China and India.
What are the main challenges facing industrial refrigeration manufacturers?
Manufacturers face challenges such as complying with diverse global environmental regulations, managing the high costs of raw materials, and addressing the shortage of skilled technicians for natural refrigerant systems.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
