Film Adhesive Market
Film Adhesive Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711498 | Published On : November 04, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Film Adhesive Market Size
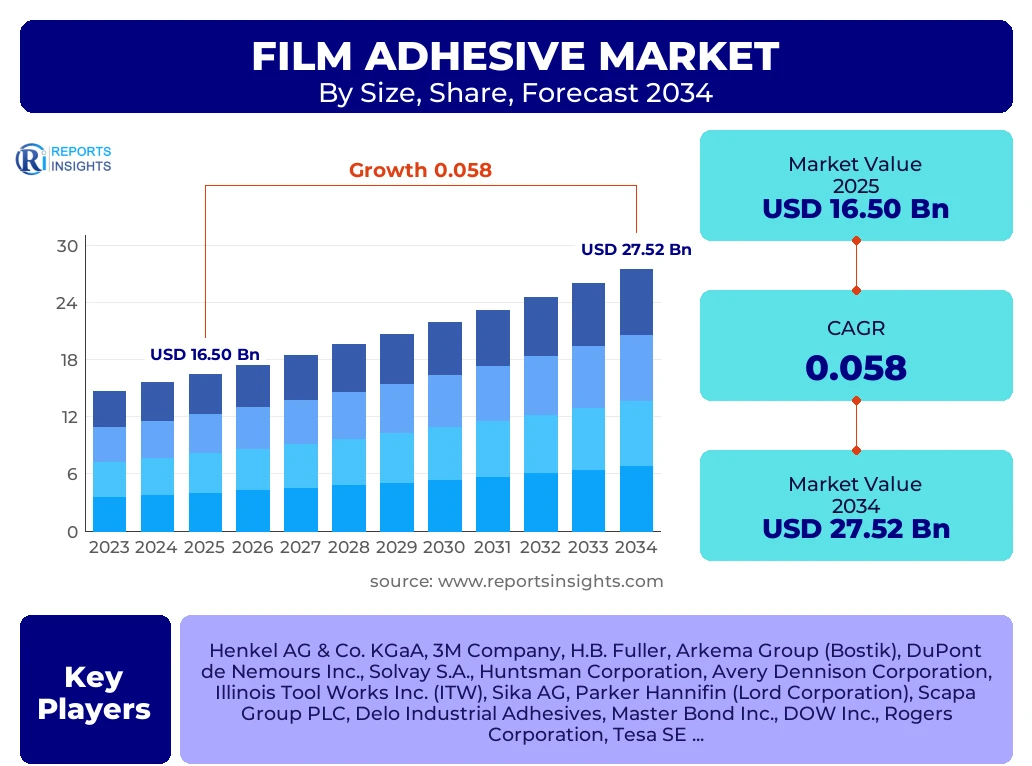
According to Reports Insights Consulting Pvt Ltd, The Film Adhesive Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.8% between 2025 and 2034. The market is estimated at USD 17.46 Billion in 2026 and is projected to reach USD 27.52 Billion by the end of the forecast period in 2034.
Key Film Adhesive Market Trends & Insights
The global film adhesive landscape is undergoing a significant transformation driven by the escalating demand for lightweight, high-performance bonding solutions across capital-intensive industries such as aerospace, automotive, and microelectronics. As manufacturers transition away from traditional mechanical fastening methods like riveting and welding to reduce structural weight and improve stress distribution, film adhesives have emerged as a critical enabling technology. These materials offer superior uniformity in bond line thickness, minimal waste, and enhanced fatigue resistance, which are vital for modern composite assembly. The integration of multi-functional adhesive films, which provide both structural integrity and thermal or electrical conductivity, is currently a dominant trend shaping the competitive environment.
- Asia Pacific is the largest and fastest-growing region, driven by massive electronics manufacturing hubs and expanding aerospace sectors in China and India.
- The Epoxy resin segment remains the largest in terms of market share due to its exceptional mechanical strength and chemical resistance in structural applications.
- Aerospace and Defense represent the largest end-use segment, where film adhesives are indispensable for bonding honeycomb structures and composite skins.
- There is a notable shift toward bio-based and solvent-free adhesive films as global environmental regulations regarding Volatile Organic Compounds (VOCs) become more stringent.
- The rise of Electric Vehicle (EV) production is catalyzing demand for specialized adhesive films for battery pack assembly and thermal management systems.
Key Takeaways Film Adhesive Market Size & Forecast
The forecast period from 2025 to 2034 indicates a robust growth trajectory fueled by technological convergence and material science innovations. Market participants are increasingly focusing on the development of low-temperature cure films to reduce energy consumption and cycle times in manufacturing. Furthermore, the expansion of the 5G infrastructure and the miniaturization of consumer electronics are creating niche high-value opportunities for ultra-thin adhesive films that can withstand high thermal loads without compromising dielectric properties.
- China continues to lead as the primary consumer and producer of film adhesives, underpinned by its dominance in global consumer electronics and rapid advancement in domestic aircraft manufacturing.
- The shift from liquid adhesives to film formats is accelerating in high-precision industries to ensure process repeatability and eliminate the risks associated with manual application.
- High-temperature resistant films, specifically those based on polyimide chemistries, are seeing heightened demand in the semiconductor and aerospace engine component sectors.
- Strategic collaborations between adhesive formulators and composite material manufacturers are becoming essential to develop integrated bonding solutions for next-generation airframes.
- The European market is witnessing a surge in demand for recyclable and repairable adhesive systems, aligned with the region's circular economy objectives.
Film Adhesive Market Drivers Analysis
The market expansion is primarily propelled by the fundamental shift toward lightweighting in the transportation sector and the increasing complexity of electronic assemblies. As industries prioritize fuel efficiency and carbon footprint reduction, the adoption of advanced composites and dissimilar material bonding—where film adhesives excel—becomes a strategic necessity. Furthermore, the precision offered by film adhesives in automated assembly lines significantly enhances throughput and reduces total cost of ownership for large-scale manufacturers.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Demand for Lightweight Aerospace Components | +1.8% | Global (North America, Europe) | 2025 - 2034 |
| Miniaturization of Semiconductor and Electronic Devices | +1.5% | Asia Pacific (Taiwan, South Korea, China) | 2025 - 2030 |
| Expansion of Electric Vehicle (EV) Infrastructure | +1.2% | Global (Germany, USA, China) | 2026 - 2034 |
| Advancements in Automated Dispensing and Placement Technologies | +0.8% | North America, Europe | 2025 - 2029 |
Film Adhesive Market Restraints Analysis
Despite the positive growth outlook, the market faces significant hurdles related to the high initial cost of materials and the technical complexities associated with storage and handling. Many high-performance film adhesives require cold-chain logistics and have limited shelf lives, which complicates inventory management for smaller manufacturers and increases operational overheads.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Storage and Cold-Chain Requirements | -0.9% | Global | 2025 - 2034 |
| High Production and Material Costs vs. Liquid Alternatives | -0.7% | Emerging Markets (India, SE Asia) | 2025 - 2030 |
| Environmental Regulations on Synthetic Resin Components | -0.5% | Europe (REACH Compliance) | 2025 - 2034 |
Film Adhesive Market Opportunities Analysis
The emergence of 5G technology and the next generation of telecommunications hardware present a fertile ground for market growth. These applications require adhesive films with specific dielectric constants and high thermal conductivity to manage heat dissipation in compact enclosures. Additionally, the medical device sector is increasingly utilizing medical-grade adhesive films for wearable biosensors and advanced wound care, representing a high-margin growth vertical.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of 5G and IoT Infrastructure | +1.4% | Global (USA, Japan, South Korea) | 2026 - 2032 |
| Medical-Grade Films for Wearable Health Devices | +1.1% | North America, Europe | 2025 - 2034 |
| Recyclable Adhesive Chemistries for Circular Economy | +0.9% | Europe | 2027 - 2034 |
Film Adhesive Market Challenges Impact Analysis
Supply chain volatility concerning specialty chemicals and raw resins remains a persistent challenge for manufacturers. The geopolitical landscape often affects the pricing of key precursors for epoxy and polyimide resins, leading to narrowed profit margins. Furthermore, the technical challenge of ensuring consistent bond quality across varying substrates in high-speed automated lines requires continuous R&D investment.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Volatility (Petrochemical Derivatives) | -1.0% | Global | 2025 - 2034 |
| Complex Certification Processes in Aerospace and Medical | -0.6% | USA, EU | 2025 - 2034 |
Film Adhesive Market - Updated Report Scope
This report provides a granular analysis of the global film adhesive market, encompassing technological advancements, competitive dynamics, and regulatory influences. It evaluates the shift from traditional bonding to film-based systems, providing stakeholders with actionable insights into high-growth segments and regional investment pockets. The scope covers various resin types, carrier materials, and diverse end-use industries, ensuring a holistic view of the value chain.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 16.50 Billion |
| Market Forecast in 2034 | USD 27.52 Billion |
| Growth Rate | 5.8% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Henkel AG & Co. KGaA, 3M Company, H.B. Fuller, Arkema Group (Bostik), DuPont de Nemours Inc., Solvay S.A., Huntsman Corporation, Avery Dennison Corporation, Illinois Tool Works Inc. (ITW), Sika AG, Parker Hannifin (Lord Corporation), Scapa Group PLC, Delo Industrial Adhesives, Master Bond Inc., DOW Inc., Rogers Corporation, Tesa SE, Nitto Denko Corporation. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The film adhesive market is segmented primarily by resin chemistry and end-use application, with each segment exhibiting distinct growth drivers. Epoxy resins dominate the structural applications due to their superior load-bearing capabilities, while acrylics are preferred in the electronics sector for their fast-curing properties and excellent adhesion to plastics. The transition toward thermoplastic films is a key sub-segmental trend, as these materials offer the advantage of being re-processable and having faster cycle times compared to thermoset alternatives.
- Resin Type Analysis: Epoxy remains the gold standard for aerospace, while Polyimides are gaining ground in high-heat electronic environments.
- End-Use Industry: Aerospace and Defense lead the market value, followed closely by the Electrical and Electronics sector due to the proliferation of smart devices.
- Technology: Thermosetting films currently hold the majority share, but Thermoplastic films are projected to grow at a faster rate due to recyclability trends.
- Application Type: Structural bonding is the primary application, though functional bonding (EMI shielding, thermal interface) is the fastest-growing sub-segment.
Regional Highlights
- Asia Pacific: Holds the largest market share and is the fastest-growing region. This is attributed to the concentration of electronics manufacturing in China, Taiwan, and South Korea, coupled with massive automotive production.
- North America: A major hub for innovation in aerospace film adhesives. The presence of aerospace giants and a robust defense sector ensures steady demand for high-performance structural films.
- Europe: Driven by the automotive industry's move toward electric vehicles and stringent environmental regulations favoring sustainable adhesive formulations. Germany and France are key contributors.
- Latin America & MEA: These regions are emerging markets with growth centered around infrastructure development and the gradual expansion of localized automotive assembly plants.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Film Adhesive Market.- Henkel AG & Co. KGaA
- 3M Company
- H.B. Fuller Company
- Arkema Group (Bostik)
- DuPont de Nemours, Inc.
- Solvay S.A.
- Huntsman Corporation
- Avery Dennison Corporation
- Illinois Tool Works Inc. (ITW)
- Sika AG
- Parker Hannifin (Lord Corporation)
- Scapa Group PLC
- Delo Industrial Adhesives
- Master Bond Inc.
- DOW Inc.
- Rogers Corporation
- Tesa SE
- Nitto Denko Corporation
- 3M Aerospace
- Hexcel Corporation
Frequently Asked Questions
What is the current market size of the global Film Adhesive industry?
The global film adhesive market is estimated to be valued at USD 16.50 Billion in 2025 and is expected to reach USD 27.52 Billion by 2034, growing at a CAGR of 5.8%.
Which end-use industry is the primary driver for film adhesive demand?
The Aerospace and Defense industry is the primary driver, utilizing film adhesives for critical structural bonding in aircraft wings, fuselages, and honeycomb panels where weight reduction and high strength are paramount.
Why are film adhesives preferred over liquid adhesives in high-tech manufacturing?
Film adhesives are preferred because they provide a uniform bond line thickness, eliminate waste from over-application, offer cleaner processing, and are better suited for automated assembly lines.
Which region offers the most significant growth opportunities?
Asia Pacific offers the most significant growth opportunities due to the rapid expansion of the consumer electronics sector, increased automotive production, and rising aerospace investments in China and India.
What are the main challenges facing the Film Adhesive market?
Key challenges include high material costs compared to traditional adhesives, the need for specialized cold-chain storage for thermosetting films, and raw material price volatility linked to petrochemical precursors.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
