Fiber Cement Market
Fiber Cement Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711618 | Published On : November 08, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Fiber Cement Market Size
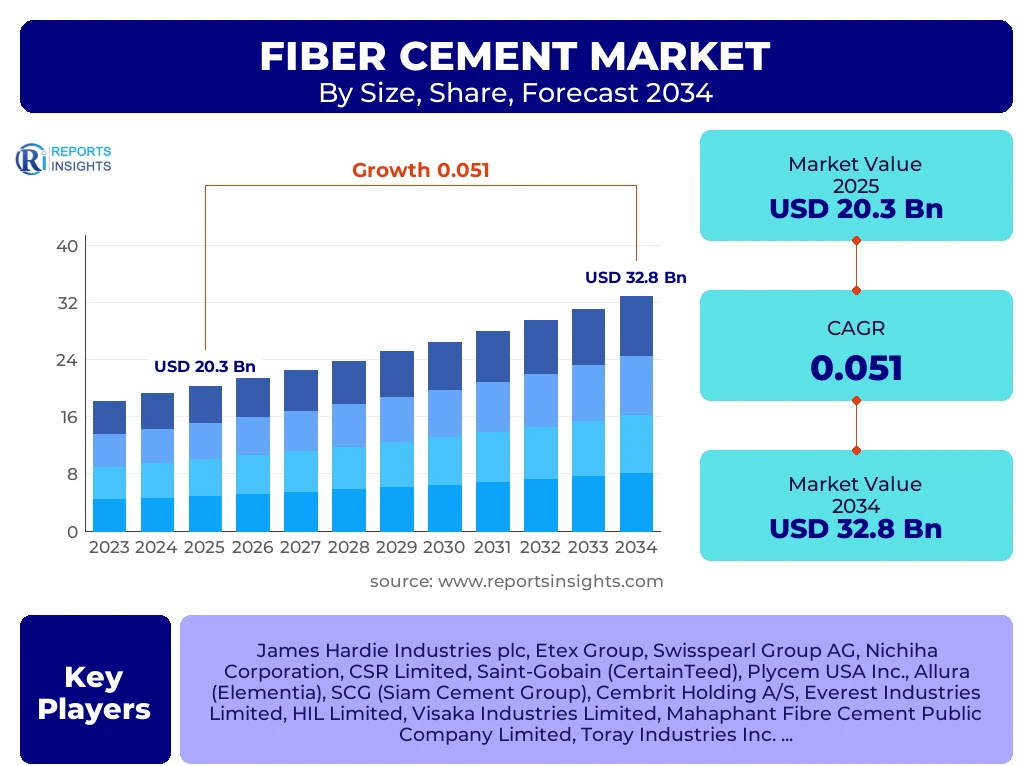
According to Reports Insights Consulting Pvt Ltd, The Fiber Cement Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.1% between 2025 and 2034. The market is estimated at USD 21.4 Billion in 2026 and is projected to reach USD 32.8 Billion by the end of the forecast period in 2034.
Key Fiber Cement Market Trends & Insights
The global fiber cement industry is undergoing a significant transformation driven by the escalating demand for sustainable, fire-resistant, and aesthetically versatile building materials. As urbanization intensifies across the Asia-Pacific region and renovation activities surge in North America and Europe, fiber cement has emerged as a preferred alternative to traditional wood, vinyl, and masonry products. Modern manufacturing techniques are now enabling the production of fiber cement boards that replicate the texture of natural timber or stone while offering superior durability and minimal maintenance. Furthermore, the integration of advanced coating technologies and autoclaved curing processes has enhanced the material's resistance to moisture, rot, and pest infestation, positioning it as a cornerstone of resilient infrastructure development. Competitive benchmarking indicates that leading players are increasingly focusing on low-carbon formulations to align with global net-zero construction targets, thereby securing a competitive edge in environmentally conscious markets.
- Asia-Pacific is the fastest-growing regional market due to rapid infrastructure development and high residential construction rates in China, India, and Southeast Asia.
- North America remains the largest regional market by value, primarily driven by the replacement of aging vinyl siding and the widespread adoption of fiber cement in new residential developments.
- The Siding and Cladding segment constitutes the largest market share, as homeowners and commercial developers prioritize long-lasting exterior protection.
- Portland Cement remains the dominant raw material segment, though the use of recycled cellulosic fibers is gaining momentum in sustainable product lines.
- Increasing investment in non-residential construction, specifically in the healthcare and education sectors, is creating new revenue streams for high-performance fiber cement panels.
Key Takeaways Fiber Cement Market Size & Forecast
The strategic outlook for the fiber cement market remains bullish, supported by a fundamental shift toward durable building envelopes and stringent fire safety regulations across the globe. Users and stakeholders are increasingly inquiring about the cost-benefit analysis of fiber cement versus traditional materials, the impact of raw material price volatility, and the role of innovation in surface finishes. Our analysis suggests that while the initial installation cost may be higher than vinyl, the lifecycle value and reduced maintenance requirements provide a compelling economic narrative for end-users. The transition from asbestos-based products to non-asbestos fiber cement in developing economies also represents a significant growth vector, as public health regulations become more aligned with international standards.
- The United States leads the market in terms of technology adoption and high-end residential applications.
- Market growth is heavily influenced by the remodeling and renovation sector, which accounts for nearly half of the demand in mature economies.
- Environmentally friendly product certifications (LEED, BREEAM) are becoming essential for market entry in the European Union.
- Innovation in digital printing on fiber cement surfaces is allowing for customized architectural designs, expanding the material's use in high-end commercial projects.
- The residential segment is expected to maintain its dominance throughout the forecast period, fueled by the global housing shortage and urbanization.
Fiber Cement Market Drivers Analysis
The primary growth engine for the fiber cement market is the increasing global focus on resilient building materials that can withstand extreme weather events and mitigate fire risks. As building codes become more rigorous, particularly in wildfire-prone regions and densely populated urban centers, the non-combustible nature of fiber cement provides a significant advantage over wood and synthetic alternatives. Additionally, the ongoing urbanization in emerging economies necessitates materials that offer a balance of cost-efficiency, durability, and aesthetic appeal. The aesthetic versatility of modern fiber cement, which can mimic wood grain, smooth stucco, or rugged stone, allows it to cater to diverse architectural styles while maintaining the structural integrity required for modern construction.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Growing Demand for Fire-Resistant Materials | +1.4% | North America and Australia | 2025 - 2034 |
| Rapid Urbanization in Emerging Economies | +1.2% | India, China, and Vietnam | 2026 - 2034 |
| Expansion of Renovation and Remodeling Sector | +0.9% | Western Europe and USA | 2025 - 2030 |
| Ban on Asbestos-Based Construction Products | +0.7% | Southeast Asia and Latin America | 2025 - 2034 |
Fiber Cement Market Restraints Analysis
Despite its numerous advantages, the fiber cement market faces hurdles related to high installation costs and labor intensity. The material is significantly heavier than vinyl or wood, requiring specialized handling, cutting tools, and a larger workforce for installation, which can deter budget-conscious developers. Furthermore, the volatility in the prices of raw materials such as Portland cement and silica sand can impact the profit margins of manufacturers. Environmental concerns regarding the carbon footprint of cement production also pose a long-term restraint, as regulatory bodies move toward stricter carbon emission standards for building material manufacturers.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Installation and Labor Costs | -0.6% | Global | 2025 - 2034 |
| Raw Material Price Volatility | -0.4% | Global | 2025 - 2030 |
| Environmental Regulations on Cement Production | -0.3% | European Union | 2027 - 2034 |
Fiber Cement Market Opportunities Analysis
The shift toward green building practices presents a lucrative opportunity for fiber cement manufacturers to develop carbon-neutral or carbon-negative product lines. By incorporating industrial by-products like fly ash or using alternative binders, companies can reduce the environmental impact of their products. Additionally, the expansion of modular and prefabricated construction offers a unique opportunity for fiber cement panels, which are well-suited for off-site manufacturing due to their durability and ease of transport once formed. The development of self-cleaning and photocatalytic coatings also represents a high-growth niche, particularly for commercial buildings in polluted urban environments.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of Green Building Standards | +1.1% | Europe and North America | 2026 - 2034 |
| Growth in Prefabricated/Modular Construction | +0.8% | Japan and Nordic Countries | 2025 - 2034 |
| Development of Advanced Surface Coatings | +0.5% | Global | 2028 - 2034 |
Fiber Cement Market Challenges Impact Analysis
One of the most persistent challenges in the fiber cement market is the shortage of skilled labor capable of properly installing these materials. Improper installation can lead to moisture infiltration and cracking, which negatively impacts the brand reputation of manufacturers. Additionally, the logistics of transporting heavy and brittle fiber cement boards over long distances can lead to high breakage rates and increased carbon emissions. Competition from emerging alternative materials, such as engineered wood and advanced composites that offer similar durability with lower weight, also necessitates constant innovation from fiber cement producers.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shortage of Skilled Installation Labor | -0.5% | North America and Western Europe | 2025 - 2034 |
| Logistics and Transportation Fragility | -0.3% | Large Geographic Markets (e.g., USA, Australia) | 2025 - 2034 |
| Competition from New Composite Materials | -0.4% | Global | 2026 - 2034 |
Fiber Cement Market - Updated Report Scope
This report provides a comprehensive analysis of the global fiber cement market, covering various product types, applications, and end-use sectors across all major geographic regions. The scope includes a detailed evaluation of raw material trends, manufacturing process innovations, and the competitive landscape of the top industry participants. By examining both historical data and future growth projections, the report offers a strategic roadmap for stakeholders to identify high-potential segments and navigate the evolving regulatory environment.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 20.3 Billion |
| Market Forecast in 2034 | USD 32.8 Billion |
| Growth Rate | 5.1% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | James Hardie Industries plc, Etex Group, Swisspearl Group AG, Nichiha Corporation, CSR Limited, Saint-Gobain (CertainTeed), Plycem USA Inc., Allura (Elementia), SCG (Siam Cement Group), Cembrit Holding A/S, Everest Industries Limited, HIL Limited, Visaka Industries Limited, Mahaphant Fibre Cement Public Company Limited, Toray Industries Inc., Equitone, American Fiber Cement Corporation, GAF, Woodville Co. Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The fiber cement market is segmented based on raw materials, applications, and end-use sectors to provide a granular view of market dynamics. The siding application segment currently dominates the market due to its wide adoption in residential exteriors, where it offers a blend of durability and aesthetic variety. In terms of end-use, the residential sector holds the majority share, though the non-residential segment is witnessing rapid growth driven by the demand for low-maintenance and fire-resistant cladding in commercial and institutional buildings. The raw material segment is led by Portland cement, while the inclusion of performance-enhancing additives like silica and various synthetic or natural fibers is becoming increasingly common to tailor products for specific climatic conditions.
- By Raw Material:
- Portland Cement (Dominant segment due to structural properties)
- Silica (Essential for stability and moisture resistance)
- Cellulosic Fiber (Provides reinforcement and flexibility)
- Other Additives (Colorants, chemicals, and fillers)
- By Application:
- Siding (Largest segment, widely used for home exteriors)
- Roofing (Popular in regions requiring high weather resistance)
- Flooring (Used as tile underlayment and sub-flooring)
- Molding & Trim (Growing use in finishing applications)
- Other Applications (Backer boards, fire protection panels)
- By End-Use:
- Residential (Major driver, includes new builds and renovations)
- Non-residential (Commercial, healthcare, education, and industrial)
Regional Highlights
- North America: The largest market globally, characterized by a strong preference for fiber cement siding in residential construction and a robust renovation culture. The United States is the primary contributor to this region's revenue.
- Asia-Pacific: The fastest-growing region, fueled by massive urbanization, infrastructure projects, and a shift away from traditional building materials in China, India, and Southeast Asia.
- Europe: Focuses on high-performance cladding and sustainable building solutions. Strict fire safety regulations and the European Green Deal are key market drivers here.
- Latin America: Experiencing steady growth as fiber cement replaces traditional masonry and wood in low-to-middle income housing projects.
- Middle East & Africa: Demand is driven by large-scale infrastructure projects and the need for heat-resistant materials in arid climates.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Fiber Cement Market.- James Hardie Industries plc
- Etex Group
- Swisspearl Group AG
- Nichiha Corporation
- CSR Limited
- Saint-Gobain (CertainTeed)
- Plycem USA Inc.
- Allura (Elementia)
- SCG (Siam Cement Group)
- Cembrit Holding A/S
- Everest Industries Limited
- HIL Limited
- Visaka Industries Limited
- Mahaphant Fibre Cement Public Company Limited
- Toray Industries Inc.
- Equitone
- American Fiber Cement Corporation
- GAF
- Woodville Co. Ltd.
- Acon Holding JSC
Frequently Asked Questions
What is fiber cement and why is it preferred in construction?
Fiber cement is a composite building material made from cement, sand, and cellulose fibers. It is preferred due to its extreme durability, resistance to fire, rot, and termites, and its ability to mimic the appearance of wood, stone, or brick with significantly lower maintenance requirements.
What is the projected growth rate of the Fiber Cement Market through 2034?
The market is expected to grow at a Compound Annual Growth Rate (CAGR) of 5.1% from 2025 to 2034, driven by urbanization and the demand for fire-safe building envelopes.
Which region currently leads the global Fiber Cement Market?
North America is currently the largest market in terms of value, primarily due to the extensive use of fiber cement siding in residential construction and a large volume of home remodeling projects.
How does fiber cement compare to vinyl siding in terms of cost and value?
While fiber cement typically has a higher initial cost for both the material and installation compared to vinyl, it offers superior long-term value through increased durability, better fire resistance, and a higher return on investment for property resale.
Is fiber cement considered an environmentally friendly building material?
Yes, fiber cement is considered more sustainable than many alternatives because it is long-lasting, reducing the need for replacement. Many manufacturers are also now using recycled content and low-carbon production methods to enhance its eco-friendly profile.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
