Ev Electronics Testing Inspection Certification Tic Market
Ev Electronics Testing Inspection Certification Tic Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711049 | Published On : October 02, 2026 |
Format : 


 | Author : Ashraf Shehata
Ev Electronics Testing Inspection Certification Tic Market Size
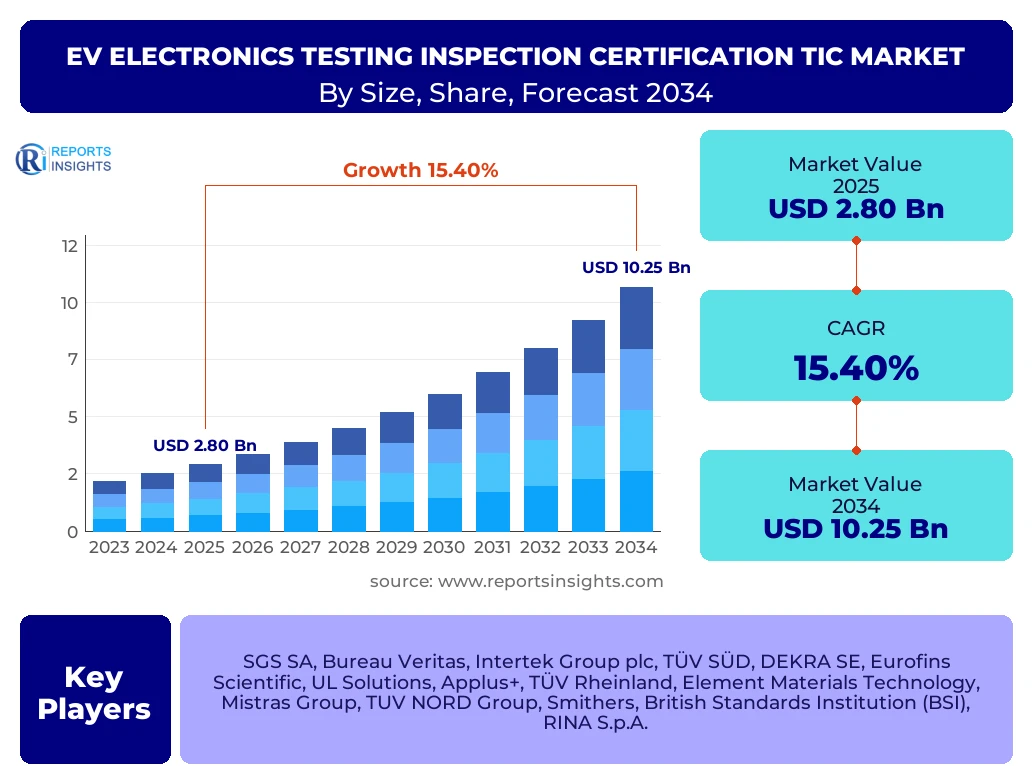
According to Reports Insights Consulting Pvt Ltd, The Ev Electronics Testing Inspection Certification Tic Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 15.4% between 2026 and 2034. The market is estimated at USD 3.23 Billion in 2026 and is projected to reach USD 10.25 Billion by the end of the forecast period in 2034.
Key Ev Electronics Testing Inspection Certification Tic Market Trends & Insights
The global EV electronics TIC market is undergoing a radical transformation driven by the rapid electrification of the automotive sector and the increasing complexity of vehicle architectures. As internal combustion engines are replaced by sophisticated electric powertrains, the demand for rigorous testing, inspection, and certification (TIC) services has surged. Stakeholders are increasingly focused on battery safety, electromagnetic compatibility (EMC), and cybersecurity, which have become the three pillars of modern automotive compliance. Regional insights suggest a significant shift in manufacturing hubs, with the Asia-Pacific region maintaining its dominance while North America experiences the fastest growth due to aggressive localized supply chain initiatives and government incentives. Competitive benchmarking reveals that leading TIC firms are shifting from traditional laboratory testing to integrated software-based simulation and digital twin validation to keep pace with the shortened product development cycles of EV manufacturers.
- Largest Region: Asia-Pacific remains the largest market, accounting for over 45% of the global share, driven by massive EV production volumes in China and Japan.
- Fastest Growing Region: North America is projected to be the fastest-growing region with a CAGR of 17.2% due to the expansion of domestic battery gigafactories and stringent safety mandates.
- Largest Segment by Service: Testing services currently hold the largest market share as OEMs require extensive laboratory validation for new electronic components.
- Largest Segment by Application: The Battery and Powertrain segment dominates the market, representing the most critical area for safety and performance certification.
- Digital Transformation: Remote inspection and AI-driven automated testing are emerging as significant trends to reduce time-to-market for Tier 1 and Tier 2 suppliers.
Key Takeaways Ev Electronics Testing Inspection Certification Tic Market Size & Forecast
The EV electronics TIC market is positioned for exponential growth as global regulatory bodies harmonize safety standards for high-voltage systems and autonomous driving technologies. Analysts observe that the market is moving toward a service-oriented model where certification is not just a regulatory hurdle but a competitive advantage for OEMs seeking to build consumer trust in battery reliability and vehicle range. The integration of Vehicle-to-Everything (V2X) communication is further expanding the scope of TIC services to include network security and interoperability testing. The transition toward Software-Defined Vehicles (SDVs) ensures that the TIC market will remain resilient, with ongoing software updates requiring continuous certification throughout the vehicle's lifecycle.
- China Dominance: China leads the global market in both consumption and production of TIC services for EV electronics, supported by a mature infrastructure and standardized national protocols.
- Battery Safety Focus: Certification against standards such as UN ECE R100 and ISO 6469-3 is the primary revenue driver for TIC providers.
- Cybersecurity Emergence: The implementation of ISO/SAE 21434 has created a new high-value vertical for TIC companies focusing on automotive electronics.
- Infrastructure Expansion: Charging station certification is becoming a significant secondary market, focusing on safety, interoperability, and billing accuracy.
- Tier 1 Compliance: Increased pressure on component suppliers to provide pre-certified modules is accelerating the growth of the testing segment.
Ev Electronics Testing Inspection Certification Tic Market Drivers Analysis
The expansion of the EV electronics TIC market is primarily fueled by the escalation of safety regulations and the global push for decarbonization. Governments worldwide are implementing stringent mandates for vehicle safety, particularly concerning lithium-ion battery stability and high-voltage electrical systems. Furthermore, the rising complexity of semi-autonomous and fully autonomous features necessitates extensive electronic validation to prevent system failures. The proliferation of electronic control units (ECUs) in modern EVs ensures a constant demand for EMC testing to prevent signal interference.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period | |
|---|---|---|---|---|
| Stringent Government Safety Mandates | +4.2% | European Union & United States | 2025 - 2034 | High-voltage safety and battery crash-test standards drive continuous demand. |
| Technological Advancements in ADAS | +3.8% | Global | 2026 - 2032 | Complexity in sensor fusion requires rigorous electronic certification. |
| Proliferation of Connected Vehicles | +3.1% | North America & APAC | 2025 - 2030 | V2X communication testing becomes a critical requirement. |
Ev Electronics Testing Inspection Certification Tic Market Restraints Analysis
Despite the positive growth trajectory, the EV electronics TIC market faces challenges such as the high cost of specialized testing equipment and the lack of global standardization. The rapid evolution of battery chemistries, such as the shift toward solid-state batteries, often outpaces the development of testing protocols, leading to delays in certification. Additionally, the high capital expenditure required to establish state-of-the-art high-voltage testing laboratories acts as a barrier for smaller TIC players, leading to market consolidation.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period | |
|---|---|---|---|---|
| High Capital Expenditure (CAPEX) | -2.1% | Global | 2025 - 2028 | Initial investment in specialized labs limits market entry for smaller firms. |
| Fragmented Regulatory Landscape | -1.8% | Emerging Markets | 2025 - 2034 | Conflicting standards between regions increase compliance costs for OEMs. |
Ev Electronics Testing Inspection Certification Tic Market Opportunities Analysis
The transition toward sustainable mobility offers lucrative opportunities in second-life battery testing and wireless charging certification. As the first generation of EVs reaches the end of its life, TIC providers can develop specialized services for assessing the health and safety of reused batteries in stationary storage applications. Furthermore, the integration of Artificial Intelligence in TIC processes can significantly enhance efficiency, offering a first-mover advantage to companies that adopt automated inspection technologies. The emergence of hydrogen fuel cell vehicles also presents a long-term growth vertical for electronic control system testing.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period | |
|---|---|---|---|---|
| Second-Life Battery Certification | +2.9% | Europe & Japan | 2028 - 2034 | Testing used EV batteries for grid storage applications. |
| AI-Driven Automated Testing | +2.5% | North America & China | 2026 - 2034 | Using AI to predict failures and speed up the certification process. |
| Wireless EV Charging Standards | +1.7% | South Korea & Germany | 2027 - 2032 | Emerging market for resonance-based charging electronics testing. |
Ev Electronics Testing Inspection Certification Tic Market Challenges Impact Analysis
One of the primary challenges in the market is the acute shortage of skilled personnel proficient in both automotive engineering and high-voltage electronic testing. As vehicles become more reliant on complex software, TIC professionals must now possess advanced cybersecurity and coding knowledge. Furthermore, the rapid pace of innovation in silicon carbide (SiC) and gallium nitride (GaN) power electronics requires TIC labs to constantly upgrade their equipment, which can strain profit margins. Ensuring data privacy during the testing of connected vehicle electronics remains a persistent hurdle.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period | |
|---|---|---|---|---|
| Shortage of Skilled Workforce | -1.5% | Global | 2025 - 2034 | Difficulty in finding experts for high-voltage and software validation. |
| Cybersecurity & Data Privacy | -1.2% | United States & Europe | 2025 - 2030 | Protecting proprietary vehicle data during third-party inspection. |
Ev Electronics Testing Inspection Certification Tic Market - Updated Report Scope
The updated report provides a comprehensive analysis of the EV electronics TIC landscape, covering the shift from hardware-centric to software-centric vehicle validation. The scope includes detailed market sizing based on primary research from major TIC providers and automotive OEMs. It examines the impact of new standards such as ISO 26262 for functional safety and ISO/SAE 21434 for cybersecurity. The report also highlights the role of environmental testing, including thermal cycling and vibration analysis, which are critical for the longevity of electronic components in harsh automotive environments.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2.80 Billion |
| Market Forecast in 2034 | USD 10.25 Billion |
| Growth Rate | 15.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | SGS SA, Bureau Veritas, Intertek Group plc, TÜV SÜD, DEKRA SE, Eurofins Scientific, UL Solutions, Applus+, TÜV Rheinland, Element Materials Technology, Mistras Group, TUV NORD Group, Smithers, British Standards Institution (BSI), RINA S.p.A. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented by service type, application, and sourcing. Testing services dominate the market due to the volume of individual component checks required. Within applications, the Battery and Powertrain segment is the most significant, driven by safety certifications. Outsourced TIC services are growing faster than in-house testing as OEMs look to leverage the specialized expertise and global footprint of third-party TIC giants to handle complex international regulations.
- By Service Type:
- Testing: Includes EMC testing, safety testing, and performance testing of electronic components.
- Inspection: Visual and automated inspections of manufacturing processes and component assembly.
- Certification: Issuing official safety and quality marks required for market entry.
- By Application:
- Battery & Powertrain: Focuses on BMS (Battery Management Systems), inverters, and high-voltage cables.
- ADAS & Safety: Covers sensors, LiDAR, Radar, and autonomous driving control units.
- Infotainment & Connectivity: Includes V2X modules, telematics, and in-car entertainment electronics.
- Charging Infrastructure: Covers EVSE (Electric Vehicle Supply Equipment) safety and interoperability.
Regional Highlights
- Asia-Pacific: The largest market globally, China alone accounts for a massive portion of the revenue due to its integrated EV ecosystem and high adoption rates. The presence of major battery manufacturers like CATL and BYD drives huge demand for TIC services.
- North America: The fastest-growing region, fueled by the Inflation Reduction Act (IRA) which incentivizes domestic production of EV components, necessitating new local TIC facilities and certifications.
- Europe: The most stringent regulatory environment. The Euro NCAP and various EU directives regarding battery recycling and safety make it a high-value market for premium TIC services.
- Latin America & MEA: Emerging markets where growth is tied to the expansion of public charging infrastructure and the initial rollout of EV fleets in metropolitan areas.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Ev Electronics Testing Inspection Certification Tic Market.- SGS SA
- Bureau Veritas
- Intertek Group plc
- TÜV SÜD
- DEKRA SE
- Eurofins Scientific
- UL Solutions
- Applus+
- TÜV Rheinland
- Element Materials Technology
- Mistras Group
- TUV NORD Group
- Smithers
- British Standards Institution (BSI)
- RINA S.p.A.
- Cetecom (now part of CTC advanced)
- VDE Testing and Certification Institute
Frequently Asked Questions
What is driving the growth of the EV Electronics TIC Market?
Growth is primarily driven by the increasing complexity of EV electronic architectures, stringent government safety mandates for high-voltage systems, and the rapid expansion of the electric vehicle charging infrastructure globally.
Which region is the fastest growing in the EV electronics TIC sector?
North America is the fastest-growing region, projected to grow at a CAGR of 17.2% due to significant investments in localized battery manufacturing and new federal safety regulations.
What are the key standards for EV electronic testing?
Key standards include ISO 26262 for functional safety, UN ECE R100 for battery safety, ISO/SAE 21434 for cybersecurity, and various CISPR standards for electromagnetic compatibility (EMC).
How is AI impacting the TIC market for electric vehicles?
AI is being used to automate visual inspections, predict component failures through digital twins, and speed up the analysis of large datasets generated during high-voltage testing, thereby reducing time-to-market.
What is the market share of battery and powertrain testing?
The battery and powertrain segment currently accounts for approximately 40-45% of the total EV electronics TIC market, as it involves the most critical safety certifications for electric vehicles.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
