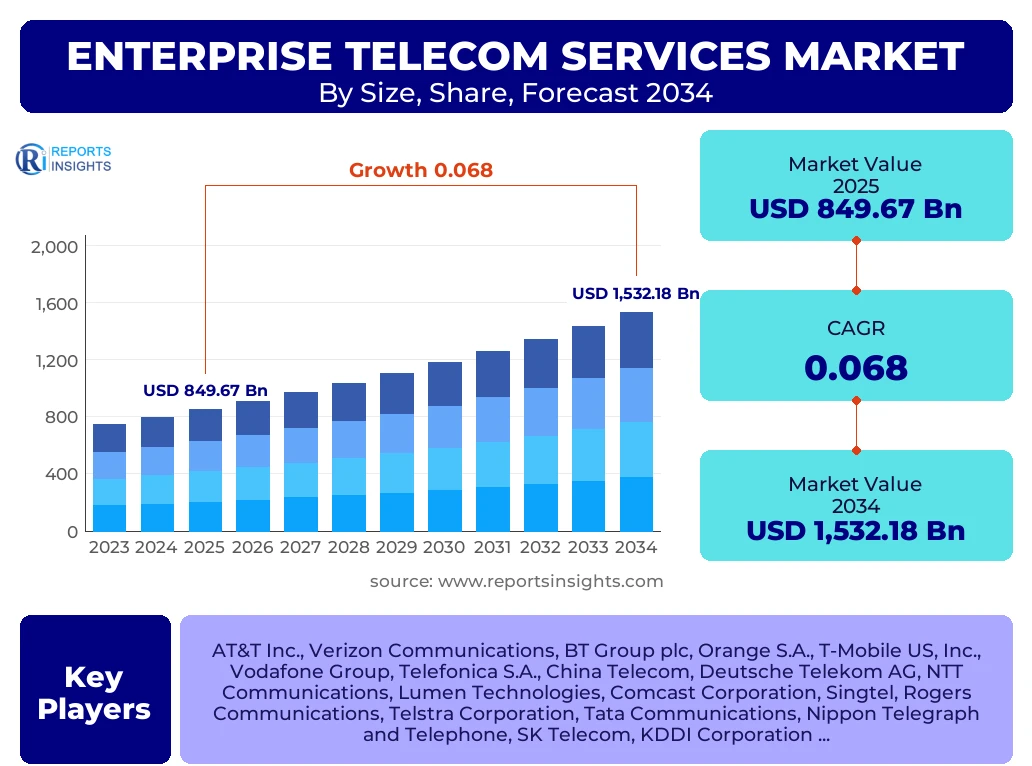
Enterprise Telecom Services Market
Enterprise Telecom Services Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711437 | Published On : November 02, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Enterprise Telecom Services Market Size
According to Reports Insights Consulting Pvt Ltd, The Enterprise Telecom Services Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.8% between 2025 and 2034. The market is estimated at USD 907.45 Billion in 2026 and is projected to reach USD 1,532.18 Billion by the end of the forecast period in 2034.
Key Enterprise Telecom Services Market Trends & Insights
The global enterprise telecom landscape is undergoing a radical shift as organizations transition from traditional legacy infrastructures to software-defined and cloud-native solutions. Current market trends indicate a significant surge in the adoption of SD-WAN (Software-Defined Wide Area Network) and 5G private networks, which offer enhanced reliability and lower latency for industrial applications. Analytical insights suggest that enterprise buyers are increasingly prioritizing bundled services that integrate cybersecurity directly into the telecommunications fabric, reflecting a move toward Secure Access Service Edge (SASE) frameworks. Furthermore, the rise of the hybrid workforce has fundamentally altered bandwidth consumption patterns, leading to a higher demand for robust fixed-line and mobile convergence solutions that maintain enterprise-grade security across distributed environments.
- North America remains the largest region by market value due to early 5G adoption and high concentration of tech-driven enterprises.
- Asia Pacific is the fastest-growing region, fueled by rapid industrialization, digital transformation initiatives in India and Southeast Asia, and massive infrastructure investments.
- The Data Services segment holds the largest market share, as corporate data traffic continues to explode through cloud computing and high-frequency digital transactions.
- Managed Services is emerging as a high-growth segment as companies outsource network management to reduce operational complexity and capital expenditure.
Key Takeaways Enterprise Telecom Services Market Size & Forecast
Market projections for the 2025–2034 period reflect a steady upward trajectory driven by the necessity of high-speed connectivity in the digital economy. Stakeholders are focusing on the integration of Artificial Intelligence within network operations to enable predictive maintenance and automated traffic routing. The convergence of IT and telecom services is creating new revenue streams for service providers who can offer end-to-end digital transformation consulting alongside core connectivity. Forecasts suggest that the integration of satellite-based enterprise connectivity will also gain traction, particularly for providing redundant links in remote operational sites within the energy and mining sectors.
- The United States and China are the leading individual country markets, collectively accounting for a substantial portion of the global investment in 5G enterprise infrastructure.
- Fixed-line services continue to dominate the revenue share in the short term, though mobile data services are closing the gap as 5G matures.
- Enterprise spending is shifting from Capex-intensive hardware to Opex-based cloud communication models (UCaaS).
- The BFSI (Banking, Financial Services, and Insurance) sector is the primary vertical driver due to stringent requirements for low-latency, highly secure data transmission.
Enterprise Telecom Services Market Drivers Analysis
The primary catalyst for growth in the enterprise telecom sector is the relentless pace of digital transformation across all industry verticals. As businesses migrate their core workloads to multi-cloud environments, the demand for high-capacity, resilient interconnectivity becomes non-negotiable. Additionally, the proliferation of Internet of Things (IoT) devices in manufacturing and logistics necessitates specialized telecom frameworks capable of handling massive device densities and real-time data processing at the edge.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Accelerated Adoption of 5G Private Networks | +2.1% | Global (Strongest in Germany, Japan, USA) | 2025 - 2030 |
| Expansion of Cloud-Based Communication (UCaaS/CCaaS) | +1.8% | North America and Western Europe | 2025 - 2034 |
| Growing Demand for SD-WAN Solutions | +1.5% | Global | 2026 - 2032 |
| Rise of Industrial IoT (IIoT) and Automation | +1.4% | Asia Pacific (China, India, South Korea) | 2027 - 2034 |
Enterprise Telecom Services Market Restraints Analysis
Despite robust growth, the market faces significant headwinds from the high cost of upgrading legacy infrastructure to support modern fiber-optic and 5G standards. Furthermore, varying regulatory environments across different jurisdictions create compliance hurdles for multinational enterprises seeking unified global telecom solutions. The volatility in spectrum auction pricing also impacts the ability of service providers to maintain aggressive roll-out schedules in emerging economies.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Capital Expenditure for Fiber/5G Rollouts | -1.2% | Emerging Markets (Africa, parts of Latin America) | 2025 - 2029 |
| Complex Regulatory and Data Sovereignty Laws | -0.8% | European Union (GDPR), China | 2025 - 2034 |
| Security Vulnerabilities in Software-Defined Architectures | -0.5% | Global | 2026 - 2030 |
Enterprise Telecom Services Market Opportunities Analysis
The integration of Artificial Intelligence and Machine Learning into network management presents a significant opportunity for service providers to offer "Self-Healing Networks" as a premium service. Moreover, the emergence of Edge Computing allows telecom operators to position themselves as critical infrastructure partners by hosting processing power closer to the enterprise end-user. There is also an untapped potential in providing specialized connectivity for the Metaverse and high-fidelity virtual collaboration tools as they move from consumer to enterprise applications.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Edge Computing and Distributed Cloud Services | +2.3% | North America and Developed APAC | 2026 - 2034 |
| AI-Driven Network Automation and Analytics | +1.9% | Global | 2027 - 2034 |
| Low Earth Orbit (LEO) Satellite Connectivity for Remote Sites | +1.1% | MEA, Latin America, Australia | 2025 - 2032 |
Enterprise Telecom Services Market Challenges Impact Analysis
One of the most persistent challenges is the escalating frequency and sophistication of cyberattacks targeting telecom backbones, necessitating constant and expensive security upgrades. Additionally, the market is seeing increased competition from "Over-the-Top" (OTT) players and tech giants who are bypassing traditional telcos by offering their own communication and networking software. Maintaining service quality and low latency while managing exponentially increasing data volumes remains a technical hurdle for many regional operators.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Intense Competition from OTT Communication Providers | -1.5% | Global | 2025 - 2034 |
| Cybersecurity Threats and Ransomware on Critical Networks | -1.1% | Global | 2025 - 2034 |
| Spectrum Scarcity and High Licensing Fees | -0.9% | India, Brazil, Southeast Asia | 2025 - 2028 |
Enterprise Telecom Services Market - Updated Report Scope
The scope of this report encompasses a thorough evaluation of the global enterprise telecom services sector, covering connectivity, managed services, and specialized vertical solutions. The analysis integrates historical data with current market dynamics to provide a robust forecast through 2034. It examines the shift from legacy TDM (Time Division Multiplexing) systems toward IP-based and software-defined frameworks, providing stakeholders with a clear roadmap of technology adoption across various enterprise sizes and industries.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 849.67 Billion |
| Market Forecast in 2034 | USD 1,532.18 Billion |
| Growth Rate | 6.8% CAGR |
| Number of Pages | 254 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | AT&T Inc., Verizon Communications, BT Group plc, Orange S.A., T-Mobile US, Inc., Vodafone Group, Telefonica S.A., China Telecom, Deutsche Telekom AG, NTT Communications, Lumen Technologies, Comcast Corporation, Singtel, Rogers Communications, Telstra Corporation, Tata Communications, Nippon Telegraph and Telephone, SK Telecom, KDDI Corporation, Swisscom. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the enterprise telecom market reveals a clear preference for data-centric and managed solutions as businesses move away from traditional voice-only contracts. The largest share is currently held by Large Enterprises, which have the capital to invest in dedicated fiber lines and private 5G deployments. However, the SME segment is witnessing the most rapid transformation as cloud-based telecom services lower the barrier to entry for advanced communication tools. From a vertical perspective, the BFSI sector remains the high-value leader, while Manufacturing is rapidly catching up due to Industry 4.0 requirements for massive machine-type communication.
- By Service Type: Includes Data Services (Fixed Broadband, IP-VPN, Leased Lines), Voice Services (Traditional and VoIP), Managed Services (Managed Security, Managed LAN/WAN), and Cloud-based Communication.
- By Enterprise Size: Segmented into Large Enterprises and Small & Medium Enterprises (SMEs), with SMEs showing high growth in UCaaS adoption.
- By Transmission Mode: Divided into Wireline (predominantly Fiber-optic) and Wireless (including 5G, 4G, and LEO Satellite).
- By Industry Vertical: Covers BFSI, IT and Telecommunications, Healthcare, Retail and E-commerce, Manufacturing, Government, and Logistics.
Regional Highlights
- North America: Currently the largest market by revenue, driven by a high density of data centers, the presence of major tech giants, and early nationwide 5G coverage in the United States.
- Asia Pacific: The fastest-growing region with a high CAGR, led by China's aggressive 5G infrastructure rollout and India's rapid digital transformation in the enterprise sector.
- Europe: A mature market focused on high-security standards and data privacy, with Germany and the UK leading in private 5G industrial applications.
- Middle East & Africa: Showing significant growth potential in urban hubs like Dubai and Riyadh, focusing on smart city initiatives and fiber-to-the-business (FTTB) expansions.
- Latin America: Growth is primarily driven by the modernization of telecom infrastructure in Brazil and Mexico to support burgeoning fintech and retail sectors.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Enterprise Telecom Services Market.- AT&T Inc.
- Verizon Communications
- BT Group plc
- Orange S.A.
- T-Mobile US, Inc.
- Vodafone Group
- Telefonica S.A.
- China Telecom
- Deutsche Telekom AG
- NTT Communications
- Lumen Technologies (CenturyLink)
- Comast Corporation
- Singtel
- Rogers Communications
- Telstra Corporation
- Tata Communications
- Nippon Telegraph and Telephone (NTT)
- SK Telecom
- KDDI Corporation
- Swisscom
Frequently Asked Questions
What is the projected market size of the Enterprise Telecom Services Market by 2034?
The market is projected to reach approximately USD 1,532.18 Billion by 2034, growing at a steady CAGR of 6.8% from 2025.
Which region is expected to show the fastest growth during the forecast period?
Asia Pacific is identified as the fastest-growing region due to increasing digital infrastructure investments and the rise of industrial automation in major economies like China and India.
How is 5G impacting the enterprise telecom services landscape?
5G is a major driver, enabling private wireless networks that offer lower latency and higher device capacity, which are essential for Industry 4.0 and real-time data analytics.
What are the key segments driving revenue in this market?
Data Services and Managed Services are the primary revenue drivers, as businesses prioritize high-speed internet, cloud connectivity, and outsourced network management.
What are the main challenges facing enterprise telecom providers?
Key challenges include high infrastructure costs (Capex), complex global regulatory compliance, and the increasing threat of cyberattacks on enterprise networks.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
