Electric Vehicle Charger Operations Maintenance Services Market
Electric Vehicle Charger Operations Maintenance Services Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711570 | Published On : November 06, 2026 |
Format : 


 | Author : Ashraf Shehata
Electric Vehicle Charger Operations Maintenance Services Market Size
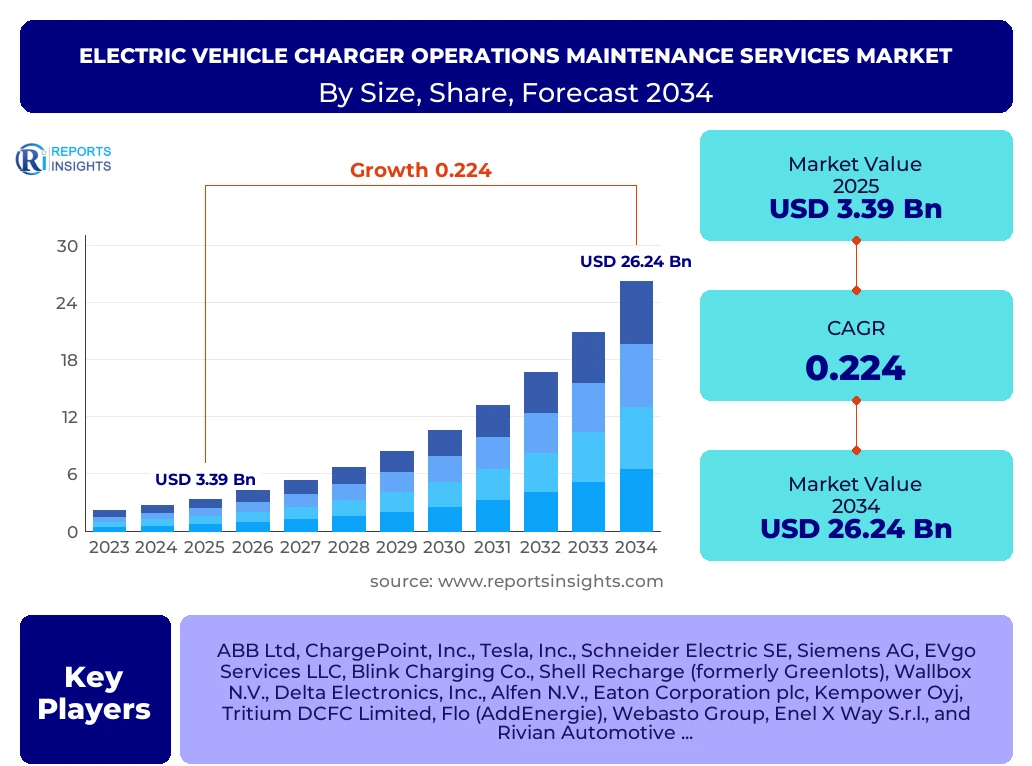
According to Reports Insights Consulting Pvt Ltd, The Electric Vehicle Charger Operations Maintenance Services Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 22.4% between 2025 and 2034. The market is estimated at USD 4.15 Billion in 2026 and is projected to reach USD 26.24 Billion by the end of the forecast period in 2034.
Key Electric Vehicle Charger Operations Maintenance Services Market Trends & Insights
The global landscape for Electric Vehicle (EV) charging infrastructure is shifting from rapid installation to long-term operational sustainability. Stakeholders are increasingly prioritizing high uptime and reliability, as the initial novelty of EV charging gives way to a demand for utility-grade dependability. Current market inquiries focus heavily on the integration of artificial intelligence for predictive diagnostics, the standardization of Service Level Agreements (SLAs) across cross-border networks, and the transition toward automated remote troubleshooting to minimize truck rolls and operational expenditure. Competitive benchmarking reveals that leading service providers are pivoting toward subscription-based maintenance models, moving away from reactive, one-off repair structures to ensure consistent revenue and network health.
- Largest Region: Asia-Pacific, driven by massive public charging deployments in China and South Korea.
- Fastest Growing Region: Europe, propelled by strict Alternative Fuels Infrastructure Regulation (AFIR) mandates regarding uptime and payment transparency.
- Largest Segment by Share: DC Fast Charging (DCFC) Maintenance, accounting for the highest value due to the technical complexity and thermal management requirements of high-power units.
- Emerging Trend: Integration of Vehicle-to-Grid (V2G) maintenance protocols as chargers become bidirectional energy hubs.
Key Takeaways Electric Vehicle Charger Operations Maintenance Services Market Size & Forecast
The market trajectory is fundamentally underpinned by the maturation of the electric mobility ecosystem, where "Charger Anxiety"—caused by broken or unresponsive equipment—is being addressed through professionalized Operations and Maintenance (O&M) frameworks. Analysis suggests that the next decade will see a consolidation of third-party service providers and a rise in specialized hardware-agnostic software platforms that facilitate real-time monitoring and automated fault detection. Regulatory pressure in North America and the European Union is setting the floor for reliability standards, often requiring 97% to 99% uptime for stations receiving public subsidies, which directly inflates the demand for comprehensive maintenance contracts.
- Dominant Country: China remains the global leader in total market value, supported by state-backed infrastructure initiatives.
- Critical Growth Factor: The professionalization of technician certification programs is alleviating the current skilled labor shortage in the EVSE sector.
- Key Market Shift: A transition from reactive maintenance (fixing what is broken) to preventive and predictive maintenance (preventing failures via data analytics).
- Infrastructure Evolution: The rise of ultra-fast charging hubs (350kW+) is increasing the technical requirements for liquid-cooling system maintenance.
Electric Vehicle Charger Operations Maintenance Services Market Drivers Analysis
The expansion of the O&M market is primarily catalyzed by the global surge in EV adoption and the subsequent necessity for reliable charging networks to support long-distance travel and fleet operations. Governments are increasingly tying financial incentives to performance metrics, forcing operators to invest in robust maintenance strategies to retain subsidies and avoid penalties.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Public Fast-Charging Networks | +7.2% | Global (High in North America & EU) | 2025 - 2034 |
| Stringent Government Uptime Mandates | +5.5% | United States (NEVI Program), European Union | 2026 - 2030 |
| Fleet Electrification Reliability Requirements | +4.8% | United Kingdom, China, Germany | 2025 - 2034 |
Electric Vehicle Charger Operations Maintenance Services Market Restraints Analysis
Despite rapid growth, the market faces significant hurdles related to the fragmentation of hardware standards and the aging of early-generation charging units. The high cost of specialized replacement components for older, proprietary systems often makes maintenance less economically viable than complete unit replacement in some scenarios.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shortage of Certified High-Voltage Technicians | -3.2% | North America, Australia | 2025 - 2028 |
| Interoperability and Legacy Hardware Issues | -2.5% | Europe (Early Adopter Countries) | 2025 - 2030 |
Electric Vehicle Charger Operations Maintenance Services Market Opportunities Analysis
The integration of advanced software solutions presents a massive opportunity for the O&M sector. Cloud-based diagnostics and over-the-air (OTA) updates are significantly reducing the need for physical inspections, allowing service providers to scale their operations across vast geographic areas without proportional increases in personnel.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| AI-Powered Predictive Maintenance Platforms | +6.1% | Japan, South Korea, United States | 2027 - 2034 |
| V2G and Energy Management Service Integration | +4.4% | Nordic Countries, Netherlands | 2028 - 2034 |
| Managed Services for Multi-Family Housing | +3.9% | Urban Centers (Global) | 2026 - 2034 |
Electric Vehicle Charger Operations Maintenance Services Market Challenges Impact Analysis
Operational challenges often stem from the harsh environmental conditions in which outdoor chargers are situated, leading to accelerated wear and tear. Furthermore, cybersecurity threats targeting charging infrastructure require O&M providers to offer increasingly sophisticated digital security maintenance alongside physical repairs.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Environmental Degradation (Corrosion/Heat) | -1.8% | Middle East, Coastal Regions | Ongoing |
| Cybersecurity Vulnerabilities in Smart Chargers | -2.1% | Global | 2025 - 2034 |
Electric Vehicle Charger Operations Maintenance Services Market - Updated Report Scope
The report provides a deep-dive analysis into the specialized O&M ecosystem, covering the full spectrum of services from remote monitoring and software updates to high-voltage component replacement. It evaluates the impact of global supply chain dynamics on spare parts availability and examines how emerging standards like OCPP (Open Charge Point Protocol) are influencing the competitive landscape of service providers.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 3.39 Billion |
| Market Forecast in 2034 | USD 26.24 Billion |
| Growth Rate | 22.4% CAGR |
| Number of Pages | 258 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | ABB Ltd, ChargePoint, Inc., Tesla, Inc., Schneider Electric SE, Siemens AG, EVgo Services LLC, Blink Charging Co., Shell Recharge (formerly Greenlots), Wallbox N.V., Delta Electronics, Inc., Alfen N.V., Eaton Corporation plc, Kempower Oyj, Tritium DCFC Limited, Flo (AddEnergie), Webasto Group, Enel X Way S.r.l., and Rivian Automotive, Inc. (O&M Division). |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Electric Vehicle Charger Operations Maintenance Services market is segmented by service delivery method, hardware specifications, and the end-user environment. The DC Fast Charging segment currently dominates the revenue share due to the intensive technical requirements of liquid-cooled cables and power conversion modules. However, the software-as-a-service (SaaS) component within maintenance is the fastest-growing sub-segment, as CPOs (Charge Point Operators) look for ways to resolve over 70% of issues remotely via cloud-based resetting and firmware updates.
- By Service Type: Preventive Maintenance, Corrective Maintenance, Software Support & Monitoring, and On-site Repair Services.
- By Charger Level: Level 1, Level 2, and DC Fast Chargers (including Ultra-Fast Charging).
- By Application: Public Charging Networks, Commercial/Retail Locations, Residential Units, and Fleet/Industrial Depots.
- By Power Output: Below 50 kW, 50-150 kW, and Above 150 kW.
Regional Highlights
- Asia-Pacific (APAC): The largest market globally, led by China's aggressive "New Infrastructure" plan. The region benefits from a highly integrated supply chain for EVSE components, making replacement parts more accessible.
- Europe: The most regulated market, with the AFIR mandate requiring high uptime and transparent maintenance reporting across the Trans-European Transport Network (TEN-T). Germany, Norway, and the UK are the primary hubs.
- North America: Experiencing rapid acceleration due to the NEVI (National Electric Vehicle Infrastructure) formula program, which earmarks billions for charging corridors, contingent on strict 97% uptime O&M contracts.
- Middle East & Africa: An emerging market focusing on high-temperature resilient O&M solutions, particularly in the UAE and Saudi Arabia as part of their sustainability visions.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Electric Vehicle Charger Operations Maintenance Services Market.- ABB Ltd
- ChargePoint, Inc.
- Tesla, Inc.
- Schneider Electric SE
- Siemens AG
- EVgo Services LLC
- Blink Charging Co.
- Shell Recharge
- Wallbox N.V.
- Delta Electronics, Inc.
- Alfen N.V.
- Eaton Corporation plc
- Kempower Oyj
- Tritium DCFC Limited
- Flo (AddEnergie)
- Webasto Group
- Enel X Way S.r.l.
- Rivian Automotive, Inc.
Frequently Asked Questions
What is the industry standard for EV charger uptime?
The current gold standard for public charging networks is 97% to 99% uptime. Government funding programs, such as the U.S. NEVI program, often mandate a minimum of 97% uptime, calculated over a rolling 12-month period, including hardware and software availability.
What are the primary causes of EV charger downtime?
Downtime is primarily caused by internal component failure (power modules), connector damage due to improper handling, software communication errors (OCPP connectivity issues), and cellular network instability preventing payment authorization.
How does preventive maintenance differ from corrective maintenance in this market?
Preventive maintenance involves scheduled inspections, filter cleaning for cooling systems, and tightening of electrical connections to prevent failure. Corrective maintenance is reactive, occurring after a fault is detected, and involves repairing or replacing broken components.
Are maintenance costs for DC fast chargers higher than Level 2 chargers?
Yes, maintenance for DC fast chargers is significantly more expensive due to complex cooling systems, high-voltage safety protocols, the need for specialized technicians, and the higher cost of internal power conversion electronics compared to simpler AC Level 2 units.
How is AI influencing the EV charger O&M market?
AI is being utilized for predictive maintenance by analyzing historical sensor data to identify patterns that precede hardware failure. This allows CPOs to schedule repairs before a charger goes offline, significantly improving uptime and customer satisfaction.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
