Electric UTV and ATV Powertrain Market
Electric UTV and ATV Powertrain Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711362 | Published On : October 29, 2026 |
Format : 


 | Author : Ashraf Shehata
Electric UTV and ATV Powertrain Market Size
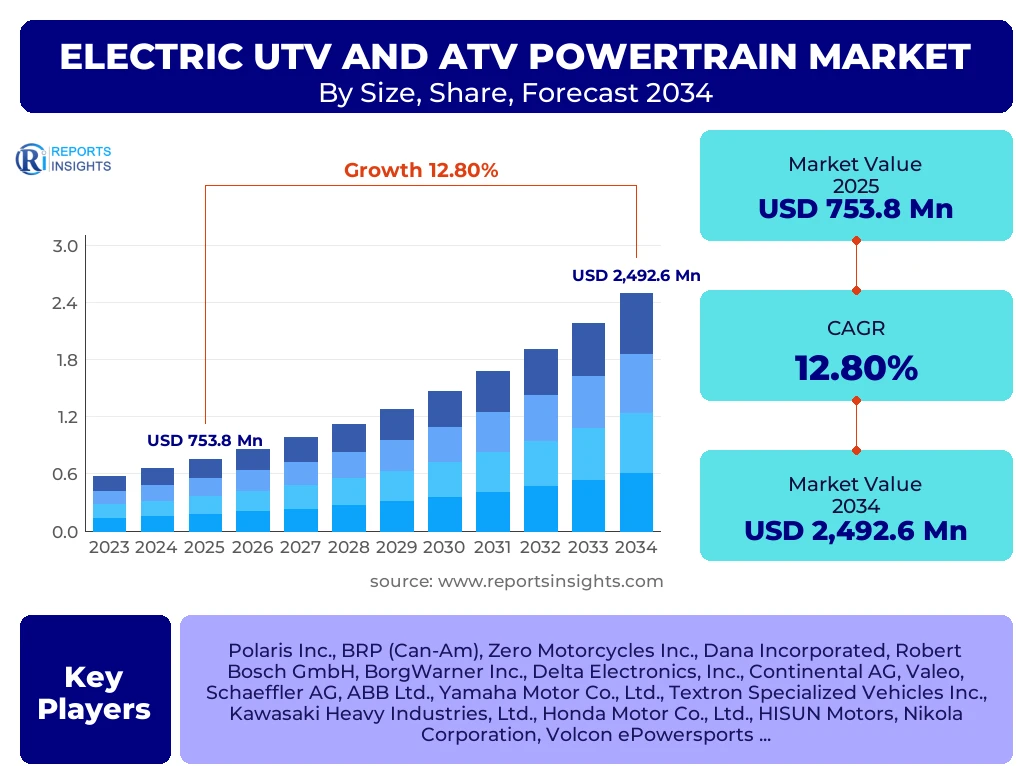
According to Reports Insights Consulting Pvt Ltd, The Electric UTV and ATV Powertrain Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 12.8% between 2025 and 2034. The market is estimated at USD 850.4 Million in 2026 and is projected to reach USD 2,492.6 Million by the end of the forecast period in 2034.
Key Electric UTV and ATV Powertrain Market Trends & Insights
The global Electric UTV (Utility Task Vehicle) and ATV (All-Terrain Vehicle) powertrain market is witnessing a profound transformation driven by the convergence of automotive electrification technologies and the specialized requirements of off-road performance. As recreational users and industrial operators seek alternatives to internal combustion engines, the focus has shifted toward high-torque density motors and integrated power electronics that can withstand rigorous environments. Current market intelligence suggests that the integration of Silicon Carbide (SiC) inverters and high-capacity lithium-ion battery packs is becoming the standard for premium electric off-road vehicles. Furthermore, the shift is not merely environmental; users are prioritizing the near-silent operation of electric powertrains for applications such as hunting, agriculture, and military reconnaissance, where stealth and low acoustic signatures are paramount. Competitive benchmarking reveals that manufacturers are increasingly forming strategic alliances with battery cell producers to ensure a stable supply chain and to optimize energy density for extended range in remote locations.
- Largest Region: North America remains the dominant market shareholder due to high consumer spending on recreational powersports and a robust agricultural sector adopting electric utility vehicles.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR, fueled by the rapid expansion of manufacturing capabilities in China and India, coupled with rising eco-tourism activities.
- Largest Segment by Component: The battery pack segment accounts for the largest value share, as it represents the single most expensive and technologically critical component of the electric powertrain.
- Largest Segment by Vehicle Type: Electric UTVs currently lead the market over ATVs, driven by their higher payload capacity and versatility in commercial and industrial settings.
- Emerging Trend: The adoption of modular powertrain architectures that allow manufacturers to scale power output and battery capacity across multiple vehicle platforms is gaining significant traction.
Key Takeaways Electric UTV and ATV Powertrain Market Size & Forecast
Analysis of market dynamics indicates that the transition to electric powertrains in the off-road sector is accelerating faster than previously anticipated, largely due to improvements in battery thermal management systems and the falling cost of permanent magnet synchronous motors. Stakeholders are focusing on the total cost of ownership (TCO), where electric UTVs and ATVs offer significant savings in maintenance and fuel over their operational lifespan. Market forecasts suggest that the utility segment will serve as the primary engine of growth through 2034, as government agencies and large-scale agricultural enterprises implement green procurement policies. The competitive landscape is also evolving, with traditional powersports giants investing heavily in dedicated electric platforms rather than adapting existing chassis, leading to more efficient packaging and superior weight distribution. Projections confirm that as charging infrastructure reaches more rural and trail-head locations, the barrier to adoption for recreational users will diminish, further solidifying the market long-term growth trajectory.
- Market Leadership: The United States and Canada are the primary contributors to global revenue, supported by a mature trail infrastructure and high levels of outdoor participation.
- Technological Shift: The transition from lead-acid to lithium-ion (LiFePO4 and NMC) chemistries is nearly complete in the high-performance segment, enhancing both range and durability.
- Regulatory Influence: Increasingly stringent emission regulations in European and North American national parks are mandating the use of zero-emission vehicles, directly boosting powertrain demand.
- Industrial Integration: Mining and construction sectors are emerging as high-value end-users for electric UTVs due to zero exhaust emissions in enclosed or sensitive environments.
- Supply Chain Focus: Key players are prioritizing localized production of motors and controllers to mitigate global logistics risks and reduce lead times for vehicle OEMs.
Electric UTV and ATV Powertrain Market Drivers Analysis
The acceleration of the electric UTV and ATV powertrain market is underpinned by several critical factors, ranging from technological breakthroughs to changing consumer preferences. The primary driver is the significant advancement in battery energy density, which has addressed the long-standing concern of range anxiety in off-road environments. Additionally, the inherent performance advantages of electric motors—specifically the delivery of instantaneous peak torque—make them exceptionally suited for the heavy-duty hauling and steep-climbing tasks common to UTV and ATV usage. Noise reduction also plays a pivotal role, as electric powertrains enable quiet operation that is highly valued in residential areas, wildlife management, and tactical military applications.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advancements in Battery Density and Charging Speeds | +4.2% | Global (Major in North America/Europe) | 2025–2034 |
| Government Incentives and Zero-Emission Mandates | +3.5% | European Union and United States | 2025–2030 |
| Operational Cost Savings and Lower Maintenance | +2.8% | Global (Focus on Agricultural sectors) | 2026–2034 |
| Demand for Quiet Operation in Recreation and Defense | +2.3% | North America and Asia-Pacific | 2025–2034 |
Electric UTV and ATV Powertrain Market Restraints Analysis
Despite the optimistic growth projections, the market faces notable restraints that could temper the pace of adoption. The most prominent barrier remains the high initial acquisition cost of electric vehicles compared to their internal combustion engine (ICE) counterparts, primarily driven by the cost of the powertrain components. Furthermore, the lack of charging infrastructure in remote off-road locations limits the utility of these vehicles for long-distance trail riding. Concerns regarding the durability and safety of high-voltage battery packs in extreme conditions, such as deep water crossings or extreme temperature fluctuations, also remain a technical hurdle for manufacturers.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Upfront Cost of Powertrain Components | -3.1% | Global (Emerging Markets) | 2025–2028 |
| Limited Off-Road Charging Infrastructure | -2.5% | Rural North America and Australia | 2025–2034 |
| Thermal Management Challenges in Extreme Climates | -1.8% | Nordic Regions and Middle East | 2026–2030 |
Electric UTV and ATV Powertrain Market Opportunities Analysis
The evolving landscape presents significant opportunities for innovation and market expansion. The development of vehicle-to-load (V2L) technology allows electric UTVs to function as mobile power banks, providing electricity for tools and equipment in remote jobsites, which is a massive value proposition for the construction and utility sectors. Additionally, there is a growing opportunity in the "refit" market, where aftermarket electric powertrain kits are developed for existing ICE vehicle chassis. As the technology matures, the integration of autonomous driving features and smart fleet management systems into the powertrain control unit offers a new frontier for high-tech off-road applications.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of Vehicle-to-Load (V2L) Features | +3.8% | North America and Europe | 2027–2034 |
| Expansion into Mining and Underground Applications | +2.9% | Australia, Canada, and Africa | 2026–2034 |
| Development of Solid-State Battery Off-Road Applications | +2.1% | Japan, South Korea, and USA | 2029–2034 |
Electric UTV and ATV Powertrain Market Challenges Impact Analysis
The primary challenges involve technical robustness and supply chain volatility. Engineering a powertrain that maintains high efficiency while being completely sealed against dust, mud, and water requires sophisticated sealing and cooling solutions. Moreover, the reliance on rare-earth minerals for high-performance permanent magnet motors exposes the market to geopolitical risks and price fluctuations. Manufacturers must also navigate a complex landscape of safety standards that vary significantly between recreational vehicles and industrial equipment, complicating the design of standardized powertrain modules.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Volatility for Rare Earth Materials | -2.4% | Global Supply Chains | 2025–2034 |
| Complex Engineering for Extreme Durability (IP67/69K) | -1.9% | High-Performance Manufacturers | 2025–2029 |
| Inconsistent Global Regulatory Standards | -1.2% | International Exporters | 2026–2032 |
Electric UTV and ATV Powertrain Market - Updated Report Scope
This comprehensive report provides a deep-dive analysis of the global Electric UTV and ATV Powertrain market, covering the entire value chain from raw material suppliers to vehicle OEMs. The scope includes a detailed evaluation of core components such as traction motors, battery modules, power electronics (inverters/converters), and transmission systems. It analyzes the market through multiple lenses, including vehicle type (ATV vs. UTV), drive configuration (AWD vs. 2WD), and end-use applications (Utility, Recreation, Military, and Industrial). By leveraging historical data and current market indicators, the report offers a granular forecast of market size and growth potential across all major geographic regions and key countries.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 753.8 Million |
| Market Forecast in 2034 | USD 2,492.6 Million |
| Growth Rate | 12.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Polaris Inc., BRP (Can-Am), Zero Motorcycles Inc., Dana Incorporated, Robert Bosch GmbH, BorgWarner Inc., Delta Electronics, Inc., Continental AG, Valeo, Schaeffler AG, ABB Ltd., Yamaha Motor Co., Ltd., Textron Specialized Vehicles Inc., Kawasaki Heavy Industries, Ltd., Honda Motor Co., Ltd., HISUN Motors, Nikola Corporation, Volcon ePowersports, Segway Technology Co., Ltd., Greenworks Tools |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Electric UTV and ATV Powertrain market is segmented by component, vehicle type, power output, and end-user, reflecting the diverse technical requirements across different applications. The component segment is the most critical for technological benchmarking, as improvements in motors and battery chemistry directly impact vehicle performance. The vehicle type segment highlights the distinct market paths of ATVs, which are predominantly recreational, and UTVs, which are increasingly utilized as serious workhorse machines in industrial and commercial sectors. Power output segmentation is essential for understanding the transition from light-duty task vehicles to high-performance racing and heavy-duty utility platforms.
- By Component:
- Battery Packs (High-voltage lithium-ion systems)
- Electric Traction Motors (PMSM, Induction, BLDC)
- Motor Controllers and Inverters
- DC-DC Converters and On-board Chargers
- Power Distribution Units (PDU)
- Transmissions and Drivetrain Components
- Thermal Management Systems
- By Vehicle Type:
- Electric All-Terrain Vehicles (ATVs)
- Electric Utility Task Vehicles (UTVs) / Side-by-Sides (SxS)
- By Power Output:
- Low Power (Less than 20 kW)
- Medium Power (20 kW to 50 kW)
- High Power (More than 50 kW)
- By Drive Configuration:
- Two-Wheel Drive (2WD)
- Four-Wheel Drive / All-Wheel Drive (4WD/AWD)
- By End-Use Application:
- Personal Recreation and Sports
- Agriculture and Forestry
- Hunting and Wildlife Management
- Mining, Construction, and Industrial
- Military and Law Enforcement
Regional Highlights
- North America: The United States and Canada represent the largest market share, driven by a deeply ingrained culture of off-road recreation and a large number of hobbyist and commercial farmers adopting electric solutions.
- Europe: The region is characterized by the fastest adoption of zero-emission regulations, with countries like Norway, Germany, and France leading the demand for electric powertrains in forestry and municipal maintenance.
- Asia-Pacific: This region is the manufacturing hub for the market, with China leading in battery production and low-cost motor manufacturing. It also shows the highest growth potential in the eco-tourism and agricultural segments.
- Latin America: Growth is primarily centered in Brazil and Argentina, where large-scale agriculture and mining operations are beginning to explore electric UTVs for cost-efficiency.
- Middle East and Africa: The market is emerging, with a focus on specialized military and safari applications that require quiet, low-heat signature vehicles.

Top Key Players
The market research report includes a detailed profile of leading top-wise companies in the Electric UTV and ATV Powertrain Market, focusing on their technological innovations, strategic partnerships, and market positioning.- Polaris Inc.
- BRP (Can-Am)
- Zero Motorcycles Inc.
- Dana Incorporated
- Robert Bosch GmbH
- BorgWarner Inc.
- Delta Electronics, Inc.
- Continental AG
- Valeo
- Schaeffler AG
- ABB Ltd.
- Yamaha Motor Co., Ltd.
- Textron Specialized Vehicles Inc.
- Kawasaki Heavy Industries, Ltd.
- Honda Motor Co., Ltd.
- HISUN Motors
- Nikola Corporation
- Volcon ePowersports
- Segway Technology Co., Ltd.
- Greenworks Tools
Frequently Asked Questions
What is the primary advantage of electric powertrains in UTVs and ATVs?
The primary advantages include instantaneous peak torque for better climbing and hauling, significantly reduced noise levels for hunting and residential use, and lower long-term maintenance costs due to fewer moving parts compared to internal combustion engines.
Which component is the most expensive in an electric UTV powertrain?
The battery pack remains the most expensive component, typically accounting for 40% to 50% of the total powertrain cost. However, costs are gradually decreasing as manufacturing scales and battery chemistry improves.
How does the range of an electric ATV compare to a gas-powered one?
Currently, most high-end electric ATVs offer a range of 40 to 80 miles per charge depending on terrain and load. While gas vehicles can be refilled quickly, electric vehicles are catching up through larger battery capacities and fast-charging technologies.
Are electric UTVs suitable for heavy-duty agricultural work?
Yes, electric UTVs are increasingly preferred for agriculture because they provide high torque at low speeds, require no fuel storage on-site, and can be charged using farm-based solar installations, providing a sustainable and cost-effective work solution.
Which region is expected to see the fastest growth in the electric powertrain market?
The Asia-Pacific region is expected to witness the fastest growth due to rising industrialization, a strong focus on electric vehicle manufacturing in China, and increasing adoption of electric utility vehicles in the agricultural sectors of India and Southeast Asia.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
