Dry Eye Treatment Devices Market
Dry Eye Treatment Devices Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711084 | Published On : October 05, 2026 |
Format : 


 | Author : Erika Grotto
Dry Eye Treatment Devices Market Size
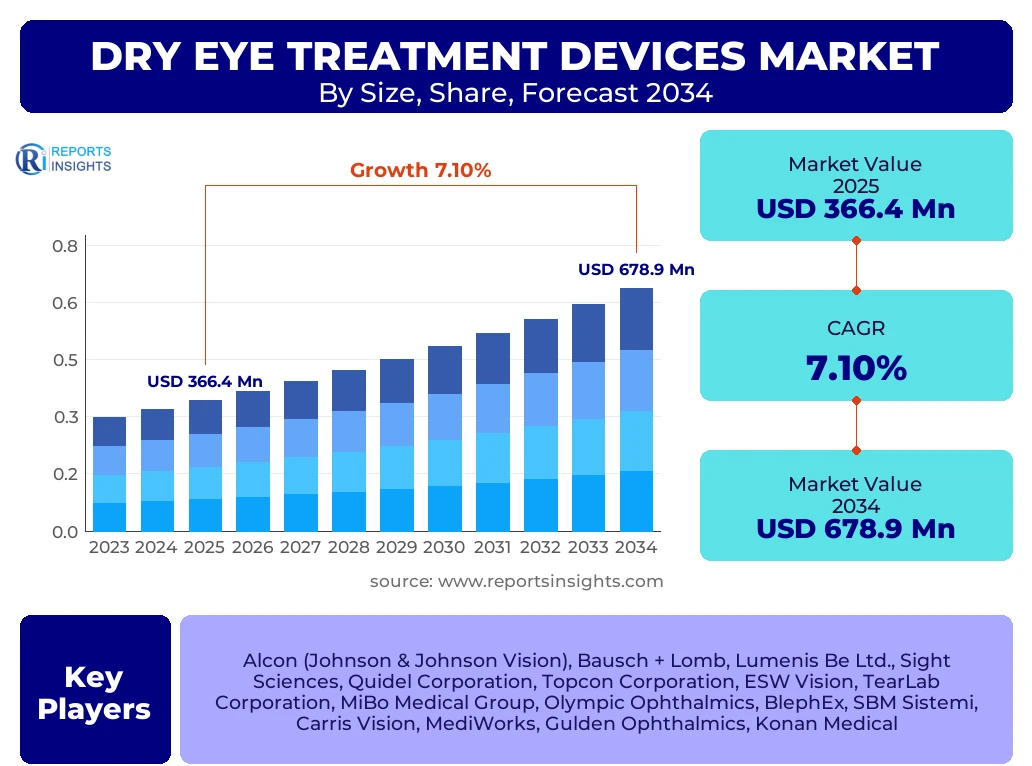
According to Reports Insights Consulting Pvt Ltd, The Dry Eye Treatment Devices Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.1% between 2025 and 2034. The market is estimated at USD 392.4 Million in 2026 and is projected to reach USD 678.9 Million by the end of the forecast period in 2034.
Key Dry Eye Treatment Devices Market Trends & Insights
The global dry eye treatment devices market is undergoing a significant transformation, shifting from palliative care such as artificial tears toward advanced interventional therapies that address the underlying causes of ocular surface disease. The increasing prevalence of Meibomian Gland Dysfunction (MGD), which accounts for approximately 86% of all dry eye cases, is driving the demand for specialized thermal pulsation and intense pulsed light (IPL) systems. Furthermore, the rising incidence of Digital Eye Strain (DES) among the younger demographic, coupled with a growing geriatric population globally, is expanding the patient pool requiring long-term clinical management rather than temporary over-the-counter solutions.
- Largest Region: North America remains the dominant market due to high healthcare expenditure and early adoption of advanced ophthalmic technologies.
- Fastest Growing Region: Asia-Pacific is expected to exhibit the highest CAGR, fueled by rapid urbanization, increasing screen time, and improving healthcare infrastructure in China and India.
- Largest Segment by Technology: Thermal Pulsation Systems currently hold the largest market share due to their proven clinical efficacy in treating MGD.
- Emerging Trend: Integration of diagnostic imaging with therapeutic devices to provide a "screen-and-treat" workflow in specialized ophthalmic clinics.
Key Takeaways Dry Eye Treatment Devices Market Size & Forecast
The market forecast indicates a robust trajectory driven by technological miniaturization and the transition of dry eye management from secondary to primary eye care settings. As clinicians increasingly recognize dry eye as a chronic progressive disease, there is a heightened focus on early intervention using devices that can restore the natural lipid layer of the tear film. The clinical evidence supporting the longevity of results from device-based treatments compared to daily pharmaceutical drops is a primary catalyst for market expansion over the next decade.
- The United States is the leading country in market value, supported by favorable reimbursement codes for certain diagnostic procedures.
- Intense Pulsed Light (IPL) therapy is gaining rapid traction as a multi-modal treatment for both inflammatory dry eye and ocular rosacea.
- Strategic collaborations between medical device manufacturers and optometric associations are increasing awareness and adoption rates.
- The forecast period will see a surge in portable and handheld treatment devices designed for smaller clinical practices.
- Market consolidation is expected as major ophthalmic players acquire niche technology startups to broaden their dry eye portfolios.
Dry Eye Treatment Devices Market Drivers Analysis
The primary drivers for the dry eye treatment devices market include the global escalation of digital device usage, which has led to a significant decrease in blink rates and subsequent evaporative dry eye. Additionally, the aging global population is more susceptible to hormonal changes and systemic conditions that exacerbate ocular surface dryness. The shift in clinical preference toward durable medical equipment that offers long-lasting symptomatic relief is further propelling market growth.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Prevalence of Meibomian Gland Dysfunction (MGD) | +2.1% | Global | 2025 - 2034 |
| Technological Advancements in Thermal Pulsation | +1.8% | North America & Europe | 2025 - 2030 |
| Increased Screen Time and Digital Eye Strain | +1.5% | Asia-Pacific | 2025 - 2034 |
Dry Eye Treatment Devices Market Restraints Analysis
Market growth is somewhat hindered by the high upfront cost of advanced treatment systems, which can be prohibitive for independent optometry practices. Additionally, the lack of comprehensive insurance coverage for elective dry eye procedures often requires patients to pay out-of-pocket, limiting the accessible patient base in price-sensitive markets.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Specialized Equipment | -1.2% | Emerging Economies | 2025 - 2028 |
| Limited Reimbursement for Device-Based Procedures | -0.9% | United States & UK | 2025 - 2034 |
Dry Eye Treatment Devices Market Opportunities Analysis
There is a significant opportunity in the development of multi-functional platforms that combine diagnostic lipid layer analysis with therapeutic heat application. Furthermore, expanding into the "home-use" professional-grade device segment represents a largely untapped market for patients requiring maintenance therapy between clinical visits.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion in Emerging Asia-Pacific Markets | +1.4% | China, India, SE Asia | 2027 - 2034 |
| Integration of AI for Personalized Treatment Protocols | +0.8% | Global | 2026 - 2034 |
Dry Eye Treatment Devices Market Challenges Impact Analysis
The market faces challenges regarding the lack of standardized clinical protocols for device-based treatments across different regions. Moreover, competition from emerging pharmacological therapies, including novel nasal sprays and anti-inflammatory drops, necessitates a clear value proposition for mechanical and thermal interventions.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Competition from Low-Cost Pharmaceutical Alternatives | -0.7% | Global | 2025 - 2034 |
| Stringent Regulatory Approval Pathways | -0.5% | European Union (MDR) | 2025 - 2027 |
Dry Eye Treatment Devices Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the technological landscape, competitive dynamics, and regulatory environment of the dry eye treatment devices industry. It covers various modalities ranging from clinic-based thermal pulsation to advanced light therapies, providing a granular view of market movements across five major geographic regions and various end-user segments.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 366.4 Million |
| Market Forecast in 2034 | USD 678.9 Million |
| Growth Rate | 7.1% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Alcon (Johnson & Johnson Vision), Bausch + Lomb, Lumenis Be Ltd., Sight Sciences, Quidel Corporation, Topcon Corporation, ESW Vision, TearLab Corporation, MiBo Medical Group, Olympic Ophthalmics, BlephEx, SBM Sistemi, Carris Vision, MediWorks, Gulden Ophthalmics, Konan Medical |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on technology, application, and end-user, with technology being the most critical differentiator. Thermal pulsation systems lead the market by providing automated, consistent heat and pressure to the eyelids, effectively clearing obstructions in the meibomian glands. The intense pulsed light (IPL) segment is the fastest-growing technology due to its ability to address inflammation and telangiectasia associated with ocular rosacea, which is a significant contributor to dry eye symptoms.
- By Technology:
- Thermal Pulsation Systems (Leading segment)
- Intense Pulsed Light (IPL) (Fastest growing)
- Meibomian Gland Expression (MGE) Devices
- Microblepharoexfoliation Systems
- Others (Nasal Neurostimulation, Eyelid Warming Masks)
- By Application:
- Evaporative Dry Eye (Highest share due to MGD prevalence)
- Aqueous Deficient Dry Eye
- Mixed Dry Eye Syndrome
- By End-User:
- Ophthalmic Clinics (Primary setting for advanced device procedures)
- Hospitals and Surgical Centers
- Specialty Eye Care Chains
Regional Highlights
- North America: Holds over 40% of the market share. The presence of major industry players and a proactive approach toward ocular health diagnostic screening contributes to its dominance. The US market is characterized by a high adoption rate of premium procedures like LipiFlow and TearCare.
- Europe: The second-largest market, with Germany, France, and the UK leading in technological adoption. Regulatory clarity under the MDR is streamlining the entry of innovative diagnostic-therapeutic hybrid devices.
- Asia-Pacific: Expected to witness a CAGR of over 8.5%. Factors such as the massive population base in China and India, increasing healthcare literacy, and the high prevalence of screen-induced dry eye among urban professionals are driving demand.
- Latin America & MEA: These regions are showing steady growth, particularly in the private healthcare sector in Brazil, Mexico, and the GCC countries, where medical tourism for ophthalmic procedures is on the rise.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Dry Eye Treatment Devices Market.- Alcon Inc. (Johnson & Johnson Vision)
- Bausch + Lomb
- Lumenis Be Ltd.
- Sight Sciences
- Quidel Corporation
- Topcon Corporation
- ESW Vision
- TearLab Corporation
- MiBo Medical Group
- Olympic Ophthalmics
- BlephEx
- SBM Sistemi
- Carris Vision
- MediWorks
- Gulden Ophthalmics
- Konan Medical
- Aier Eye Hospital Group
- EssilorLuxottica
- Bruder Healthcare
- Scope Eyecare
Frequently Asked Questions
What is the main driver for the Dry Eye Treatment Devices Market?
The primary driver is the increasing prevalence of Meibomian Gland Dysfunction (MGD) and the rise in Digital Eye Strain caused by prolonged use of computers and smartphones, which necessitates advanced device-based clinical interventions.
Which technology is leading the Dry Eye Treatment Devices Market?
Thermal Pulsation Systems currently lead the market because they provide a standardized, automated treatment for MGD, though Intense Pulsed Light (IPL) is rapidly gaining share as an effective anti-inflammatory modality.
Is the market for dry eye devices growing in Asia-Pacific?
Yes, Asia-Pacific is the fastest-growing region due to a combination of high screen-time usage, an aging demographic, and increasing investment in specialty ophthalmic clinics across China and India.
What are the major barriers to market growth?
The high cost of equipment and the fact that many device-based dry eye treatments are considered elective and are not fully covered by health insurance are the major barriers to widespread adoption.
How does IPL therapy work for dry eye?
IPL therapy uses specific wavelengths of light to treat the skin around the eyes, reducing inflammation, closing abnormal blood vessels (telangiectasia), and warming the meibomian glands to improve the quality of the tear film's lipid layer.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
