Point Of Care Infectiodisease Testing Market
Point Of Care Infectiodisease Testing Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710991 | Published On : September 25, 2026 |
Format : 


 | Author : Erika Grotto
Point Of Care Infectious Disease Testing Market Size
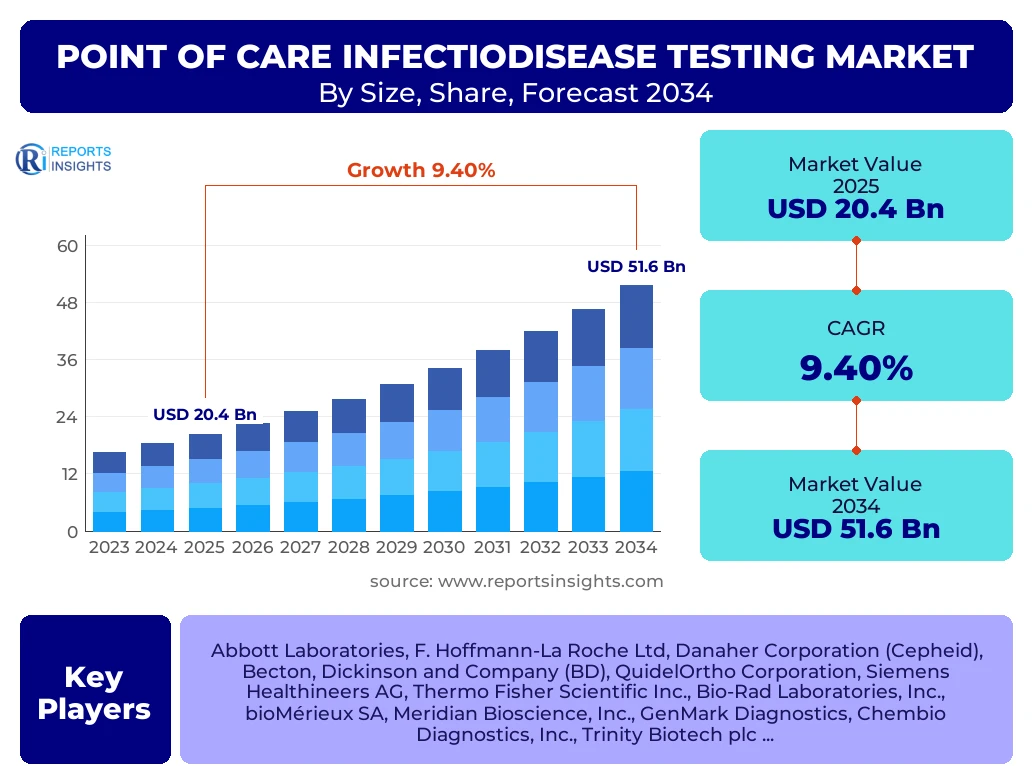
According to Reports Insights Consulting Pvt Ltd, The Point Of Care Infectious Disease Testing Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 9.4% between 2026 and 2034. The market is estimated at USD 22.4 Billion in 2026 and is projected to reach USD 51.6 Billion by the end of the forecast period in 2034.
Key Point Of Care Infectious Disease Testing Market Trends & Insights
The global landscape for decentralized diagnostics is undergoing a transformative shift, driven by the convergence of microfluidic technology, artificial intelligence, and the increasing demand for rapid clinical decision-making. Stakeholders are increasingly prioritizing diagnostic platforms that offer laboratory-grade accuracy at the patient bedside, reducing the turnaround time from hours to minutes. This transition is particularly evident in the management of respiratory infections, sexually transmitted diseases, and emerging viral pathogens, where immediate intervention is critical for both patient outcomes and public health containment. The integration of digital health connectivity is further revolutionizing the market, allowing real-time data transmission to electronic health records and centralized surveillance systems.
- North America remains the largest regional market, underpinned by advanced healthcare infrastructure and high adoption of molecular diagnostics.
- The Asia-Pacific region is identified as the fastest-growing market, propelled by expanding healthcare access and rising prevalence of infectious diseases in emerging economies.
- The molecular diagnostics segment is capturing the largest share of market value due to its superior sensitivity and specificity compared to traditional immunoassay-based tests.
- Consumables and assay kits represent the highest-grossing product segment, driven by high testing volumes and the recurring nature of diagnostic demand.
- The transition toward multiplex testing, which allows for the simultaneous detection of multiple pathogens from a single sample, is a primary trend defining competitive benchmarking.
Key Takeaways Point Of Care Infectious Disease Testing Market Size & Forecast
The market trajectory for point-of-care infectious disease diagnostics is characterized by sustained capital investment and a strategic pivot toward home-based and community-based testing environments. Large-scale epidemiological shifts and the threat of future pandemics have solidified the necessity for robust, scalable diagnostic solutions that bypass the logistical bottlenecks of centralized laboratories. Market forecasts indicate that while the post-pandemic stabilization has occurred, the baseline demand for rapid testing remains significantly higher than pre-2020 levels, particularly for influenza, RSV, and strep testing. Furthermore, the expansion of healthcare reimbursement policies for decentralized tests is facilitating broader market penetration across diverse clinical settings.
- The United States holds a dominant position in the global market, supported by a favorable regulatory environment and early adoption of novel diagnostic technologies.
- Increased prevalence of chronic infectious diseases such as HIV and Hepatitis in sub-Saharan Africa and parts of Asia is driving targeted investment in portable diagnostic platforms.
- Strategic collaborations between diagnostic manufacturers and tele-health providers are emerging as a critical growth lever for home-testing applications.
- Advancements in CRISPR-based diagnostics and isothermal amplification are expected to lower the cost and complexity of high-sensitivity molecular POC tests.
- The hospital and emergency care segment continues to be the primary end-user, though pharmacy-based testing and urgent care centers are rapidly gaining market share.
Point Of Care Infectious Disease Testing Market Drivers Analysis
The expansion of the point-of-care diagnostic sector is primarily fueled by the critical need for rapid therapeutic turnaround and the global escalation of infectious disease outbreaks. As healthcare systems move toward value-based care, the ability to diagnose and treat patients during a single visit significantly improves operational efficiency and patient satisfaction. Furthermore, the rise in antimicrobial resistance is necessitating precise diagnostic confirmation before the administration of antibiotics, positioning POC testing as a cornerstone of global antimicrobial stewardship programs.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period | +2.8% | Global (Strongest in US & EU) | 2025 - 2034 |
|---|---|---|---|
| Rising Global Prevalence of STDs and Respiratory Virus | +2.1% | Asia-Pacific and North America | 2025 - 2030 |
| Decentralization of Healthcare Services | +1.9% | Emerging Economies (India, Brazil) | 2026 - 2034 |
| Government Funding for Pandemic Preparedness | +1.5% | G7 Nations | 2025 - 2028 |
Point Of Care Infectious Disease Testing Market Restraints Analysis
Despite robust growth, the market faces significant hurdles related to the high cost of sophisticated diagnostic instruments and the stringent regulatory approval pathways in various jurisdictions. The disparity between the cost of rapid tests and laboratory-based gold standards often limits adoption in price-sensitive markets. Additionally, concerns regarding the diagnostic accuracy and potential for user error in non-laboratory settings continue to pose challenges for widespread clinical acceptance and full-scale implementation in critical care scenarios.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Molecular POC Instruments | -1.4% | Low-to-Middle Income Countries | 2025 - 2034 |
| Stringent Regulatory and Compliance Hurdles | -1.1% | European Union (MDR/IVDR) | 2025 - 2027 |
| Limited Sensitivity Compared to Lab PCR | -0.8% | Global Clinical Settings | 2025 - 2030 |
Point Of Care Infectious Disease Testing Market Opportunities Analysis
The intersection of digital health and diagnostic hardware presents unprecedented opportunities for market expansion. The development of smartphone-connected diagnostic readers and AI-driven interpretation tools allows for sophisticated testing to be conducted by minimally trained personnel or patients themselves. Moreover, there is significant untapped potential in the development of multiplex panels for neglected tropical diseases and the integration of diagnostic platforms with cloud-based epidemiological tracking systems, which can provide real-time insights for public health agencies.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| AI-Integrated Diagnostic Platforms | +2.5% | Global (Developed Markets) | 2027 - 2034 |
| Expansion into Retail Pharmacy Clinics | +1.8% | United States and United Kingdom | 2025 - 2032 |
| Home-Based Infectious Disease Monitoring | +2.2% | China and Japan | 2026 - 2034 |
Point Of Care Infectious Disease Testing Market Challenges Impact Analysis
The primary challenge for the industry remains the maintenance of diagnostic quality and data security in increasingly decentralized environments. As testing moves further away from controlled laboratory settings, the risk of misinterpretation and fragmented data reporting increases. Furthermore, the volatility of supply chains for critical reagents and microelectronic components remains a significant threat to market stability, requiring manufacturers to develop more resilient logistical frameworks and diversified sourcing strategies.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Data Privacy and Cybersecurity Concerns | -0.9% | North America and Europe | 2025 - 2034 |
| Supply Chain Instability for Reagents | -1.2% | Global | 2025 - 2028 |
Point Of Care Infectious Disease Testing Market - Updated Report Scope
The scope of this comprehensive market analysis encompasses the global ecosystem of point-of-care diagnostics specifically targeted at infectious pathogens. It includes an in-depth evaluation of technological platforms ranging from traditional lateral flow assays to cutting-edge isothermal molecular amplification. The report provides granular data on revenue streams, volume trends, and competitive positioning across multiple clinical and non-clinical end-user segments. By analyzing historical data from 2020 through 2024 and projecting forward to 2034, this research offers a strategic roadmap for stakeholders navigating the complexities of the decentralized diagnostic landscape.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 20.4 Billion |
| Market Forecast in 2034 | USD 51.6 Billion |
| Growth Rate | 9.4% CAGR |
| Number of Pages | 256 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Danaher Corporation (Cepheid), Becton, Dickinson and Company (BD), QuidelOrtho Corporation, Siemens Healthineers AG, Thermo Fisher Scientific Inc., Bio-Rad Laboratories, Inc., bioMérieux SA, Meridian Bioscience, Inc., GenMark Diagnostics, Chembio Diagnostics, Inc., Trinity Biotech plc, OraSure Technologies, Inc., Sekisui Diagnostics, Hologic, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented by product, technology, application, and end-user to provide a granular view of growth drivers and competitive dynamics. The technology segment is currently undergoing the most significant shift, as isothermal nucleic acid amplification technology (NAAT) begins to challenge the dominance of lateral flow immunoassays due to its superior clinical utility in early infection detection. On an application basis, respiratory infections continue to hold the highest market share, though the sexually transmitted disease testing segment is witnessing rapid acceleration due to increased screening initiatives and the availability of discrete home-testing options.
- By Product: Consumables and Assay Kits dominate the revenue share due to high volume turnover and the recurring nature of diagnostic testing in acute care settings.
- By Technology: Molecular Diagnostics is the fastest-growing sub-segment, offering high sensitivity and specificity for complex pathogens.
- By Application: HIV and Hepatitis testing remain significant contributors to the market, particularly in high-prevalence regions where portable POC devices are essential for field testing.
- By End-User: The Physician Office and Urgent Care segment is expanding rapidly as healthcare delivery becomes increasingly decentralized.
Regional Highlights
- North America: The largest market globally, characterized by high healthcare expenditure and a robust regulatory framework that supports the rapid commercialization of innovative POC technologies.
- Europe: A mature market with strong growth in the molecular POC segment, driven by strict mandates for infectious disease surveillance and the implementation of the IVDR regulation.
- Asia-Pacific: The fastest-growing region, with China and India leading the demand due to large patient populations, rising investments in primary healthcare, and local manufacturing incentives.
- Latin America: Growth is primarily driven by the need for rapid diagnostics in managing tropical diseases such as Dengue and Zika, with Brazil being a key contributor.
- Middle East and Africa: Market development is focused on expanding access to HIV and Tuberculosis testing through international health partnerships and government-funded screening programs.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Point Of Care Infectious Disease Testing Market.- Abbott Laboratories
- F. Hoffmann-La Roche Ltd
- Danaher Corporation (Cepheid)
- Becton, Dickinson and Company (BD)
- QuidelOrtho Corporation
- Siemens Healthineers AG
- Thermo Fisher Scientific Inc.
- Bio-Rad Laboratories, Inc.
- bioMérieux SA
- Meridian Bioscience, Inc.
- GenMark Diagnostics
- Chembio Diagnostics, Inc.
- Trinity Biotech plc
- OraSure Technologies, Inc.
- Sekisui Diagnostics
- Hologic, Inc.
- Qiagen N.V.
- LumiraDx
- Mesa Biotech (Pfizer)
- Eiken Chemical Co., Ltd.
Frequently Asked Questions
What is the current market size and growth forecast for Point Of Care Infectious Disease Testing?
The market is estimated at USD 20.4 Billion in 2025 and is projected to reach USD 51.6 Billion by 2034, growing at a CAGR of 9.4% during the forecast period. This growth is driven by decentralization of healthcare and the rise of molecular diagnostic technologies.
Which technology is leading the Point Of Care Infectious Disease Testing market?
While Lateral Flow remains widely used due to its low cost, Molecular Diagnostics is the fastest-growing technology segment. Its ability to provide high sensitivity and specificity for viral and bacterial detection makes it the preferred choice for clinical decision-making in acute settings.
Who are the major companies operating in this market?
Key players include Abbott Laboratories, Roche, Danaher (Cepheid), Becton Dickinson, and QuidelOrtho. These companies dominate through extensive product portfolios, strategic acquisitions, and robust distribution networks across both developed and emerging markets.
What are the primary drivers for the Asia-Pacific region's rapid growth?
Growth in the APAC region is fueled by increasing healthcare infrastructure investment, rising awareness of early diagnosis, and high disease prevalence in countries like India and China. Additionally, the proliferation of retail clinics and community health centers is driving POC adoption.
What are the key challenges facing the POC infectious disease testing market?
Major challenges include the high cost of molecular testing platforms, complex regulatory approval processes (such as the EU's IVDR), and concerns regarding the diagnostic accuracy and data integration of tests performed outside traditional laboratory environments.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted