Downstream Processing Market
Downstream Processing Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_703594 | Published On : September 23, 2026 |
Format : 


 | Author : Erika Grotto
Downstream Processing Market Size
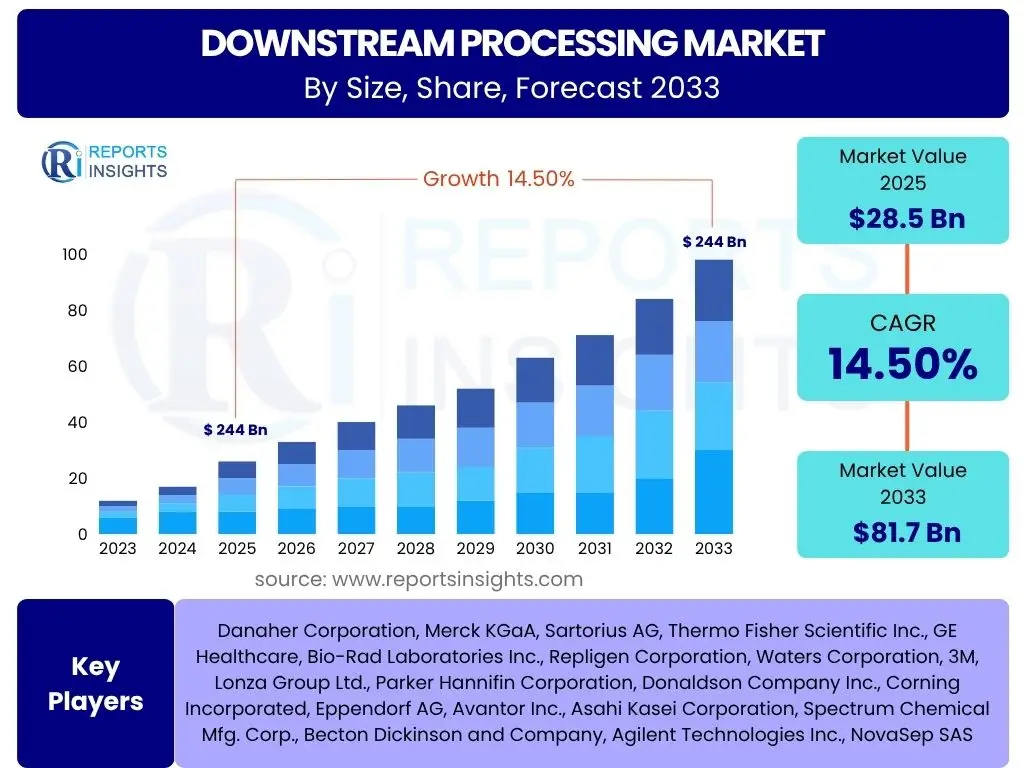
According to Reports Insights Consulting Pvt Ltd, The Downstream Processing Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 14.2% between 2026 and 2034. The market is estimated at USD 43.91 Billion in 2026 and is projected to reach USD 126.54 Billion by the end of the forecast period in 2034.
Key Downstream Processing Market Trends & Insights
The global downstream processing landscape is undergoing a paradigm shift driven by the transition from batch to continuous biomanufacturing and the widespread adoption of single-use technologies. Enterprise stakeholders are increasingly focusing on cost-reduction strategies and process intensification to manage the rising complexities of next-generation biologics, including cell and gene therapies. The integration of Process Analytical Technology (PAT) and automation is enabling real-time monitoring, ensuring higher purity levels and regulatory compliance while shortening time-to-market for critical therapeutics.
- Largest Region: North America remains the dominant market, holding over 35% of the global market share due to its robust biopharmaceutical infrastructure and high R&D investment.
- Fastest Growing Region: Asia Pacific is expected to exhibit the highest CAGR during the forecast period, fueled by the expansion of Contract Manufacturing Organizations (CMOs) in China and India.
- Leading Product Segment: Chromatography systems and resins constitute the largest segment, accounting for a significant portion of the revenue due to their indispensable role in high-resolution purification.
- Primary Application: Monoclonal Antibodies (mAbs) represent the leading application segment, driven by their increasing use in oncology and autoimmune disease treatments.
Key Takeaways Downstream Processing Market Size & Forecast
The downstream processing market is characterized by intense technological competition and a move toward modular, flexible manufacturing units. As the patent cliff approaches for several blockbuster biologics, the surge in biosimilar production is acting as a catalyst for market expansion. Investment in advanced filtration and purification techniques is becoming a strategic priority for biopharmaceutical companies aiming to improve yields and reduce the footprint of their manufacturing facilities.
- The global market value is set to nearly triple by 2034, reflecting the critical nature of purification in the bioproduction lifecycle.
- Purification techniques, particularly multi-modal chromatography, are seeing rapid adoption for complex protein separation.
- Single-use downstream systems are reducing sterilization costs and cross-contamination risks, making them a preferred choice for mid-scale production.
- The United States and Germany are the primary hubs for downstream technology innovation and equipment manufacturing.
Downstream Processing Market Drivers Analysis
The primary catalysts for the downstream processing market include the soaring demand for biopharmaceuticals and the global emphasis on personalized medicine. The increasing prevalence of chronic diseases has necessitated the large-scale production of biologics, which in turn requires sophisticated downstream infrastructure to ensure therapeutic efficacy and safety. Furthermore, government initiatives and funding for biotechnology research are providing the necessary capital for market players to innovate and scale their operations.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rise in Biologics and Biosimilars Demand | +4.2% | Global / European Union | 2025 - 2034 |
| Adoption of Single-Use Technologies (SUT) | +3.8% | North America / Asia Pacific | 2025 - 2030 |
| Expansion of CMO and CDMO Services | +3.1% | China / India / South Korea | 2026 - 2034 |
| Technological Advances in Chromatography | +2.5% | United States / Germany | 2025 - 2034 |
Downstream Processing Market Restraints Analysis
Despite robust growth, the market faces significant hurdles related to the high capital expenditure required for setting up advanced downstream processing lines. The complexity of regulatory approvals for new purification methods can also delay the implementation of innovative technologies. Additionally, the shortage of a highly skilled workforce capable of managing sophisticated automated bioprocessing systems remains a bottleneck for many organizations operating in emerging economies.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Chromatography Resins | -2.1% | Global | 2025 - 2034 |
| Stringent Regulatory Requirements | -1.8% | North America / Europe | Ongoing |
| Technical Challenges in Scaling Up | -1.5% | Emerging Markets | 2025 - 2028 |
Downstream Processing Market Opportunities Analysis
The emergence of cell and gene therapies presents an unprecedented opportunity for downstream processing vendors to develop specialized purification platforms. The shift toward continuous bioprocessing offers a route to significantly higher productivity and lower operational costs, providing a competitive edge to early adopters. Furthermore, the digitalization of the bioprocessing floor through AI and machine learning for predictive maintenance and process optimization is an untapped area with high growth potential.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of mRNA Vaccine Platforms | +3.5% | Global | 2025 - 2034 |
| Implementation of Continuous Bioprocessing | +2.9% | Europe / Japan | 2027 - 2034 |
| AI-Integrated Process Monitoring | +1.7% | United States / Israel | 2026 - 2034 |
Downstream Processing Market Challenges Impact Analysis
Supply chain vulnerabilities, as exposed by recent global disruptions, remain a critical challenge for the consistent availability of consumables like filters and resins. The high water and energy consumption associated with traditional downstream steps also poses environmental and sustainability challenges, forcing companies to rethink their green manufacturing strategies. Balancing the need for high-speed processing with the delicate nature of advanced biologics requires constant innovation in shear-sensitive separation techniques.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Instability for Consumables | -1.4% | Global | 2025 - 2027 |
| Environmental Sustainability Pressures | -1.1% | European Union | 2025 - 2034 |
| Complexities in Viral Clearance | -0.9% | Global | Ongoing |
Downstream Processing Market - Updated Report Scope
This report provides a granular analysis of the downstream processing market, covering the technological landscape, competitive dynamics, and regional growth vectors. It evaluates the shift from traditional stainless-steel infrastructure to flexible bioprocessing solutions. The scope encompasses detailed financial modeling and trend analysis for major products including chromatography systems, filters, centrifuges, and consumables, while segmenting the market by technique, application, and end-user profile.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 38.45 Billion |
| Market Forecast in 2034 | USD 126.54 Billion |
| Growth Rate | 14.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Danaher Corporation (Pall), Merck KGaA, Sartorius AG, Thermo Fisher Scientific Inc., GE Healthcare (Cytiva), Repligen Corporation, 3M Company, Corning Incorporated, Lonza Group AG, Boehringer Ingelheim, Agilent Technologies, Waters Corporation, Bio-Rad Laboratories, Eppendorf SE, Tosoh Corporation, Novasep, Kaneka Corporation, Asahi Kasei Corporation, Takara Bio Inc., Rentschler Biopharma SE |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The downstream processing market is segmented into several critical categories that reflect the technical requirements of modern biomanufacturing. The product segment is dominated by chromatography and filtration, which are essential for achieving the high levels of purity required for therapeutic proteins. Application-wise, monoclonal antibodies represent the largest revenue stream, although the cell and gene therapy segment is expected to witness the highest growth rate as these therapies move from clinical trials to commercialization. End-users such as CMOs are becoming increasingly vital as biopharma companies outsource production to leverage specialized downstream expertise.
- By Product: Includes Chromatography Systems (FPLC, HPLC), Resins (Ion Exchange, Affinity, Size Exclusion), Filters (Membrane, Depth, Tangential Flow), Centrifuges, and related consumables.
- By Technique: Covers the critical steps of Cell Disruption, Solid-Liquid Separation, Purification (Capture and Polishing), Viral Clearance, and Final Formulation.
- By Application: Specific focuses on Monoclonal Antibodies (mAbs), Vaccines (Inactivated, mRNA, Viral Vector), Recombinant Proteins, Hormones, and Nucleic Acids.
- By End-User: Divided into Biopharmaceutical & Biotechnology Enterprises, Contract Development and Manufacturing Organizations (CDMOs), and Research Laboratories.
Regional Highlights
Regional dynamics are shaped by the maturity of the healthcare sector and the level of investment in biotechnology. North America currently leads the market due to its high concentration of biopharmaceutical giants and an advanced regulatory framework that encourages innovation. Europe follows closely, with Germany and Switzerland being major hubs for biomanufacturing excellence. However, the Asia Pacific region is rapidly closing the gap, driven by lower manufacturing costs, favorable government policies, and a surging number of biosimilar approvals in China and Japan.
- North America: Market leader with high adoption of automated downstream systems and single-use technologies. The U.S. is the central hub for R&D.
- Europe: Strong emphasis on continuous bioprocessing and green manufacturing standards. Germany, France, and the UK are primary contributors.
- Asia Pacific: The fastest-growing region, characterized by massive infrastructure investment in bioparks and a growing domestic market for biologics.
- Latin America & MEA: Emerging markets focusing on local vaccine production and establishing basic bioprocessing capabilities to ensure regional drug security.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Downstream Processing Market.- Danaher Corporation (Pall Corporation)
- Merck KGaA
- Sartorius AG
- Thermo Fisher Scientific Inc.
- GE Healthcare (Cytiva)
- Repligen Corporation
- 3M Company
- Corning Incorporated
- Lonza Group AG
- Boehringer Ingelheim
- Agilent Technologies, Inc.
- Waters Corporation
- Bio-Rad Laboratories, Inc.
- Eppendorf SE
- Tosoh Corporation
- Novasep (Groupe Novasep)
- Kaneka Corporation
- Asahi Kasei Corporation
- Takara Bio Inc.
- Rentschler Biopharma SE
Frequently Asked Questions
What is the primary driver of the Downstream Processing Market growth?
The primary driver is the increasing global demand for biopharmaceuticals, particularly monoclonal antibodies and biosimilars, which require sophisticated purification and separation technologies to meet safety and efficacy standards.
Which product segment holds the largest share in the downstream processing market?
The chromatography segment, including systems and resins, holds the largest market share because it is the most critical and expensive step in the purification process for biologics.
How are single-use technologies impacting the market?
Single-use technologies are significantly reducing capital expenditure, minimizing cross-contamination risks, and decreasing the time required for cleaning and validation, thereby increasing overall facility flexibility.
Which region is expected to grow the fastest between 2025 and 2034?
The Asia Pacific region is expected to be the fastest-growing market due to the rapid expansion of CDMO services, supportive government initiatives, and an increasing focus on biosimilar development in countries like China and India.
What are the key challenges facing downstream processing companies?
Major challenges include the high cost of advanced chromatography resins, complex regulatory hurdles for new technologies, and the need for high-performance viral clearance steps to ensure product safety.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
