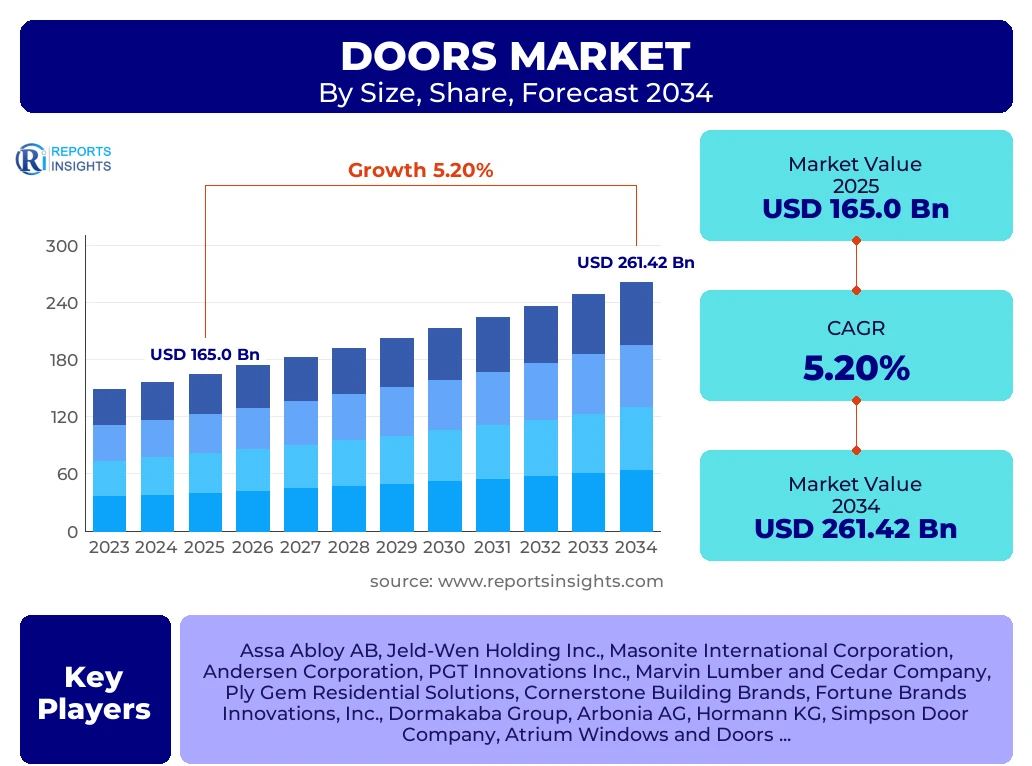
Doors Market
Doors Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711387 | Published On : October 30, 2026 |
Format : 


 | Author : Jonathan Sikka
Doors Market Size
According to Reports Insights Consulting Pvt Ltd, The Doors Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.2% between 2025 and 2034. The market is estimated at USD 173.58 Billion in 2026 and is projected to reach USD 261.42 Billion by the end of the forecast period in 2034.
Key Doors Market Trends & Insights
The global doors market is undergoing a significant transformation driven by the convergence of smart technology integration, sustainable building practices, and an increasing emphasis on high-performance security features. Stakeholders are observing a distinct shift toward eco-friendly materials such as fiberglass and engineered wood, which offer superior durability and thermal insulation compared to traditional options. Furthermore, the rise of smart home ecosystems has catalyzed the demand for automated entry systems, integrated sensors, and biometric access controls, positioning the door as a critical component of home security and energy management frameworks. Regional demand remains heavily influenced by urbanization rates in Asia-Pacific and renovation activities across North America and Europe.
- Largest Region: Asia-Pacific remains the dominant market shareholder, accounting for over 40% of the global market due to massive infrastructure projects and expanding residential sectors in China and India.
- Fastest Growing Region: Middle East and Africa (MEA) is projected to exhibit the highest CAGR as a result of luxury hospitality developments and smart city initiatives in the GCC countries.
- Largest Segment by Share: The Residential segment continues to hold the largest market share, fueled by the global housing demand and the ongoing trend of home modernization.
- Material Trend: Plastic and uPVC doors are gaining rapid traction in the commercial sector due to their cost-effectiveness and low maintenance requirements.
- Technology Integration: The adoption of Internet of Things (IoT) in door hardware is a leading trend, with smart locks and remote monitoring becoming standard in new premium constructions.
Key Takeaways Doors Market Size & Forecast
The Doors market is characterized by steady growth trajectories across both emerging and developed economies. Analysts indicate that the forecast period between 2025 and 2034 will be defined by a transition from basic functional entryways to multifunctional architectural elements that prioritize aesthetic appeal and energy efficiency. The expansion of the global construction industry, particularly in the multi-family residential sector, provides a robust foundation for market growth. Additionally, stringent government regulations regarding carbon emissions and building energy codes are forcing manufacturers to innovate in thermal break technology and sustainable sourcing, ensuring the market evolves in alignment with global climate goals.
- Market Valuation: The total market value is expected to surpass the USD 260 billion mark by 2034, reflecting a stable and resilient growth environment.
- Leading Country: China is the single largest consumer and producer of doors globally, driven by industrialization and a vast domestic construction pipeline.
- High-Growth Material: Composite doors are expected to see significant volume growth due to their ability to mimic wood aesthetics while providing the strength of steel.
- Infrastructure Impact: Rapid investment in commercial infrastructure, including hospitals, airports, and educational institutions, is boosting the demand for specialized fire-rated and acoustic doors.
- Sustainability Focus: Energy-efficient doors with high R-values are becoming a prerequisite in the European and North American renovation markets to meet strict green building certifications.
Doors Market Drivers Analysis
The primary catalysts for the doors market include the rapid pace of global urbanization and the subsequent need for residential housing. As more people migrate to urban centers, the demand for high-density living solutions increases, directly impacting the volume of doors required for new builds. Furthermore, the global push for energy-efficient buildings is a major driver; doors are no longer seen as simple barriers but as critical components of a building’s thermal envelope. Technological advancements in manufacturing, such as 3D printing and automated CNC machining, are also lowering production costs and allowing for greater customization, further stimulating market demand among high-end consumers and commercial developers.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rapid Urbanization and Housing Demand | +1.8% | Global (High in India/China) | 2025 - 2034 |
| Strict Energy Efficiency Regulations | +1.2% | North America and Europe | 2025 - 2030 |
| Integration of Smart Home Technologies | +0.9% | United States, Germany, Japan | 2026 - 2034 |
| Growth in Tourism and Hospitality Infrastructure | +0.7% | Middle East (UAE, Saudi Arabia) | 2025 - 2032 |
| Rise in Renovation and Home Improvement Projects | +0.6% | Europe and North America | 2025 - 2034 |
Doors Market Restraints Analysis
Despite the positive growth outlook, the market faces significant headwinds from the volatility of raw material prices. The cost of timber, steel, and aluminum is subject to global supply chain fluctuations and geopolitical tensions, which can erode profit margins for manufacturers. Additionally, the labor-intensive nature of door installation and a shortage of skilled tradespeople in developed regions act as bottlenecks for market expansion. Environmental regulations regarding the sourcing of certain hardwoods also pose a challenge, requiring companies to invest heavily in certification and sustainable procurement processes, which may increase the final price for consumers.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Volatility (Steel/Wood) | -0.8% | Global | 2025 - 2028 |
| Shortage of Skilled Installation Labor | -0.5% | United Kingdom, USA, Germany | 2025 - 2034 |
| Strict Environmental Hardwood Regulations | -0.4% | Brazil, Indonesia, Europe | 2026 - 2034 |
Doors Market Opportunities Analysis
The increasing focus on sustainable construction presents a massive opportunity for the development of bio-based materials and circular economy models within the door industry. Manufacturers can capitalize on the demand for LEED and BREEAM certified products by using recycled metals and responsibly sourced wood fibers. Moreover, the aging population in developed countries is creating a niche market for accessibility-focused products, such as wide-clearance automated sliding doors and low-threshold entryways. The digital transformation of the sales process, including Virtual Reality (VR) showrooms and Augmented Reality (AR) apps that allow customers to visualize door designs in their own homes, also offers significant potential for enhancing retail and direct-to-consumer sales channels.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of Recycled and Bio-Based Materials | +1.5% | European Union, Scandinavia | 2026 - 2034 |
| Focus on Universal Design and Accessibility | +1.1% | Japan, USA, Western Europe | 2025 - 2034 |
| Expansion in E-commerce and AR Visualization | +0.8% | Global | 2025 - 2030 |
| Infrastructure Modernization in Emerging Markets | +1.4% | Southeast Asia, Latin America | 2027 - 2034 |
Doors Market Challenges Impact Analysis
Interoperability and cybersecurity emerge as critical challenges as doors become increasingly integrated into smart home networks. Ensuring that electronic locks and sensors are compatible with various home automation platforms while remaining secure against hacking attempts is a significant hurdle for manufacturers. Furthermore, the intense competition from local, low-cost manufacturers in fragmented markets often leads to price wars, making it difficult for premium brands to maintain market share without constant innovation. The logistical complexity of transporting large, fragile items like high-end glass or heavy steel doors across long distances also adds to the operational costs and carbon footprint of the industry.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity Risks in Smart Entry Systems | -0.6% | Global | 2025 - 2034 |
| Intense Competition from Local Manufacturers | -0.5% | India, Southeast Asia | 2025 - 2034 |
| Logistical and Transportation Costs | -0.4% | North America, Australia | 2025 - 2029 |
Doors Market - Updated Report Scope
This report provides a comprehensive examination of the global doors market, offering detailed quantitative and qualitative analysis across all major geographic regions and product segments. The scope encompasses an in-depth study of market drivers, restraints, and technological shifts, providing stakeholders with actionable insights to navigate the evolving landscape of architectural entryways and internal partitions. Particular focus is given to the impact of smart technology, sustainability trends, and the changing regulatory environment on market growth through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 165.0 Billion |
| Market Forecast in 2034 | USD 261.42 Billion |
| Growth Rate | 5.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Assa Abloy AB, Jeld-Wen Holding Inc., Masonite International Corporation, Andersen Corporation, PGT Innovations Inc., Marvin Lumber and Cedar Company, Ply Gem Residential Solutions, Cornerstone Building Brands, Fortune Brands Innovations, Inc., Dormakaba Group, Arbonia AG, Hormann KG, Simpson Door Company, Atrium Windows and Doors, Pella Corporation, Masco Corporation, Fancy Doors and Mouldings, VKR Holding A/S |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on material, mechanism, application, and end-use, allowing for a granular understanding of specific growth pockets. Currently, the wood segment leads in residential interiors due to its aesthetic warmth and versatility, while metal doors, specifically steel, dominate the industrial and security-focused commercial sectors. The sliding door mechanism is witnessing a surge in popularity in modern architecture, as it facilitates open-plan living and maximizes space in urban apartments. Additionally, the renovation segment is growing rapidly in mature economies as homeowners seek to improve property value and energy efficiency by replacing outdated entry systems.
- By Material:
- Wood (Hardwood, Softwood, Engineered Wood)
- Metal (Steel, Aluminum, Bronze)
- Glass (Tempered, Laminated, Insulated)
- Plastic/uPVC (Standard, Reinforced)
- Composite (Fiberglass, Wood-Plastic Composite)
- By Mechanism:
- Swinging (Left-handed, Right-handed)
- Sliding (Bypass, Pocket, Barn Doors)
- Folding (Bifold, Accordion)
- Revolving (Manual, Automatic)
- Overhead (Sectional, Rolling)
- By Application:
- Residential (New Build, Remodeling)
- Commercial (Healthcare, Hospitality, Retail, Corporate Offices)
- Industrial (Factory Floors, Cold Storage, Logistics Hubs)
- By End-Use:
- New Construction
- Renovation/Aftermarket
Regional Highlights
The regional landscape of the doors market is diverse, with Asia-Pacific serving as the engine of volume growth. In contrast, North America and Europe are centers for high-value technological innovation. The United States market is currently bolstered by a strong residential replacement sector and a shift toward impact-resistant doors in hurricane-prone regions. Germany and the Nordic countries are leading the way in "Passive House" standards, driving the demand for triple-glazed and highly insulated door systems. In emerging markets like India and Vietnam, government-led affordable housing schemes are significantly boosting the demand for cost-effective wood and uPVC solutions.
- Asia-Pacific: The largest market globally, with China leading in both production and consumption. The region is the fastest-growing market for uPVC and metal doors due to commercial infrastructure expansion.
- North America: A mature market characterized by high demand for premium materials and smart locks. The US residential renovation market remains a key contributor to stable revenues.
- Europe: Driven by strict environmental regulations and the European Green Deal, there is a substantial shift toward high-performance, energy-efficient entry systems.
- Middle East & Africa: Rapidly growing due to luxury tourism developments and the rise of smart cities, creating high demand for specialized architectural glass and metal doors.
- Latin America: Expected to show steady growth as economic stabilization leads to renewed investment in urban residential projects, particularly in Brazil and Mexico.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Doors Market.- Assa Abloy AB
- Jeld-Wen Holding Inc.
- Masonite International Corporation
- Andersen Corporation
- PGT Innovations Inc.
- Marvin Lumber and Cedar Company
- Ply Gem Residential Solutions
- Cornerstone Building Brands
- Fortune Brands Innovations, Inc.
- Dormakaba Group
- Arbonia AG
- Hormann KG
- Simpson Door Company
- Atrium Windows and Doors
- Pella Corporation
- Masco Corporation
- Fancy Doors and Mouldings
- VKR Holding A/S
- YKK AP Inc.
- Reynaers Aluminium
Frequently Asked Questions
What is the current global market size for doors and what is the growth forecast?
The Doors Market is valued at USD 165.0 Billion in 2025 and is projected to reach approximately USD 261.42 Billion by 2034, growing at a steady CAGR of 5.2% during the forecast period.
Which material is expected to witness the highest growth in the doors market?
While wood remains dominant in residential applications, composite materials (fiberglass) and uPVC are expected to see the fastest growth due to their superior durability, low maintenance, and excellent thermal insulation properties.
How is smart technology impacting the doors market trends?
Smart technology is transforming doors from static barriers into active security nodes. Key trends include the integration of biometric scanners, IoT-connected locks, and remote access monitoring, primarily in the premium residential and commercial sectors.
Which region currently leads the doors market in terms of revenue?
Asia-Pacific is the leading region, holding over 40% of the market share. This dominance is driven by massive urbanization, government-sponsored housing projects, and a robust manufacturing base in countries like China and India.
What are the primary drivers for the doors market in North America and Europe?
In these regions, market growth is primarily driven by strict energy-efficiency regulations (green building codes) and a high volume of renovation and home improvement projects aimed at increasing property value and lowering utility costs.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
