Dipeptide Peptidase 4 Inhibitors Market
Dipeptide Peptidase 4 Inhibitors Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711288 | Published On : October 24, 2026 |
Format : 


 | Author : Erika Grotto
Dipeptide Peptidase 4 Inhibitors Market Size
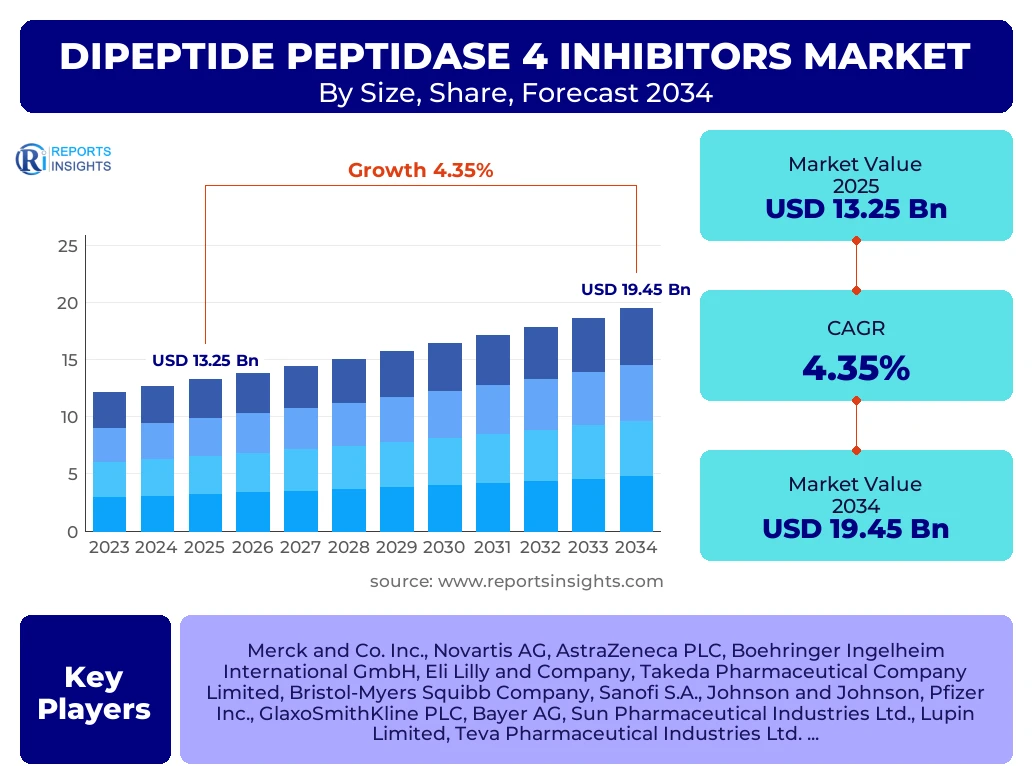
According to Reports Insights Consulting Pvt Ltd, The Dipeptide Peptidase 4 Inhibitors Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 4.35% between 2025 and 2034. The market is estimated at USD 13.82 Billion in 2026 and is projected to reach USD 19.45 Billion by the end of the forecast period in 2034.
Key Dipeptide Peptidase 4 Inhibitors Market Trends & Insights
The global landscape for Dipeptide Peptidase 4 (DPP-4) inhibitors is currently undergoing a significant transition characterized by the shift toward combination therapies and the increasing penetration of generic alternatives following patent expirations of first-generation molecules. Market intelligence suggests that clinical preference is leaning heavily toward fixed-dose combinations (FDCs), particularly those pairing DPP-4 inhibitors with metformin or SGLT2 inhibitors, to improve patient adherence and achieve synergistic glycemic control. Regional analysis indicates a surge in demand across emerging economies due to improving healthcare infrastructure and rising diagnostic rates for Type 2 diabetes. Furthermore, competitive benchmarking reveals a focus on long-term cardiovascular safety data, which remains a primary differentiator for established brands in a crowded therapeutic space.
- North America remains the largest regional market due to high healthcare spending and a significant prevalence of metabolic disorders.
- The Asia-Pacific region is the fastest-growing market, driven by massive diabetic populations in China and India and rising disposable incomes.
- Sitagliptin continues to be the largest product segment in terms of market share, although its dominance is being challenged by generic entries.
- The Retail Pharmacy segment holds the largest share of distribution, supported by the chronic nature of diabetes management requiring long-term medication.
- Increasing integration of digital health monitoring with pharmaceutical prescriptions is a notable trend affecting patient outcomes and market dynamics.
Key Takeaways Dipeptide Peptidase 4 Inhibitors Market Size & Forecast
The Dipeptide Peptidase 4 Inhibitors market is poised for steady growth through 2034, underpinned by the global diabetes epidemic and the favorable safety profile of these agents compared to traditional sulfonylureas. Market forecasts indicate that while newer drug classes like GLP-1 receptor agonists are capturing headlines, DPP-4 inhibitors maintain a critical role as second-line or third-line oral therapies due to their weight neutrality and low risk of hypoglycemia. Strategic focus is shifting toward the development of more potent, once-weekly formulations and the optimization of supply chains in high-growth regions like Southeast Asia and Latin America to capture untapped patient pools. The forecast period will likely see a balance between the volume growth of generics and the value maintenance of high-efficacy combination brands.
- The United States is the leading country market, characterized by advanced therapeutic adoption and robust reimbursement frameworks.
- Combination therapies are projected to outpace monotherapy growth rates as clinical guidelines increasingly favor early intensive glycemic management.
- Type 2 Diabetes remains the primary application segment, with no significant off-label uses currently impacting market valuations.
- The patent cliff for major blockbusters like Januvia is a pivotal factor driving market volume while pressuring overall revenue values.
- Strategic collaborations between multinational pharmaceutical firms and local manufacturers in APAC are essential for navigating regulatory hurdles and pricing sensitivities.
Dipeptide Peptidase 4 Inhibitors Market Drivers Analysis
The primary catalyst for the Dipeptide Peptidase 4 Inhibitors market is the escalating global prevalence of Type 2 Diabetes Mellitus (T2DM), which has reached pandemic proportions according to the International Diabetes Federation. As sedentary lifestyles and obesity rates climb, the patient pool requiring long-term glycemic management expands, creating a sustained demand for oral antidiabetic agents. DPP-4 inhibitors are particularly favored by clinicians for their oral bioavailability, weight neutrality, and minimal risk of hypoglycemia, making them an ideal choice for the growing geriatric population who are more susceptible to the adverse effects of older treatments.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Global Prevalence of Type 2 Diabetes | +1.5% | Global (High in India & China) | 2025 - 2034 |
| Preference for Oral Combination Therapies | +1.2% | North America and Europe | 2026 - 2030 |
| Growth in Geriatric Population | +0.9% | Japan, Germany, and USA | 2025 - 2034 |
| Expansion of Healthcare Access in Emerging Markets | +0.75% | Brazil, Mexico, and ASEAN | 2027 - 2034 |
Dipeptide Peptidase 4 Inhibitors Market Restraints Analysis
A significant restraint facing the market is the intensifying competition from newer drug classes, specifically SGLT2 inhibitors and GLP-1 receptor agonists, which have demonstrated superior cardiovascular and renal benefits in large-scale clinical trials. Additionally, the impending patent expirations for several key molecules will lead to an influx of low-cost generics, which, while beneficial for patient access, significantly erodes the revenue potential for brand-name manufacturers. Regulatory scrutiny regarding rare but serious side effects, such as potential links to pancreatitis or joint pain, also necessitates ongoing monitoring and can dampen prescription growth in highly regulated markets.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Competition from GLP-1 and SGLT2 Classes | -1.1% | Global | 2025 - 2034 |
| Patent Expirations and Generic Erosion | -1.4% | USA and EU5 Countries | 2025 - 2028 |
| Stringent Drug Pricing Policies | -0.6% | European Union | 2025 - 2034 |
Dipeptide Peptidase 4 Inhibitors Market Opportunities Analysis
The market presents substantial opportunities in the development of novel drug delivery systems and fixed-dose combinations that address comorbidities such as hypertension and dyslipidemia alongside diabetes. There is also significant potential in targeting undiagnosed patient populations in low-and-middle-income countries through philanthropic partnerships and tiered pricing models. Furthermore, the integration of real-world evidence (RWE) to demonstrate the long-term cost-effectiveness of DPP-4 inhibitors in reducing hospitalizations could influence payer decisions and secure favorable formulary positions in value-based healthcare systems.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Fixed-Dose Combinations (FDCs) | +1.3% | Asia-Pacific and Latin America | 2026 - 2034 |
| Expansion into Rural Healthcare Markets | +0.8% | India and Sub-Saharan Africa | 2028 - 2034 |
| Use of Real-World Evidence for Market Access | +0.5% | United Kingdom and Canada | 2025 - 2030 |
Dipeptide Peptidase 4 Inhibitors Market Challenges Impact Analysis
One of the primary challenges is maintaining manufacturing quality and supply chain resilience amidst fluctuating global trade dynamics and raw material costs. Furthermore, the lack of standardized clinical guidelines across different regions can lead to inconsistent prescribing patterns, complicating global marketing strategies for pharmaceutical companies. The high cost associated with conducting post-marketing surveillance and required cardiovascular outcome trials (CVOTs) also poses a financial challenge for smaller players attempting to enter the market with biosimilars or follow-on biologics.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Clinical Trials for New Formulations | -0.7% | Global | 2025 - 2034 |
| Supply Chain Disruptions in Active Ingredients | -0.4% | Global | 2025 - 2027 |
| Variability in Regional Regulatory Approvals | -0.5% | Middle East and Africa | 2025 - 2034 |
Dipeptide Peptidase 4 Inhibitors Market - Updated Report Scope
This report provides a comprehensive analysis of the global Dipeptide Peptidase 4 Inhibitors market, covering historical trends from 2020 to 2024 and providing a robust forecast for the period 2026-2034. It evaluates the impact of pharmacological advancements, patent landscapes, and the shifting epidemiological profile of metabolic diseases on market growth. The scope includes a detailed breakdown of drug types, combination therapies, and distribution channels across six major geographic regions, offering strategic insights for stakeholders ranging from pharmaceutical manufacturers to institutional investors.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 13.25 Billion |
| Market Forecast in 2034 | USD 19.45 Billion |
| Growth Rate | 4.35% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Merck and Co. Inc., Novartis AG, AstraZeneca PLC, Boehringer Ingelheim International GmbH, Eli Lilly and Company, Takeda Pharmaceutical Company Limited, Bristol-Myers Squibb Company, Sanofi S.A., Johnson and Johnson, Pfizer Inc., GlaxoSmithKline PLC, Bayer AG, Sun Pharmaceutical Industries Ltd., Lupin Limited, Teva Pharmaceutical Industries Ltd., Mylan N.V. (Viatris), Glenmark Pharmaceuticals, Servier Laboratories |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Dipeptide Peptidase 4 Inhibitors market reflects the diverse clinical needs and purchasing behaviors of the global diabetic population. Drug type segmentation remains the most critical, as different molecules offer varying degrees of metabolic stability and renal safety, with Sitagliptin maintaining a dominant position due to its early entry and extensive clinical history. The formulation segment is increasingly pivoting toward combination therapies, which address the complex pathophysiology of diabetes more effectively than monotherapies alone. Furthermore, the distribution channel analysis highlights the growing importance of online pharmacies, which offer convenience and price transparency for patients managing chronic conditions.
- By Drug Type: Sitagliptin, Vildagliptin, Saxagliptin, Linagliptin, Alogliptin, Teneligliptin, Anagliptin, Gemigliptin.
- By Formulation: Monotherapy (Single active ingredient) and Combination Therapy (FDCs with Metformin, SGLT2, or Pioglitazone).
- By Distribution Channel: Hospital Pharmacies (In-patient prescriptions), Retail Pharmacies (Mainstream community pharmacies), Online Pharmacies (E-commerce and home delivery).
- By Application: Type 2 Diabetes Mellitus Management.
Regional Highlights
- North America: The largest market by revenue, driven by high per-capita healthcare expenditure, a well-established reimbursement system, and early adoption of combination therapies. The United States accounts for the majority share of this region.
- Asia-Pacific: The fastest-growing region during the forecast period. The massive diabetic populations in China and India, coupled with government initiatives to improve healthcare affordability, are propelling market demand. Increasing local production of generics in India is also a key factor.
- Europe: A mature market characterized by stringent regulatory environments and a focus on cost-containment. Growth is driven by the rising geriatric population and a high prevalence of obesity-related diabetes in Western Europe.
- Latin America: Showing significant potential due to the modernization of healthcare infrastructure in countries like Brazil and Mexico, though economic volatility remains a challenge for market stability.
- Middle East and Africa: Growth is supported by increasing awareness programs and the high prevalence of metabolic syndrome in Gulf Cooperation Council (GCC) countries.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Dipeptide Peptidase 4 Inhibitors Market.- Merck and Co. Inc.
- Novartis AG
- AstraZeneca PLC
- Boehringer Ingelheim International GmbH
- Eli Lilly and Company
- Takeda Pharmaceutical Company Limited
- Bristol-Myers Squibb Company
- Sanofi S.A.
- Johnson and Johnson
- Pfizer Inc.
- GlaxoSmithKline PLC
- Bayer AG
- Sun Pharmaceutical Industries Ltd.
- Lupin Limited
- Teva Pharmaceutical Industries Ltd.
- Mylan N.V. (Viatris)
- Glenmark Pharmaceuticals
- Servier Laboratories
- Mitsubishi Tanabe Pharma Corporation
- Kyowa Kirin Co. Ltd.
Frequently Asked Questions
What is the current market size and forecast growth for DPP-4 inhibitors?
The global DPP-4 inhibitors market is valued at approximately USD 13.25 Billion in 2025 and is expected to reach USD 19.45 Billion by 2034, growing at a CAGR of 4.35%. Growth is driven by the increasing incidence of Type 2 diabetes and the clinical safety profile of these drugs.
Which drug type currently dominates the Dipeptide Peptidase 4 Inhibitors market?
Sitagliptin remains the market leader due to its established brand recognition (Januvia) and extensive safety data. However, Linagliptin and Vildagliptin also hold significant market shares, especially in specific regional markets like Europe and Asia-Pacific.
How is the rise of SGLT2 inhibitors and GLP-1 agonists impacting this market?
While SGLT2 and GLP-1 drugs are gaining market share due to their weight loss and cardiovascular benefits, DPP-4 inhibitors continue to be a staple therapy because they are oral, generally well-tolerated, and have lower costs, particularly as more generics become available.
What are the primary distribution channels for these medications?
Retail pharmacies are the primary channel for DPP-4 inhibitors, as they serve the long-term, out-patient needs of diabetic patients. Online pharmacies are the fastest-growing channel, offering convenience and cost savings for chronic medication management.
Which region offers the most significant growth opportunities for pharmaceutical companies?
The Asia-Pacific region offers the highest growth potential due to its large and aging population, rising rates of obesity, and improving healthcare infrastructure. Countries like China, India, and Japan are central to the expansion strategies of major pharmaceutical players.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
