General Surgery Devices Market
General Surgery Devices Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711048 | Published On : October 01, 2026 |
Format : 


 | Author : Erika Grotto
General Surgery Devices Market Size
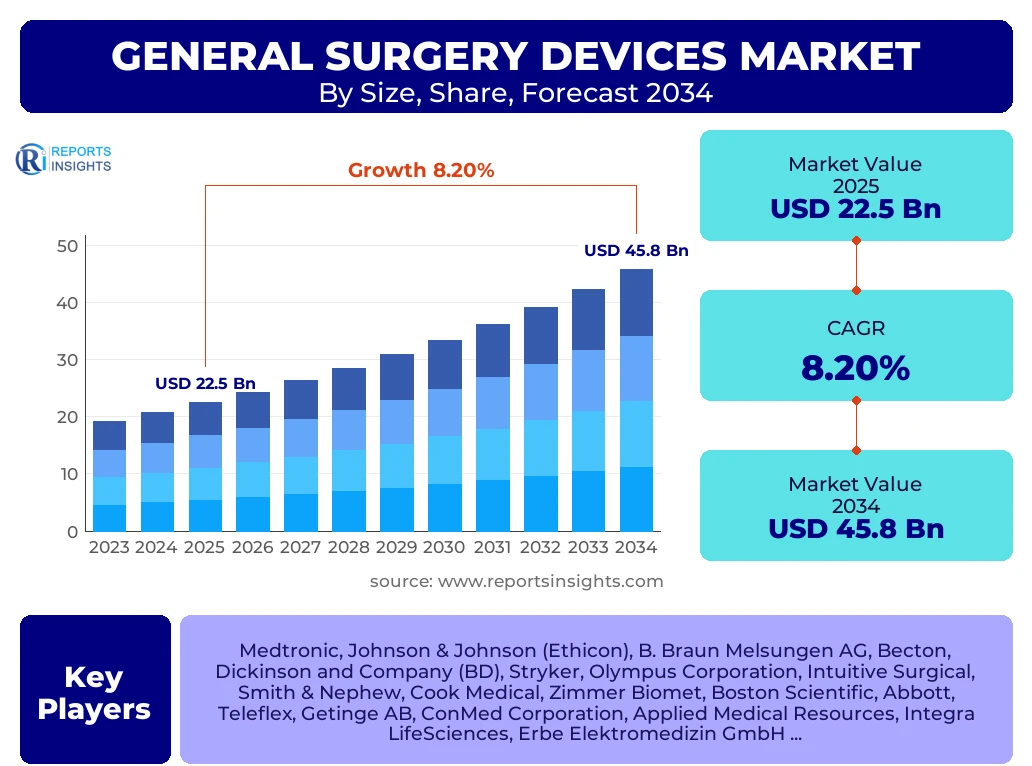
According to Reports Insights Consulting Pvt Ltd, The General Surgery Devices Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.2% between 2026 and 2034. The market is estimated at USD 22.5 Billion in 2025 and is projected to reach USD 45.8 Billion by the end of the forecast period in 2034.
Key General Surgery Devices Market Trends & Insights
The global landscape for general surgery devices is undergoing a significant transformation, driven by the convergence of digital technology and traditional surgical methodologies. Current trends indicate a decisive shift toward minimally invasive procedures, which are prioritized by both healthcare providers and patients due to reduced recovery times, lower infection risks, and improved aesthetic outcomes. This transition is further supported by advancements in high-definition imaging and the integration of artificial intelligence (AI) within surgical workflows, providing surgeons with real-time diagnostic support and predictive intraoperative data.
Furthermore, the market is witnessing an evolution in business models, moving from simple product sales to value-based care partnerships. Manufacturers are increasingly focusing on the development of smart surgical instruments that offer integrated sensing and feedback mechanisms. This evolution is particularly evident in the rapid adoption of robotic-assisted surgery platforms, which are no longer confined to academic medical centers but are becoming a standard of care in large-scale community hospitals. Competitive benchmarking reveals that companies emphasizing sustainable procurement practices and the development of cost-effective, high-performance disposable tools are gaining substantial market share in emerging economies.
- Largest Region: North America remains the dominant region, holding over 40% of the total market share due to its advanced healthcare infrastructure and high adoption of robotic systems.
- Fastest Growing Region: Asia-Pacific is expected to experience the highest CAGR during the forecast period, fueled by healthcare infrastructure modernization in China and India.
- Dominant Product Segment: Handheld surgical instruments continue to hold the largest volume share, while energy-based surgical devices are the fastest-growing segment by value.
- Primary End-User: Hospitals remain the leading end-user, though Ambulatory Surgical Centers (ASCs) are the fastest-growing category due to the global shift toward outpatient care.
Key Takeaways General Surgery Devices Market Size & Forecast
The General Surgery Devices market is characterized by a robust growth trajectory, sustained by the increasing prevalence of chronic diseases requiring surgical intervention and the global aging population. As the volume of surgeries increases, there is a parallel demand for precision-engineered tools that minimize procedural errors and optimize clinical outcomes. Market forecasts suggest that the integration of digital health and Internet of Medical Things (IoMT) will become a standard feature in surgical device portfolios by 2034.
- Market Valuation: The total market value is anticipated to nearly double by 2034, reflecting the heavy investment in automated and robotic-assisted surgical solutions.
- Leading Countries: The United States, Germany, and Japan are the primary contributors to technological innovation, while China is becoming the largest manufacturing hub and a critical consumer market.
- Technological Focus: Energy-based devices, including electrosurgical and ultrasonic instruments, are critical drivers of market value as they offer superior precision in tissue sealing and dissection.
- Regulatory Impact: Tightening MDR (Medical Device Regulation) standards in Europe and evolving FDA pathways in the United States are influencing product launch timelines and R&D strategies.
General Surgery Devices Market Drivers Analysis
The primary growth engines of the general surgery devices market include the global rise in geriatric demographics, the surge in lifestyle-related chronic conditions, and a strong preference for minimally invasive surgical techniques. These factors collectively push healthcare facilities to upgrade their existing surgical suites with advanced instrumentation.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Surge in Robotic-Assisted Surgery Adoption | +2.8% | Global (Primarily US and EU) | 2025 - 2034 |
| Rising Geriatric Population and Surgical Volume | +1.5% | Japan, Western Europe | 2025 - 2030 |
| Expansion of Ambulatory Surgical Centers (ASCs) | +2.1% | North America, India, Brazil | 2026 - 2034 |
General Surgery Devices Market Restraints Analysis
Despite strong growth, the market faces hurdles such as the high capital expenditure required for advanced robotic platforms and the increasing scrutiny over the environmental impact of single-use surgical disposables. Additionally, budgetary constraints in public healthcare sectors can delay procurement cycles for high-end technology.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Advanced Surgical Robotics | -1.2% | Emerging Economies (SEA, LATAM) | 2025 - 2028 |
| Stringent Regulatory Approval Procedures | -0.8% | European Union (MDR Compliance) | 2025 - 2034 |
General Surgery Devices Market Opportunities Analysis
Significant opportunities lie in the development of portable and handheld smart surgical tools designed for mid-tier hospitals and developing regions. Moreover, the integration of 5G and tele-surgery capabilities presents a frontier for companies to expand surgical expertise into remote areas, creating entirely new service-based revenue streams.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| AI-Integrated Surgical Navigation Systems | +3.2% | Global | 2027 - 2034 |
| Demand for Disposable Instruments in Emerging Markets | +1.9% | China, India, Southeast Asia | 2025 - 2034 |
General Surgery Devices Market Challenges Impact Analysis
Supply chain resilience remains a critical challenge, especially for electronic components used in energy-based devices. Furthermore, the competitive landscape is intensifying as local manufacturers in Asia offer high-quality alternatives at lower price points, challenging the dominance of traditional Western incumbents.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity Threats in Connected Surgical Suites | -0.5% | Developed Economies | 2026 - 2034 |
| Price Erosion due to Local Competition | -1.0% | APAC, MEA | 2025 - 2030 |
General Surgery Devices Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the global general surgery devices ecosystem, including manual instruments, energy-based systems, and surgical robotics. It evaluates technological trends, regulatory landscapes, and competitive dynamics across five major geographical regions. The report provides quantitative data on market size and CAGRs, alongside qualitative insights into the strategic maneuvers of key industry players and the impact of macroeconomic factors on healthcare spending.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 22.5 Billion |
| Market Forecast in 2034 | USD 45.8 Billion |
| Growth Rate | 8.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Medtronic, Johnson & Johnson (Ethicon), B. Braun Melsungen AG, Becton, Dickinson and Company (BD), Stryker, Olympus Corporation, Intuitive Surgical, Smith & Nephew, Cook Medical, Zimmer Biomet, Boston Scientific, Abbott, Teleflex, Getinge AB, ConMed Corporation, Applied Medical Resources, Integra LifeSciences, Erbe Elektromedizin GmbH, Richard Wolf GmbH, KLS Martin Group |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The general surgery devices market is segmented primarily by product type, application, and end-user. Product segmentation is the most critical as it defines the technological tier of the market, ranging from traditional manual tools to sophisticated robotic platforms. Handheld instruments represent the largest volume share, serving as the foundational tools for every surgical suite. However, the energy-based surgical devices segment is witnessing the most rapid innovation, with advancements in bipolar electrosurgery and harmonic scalpels providing unprecedented precision in tissue management.
Application-based segmentation reveals that gastrointestinal and cardiovascular surgeries are the largest revenue contributors due to the high volume of procedures and the complexity of the instruments required. End-user analysis shows a significant shift from traditional inpatient hospital settings to Ambulatory Surgical Centers (ASCs). This shift is driven by the global push for healthcare cost containment and the clinical preference for minimally invasive techniques that allow for same-day discharge. Specialty clinics are also emerging as a niche but profitable segment for high-end aesthetic and orthopedic surgical devices.
- By Product: Handheld Instruments, Energy-based Devices, Sutures & Staplers, Robotic Systems, Surgical Imaging.
- By Application: Gastrointestinal, Cardiovascular, Gynecological, Orthopedic, Urological, Plastic & Reconstructive.
- By End-User: Hospitals (Large & Medium), Ambulatory Surgical Centers, Specialized Surgical Clinics.
Regional Highlights
North America currently holds the largest market share, approximately 42%, driven by the presence of major industry players, high healthcare expenditure, and a mature market for robotic-assisted surgery. The United States is the primary hub for surgical device innovation, with a regulatory environment that supports the rapid commercialization of advanced technologies. In Europe, Germany and France lead the market, with a strong focus on high-quality manual instruments and energy-based systems, though growth is slightly tempered by stringent MDR compliance requirements.
The Asia-Pacific region is identified as the fastest-growing market, with a projected CAGR exceeding 9.5%. This growth is concentrated in China and India, where government initiatives to upgrade medical facilities and a rising middle class with better access to healthcare are creating massive demand. Japan remains a high-value market for sophisticated surgical electronics. Latin America and the MEA region are expected to show steady growth, driven by medical tourism in countries like Brazil, Mexico, and the UAE, where investment in state-of-the-art surgical centers is on the rise.
- North America: Largest market share, leading in robotic surgery and advanced imaging adoption.
- Asia-Pacific: Highest growth rate, driven by healthcare infrastructure expansion in China and India.
- Europe: Key center for high-precision manual and electrosurgical instruments.
- Latin America: Growing demand for cost-effective surgical tools and cosmetic surgery devices.
- Middle East & Africa: Emerging market for advanced surgical platforms in private healthcare hubs.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the General Surgery Devices Market.- Medtronic
- Johnson & Johnson (Ethicon)
- B. Braun Melsungen AG
- Becton, Dickinson and Company (BD)
- Stryker
- Olympus Corporation
- Intuitive Surgical
- Smith & Nephew
- Cook Medical
- Zimmer Biomet
- Boston Scientific
- Abbott
- Teleflex
- Getinge AB
- ConMed Corporation
- Applied Medical Resources
- Integra LifeSciences
- Erbe Elektromedizin GmbH
- Richard Wolf GmbH
- KLS Martin Group
Frequently Asked Questions
What is the current market size and forecast for the General Surgery Devices Market?
The market is estimated at USD 22.5 Billion in 2025 and is projected to grow to USD 45.8 Billion by 2034, representing a CAGR of 8.2% over the forecast period.
Which product segment is expected to see the fastest growth?
The Robotic-Assisted Surgical Systems and Energy-based Surgical Devices segments are expected to see the highest growth due to the shift toward precision-based minimally invasive procedures.
What are the primary drivers of growth in the Asia-Pacific region?
Growth in APAC is driven by rapid healthcare infrastructure development, an increasing volume of elective surgeries, and government policies aimed at improving surgical outcomes in emerging economies like China and India.
How is AI influencing the development of surgical devices?
AI is being integrated into surgical navigation and imaging systems to provide real-time anatomical identification, reduce human error, and assist surgeons in decision-making during complex procedures.
What are the key challenges facing market players today?
The main challenges include navigating the high cost of R&D for advanced technologies, meeting stringent international regulatory standards (like EU MDR), and managing supply chain disruptions for sophisticated electronic components.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted