Digital Pathology Market
Digital Pathology Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_700630 | Published On : October 12, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Digital Pathology Market Size
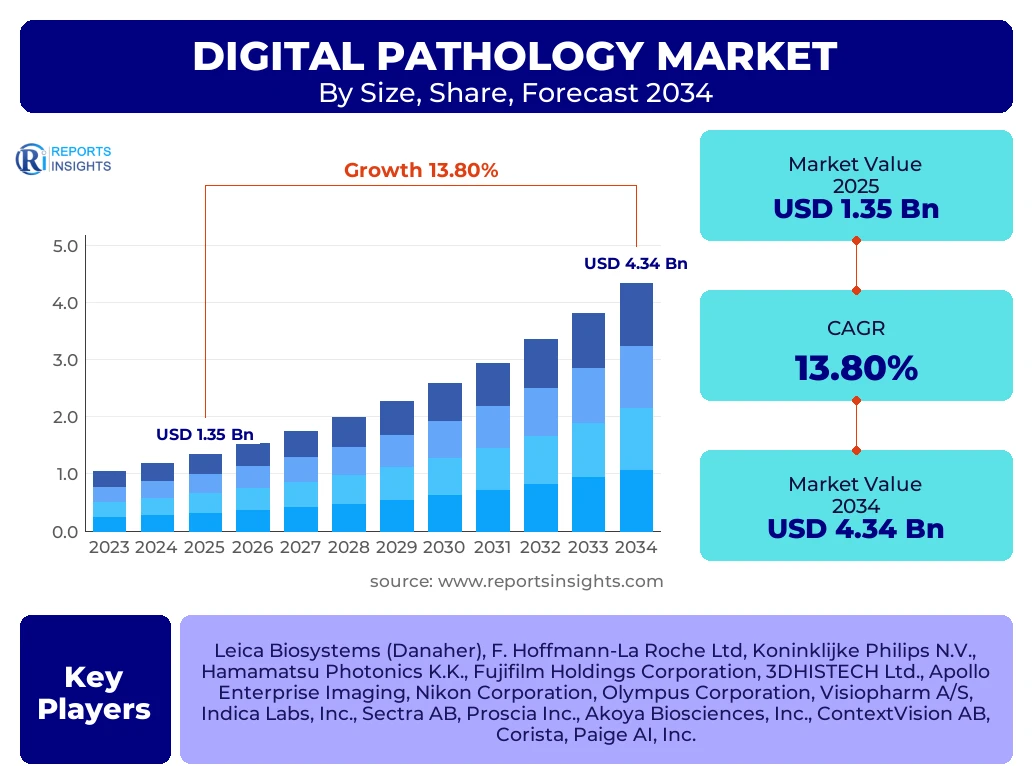
According to Reports Insights Consulting Pvt Ltd, The Digital Pathology Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 13.8% between 2025 and 2034. The market is estimated at USD 1.54 Billion in 2026 and is projected to reach USD 4.34 Billion by the end of the forecast period in 2034.
Key Digital Pathology Market Trends & Insights
The global digital pathology landscape is undergoing a radical transformation driven by the integration of Artificial Intelligence (AI) and Machine Learning (ML) into diagnostic workflows. Stakeholders are increasingly seeking automated solutions that can handle high-volume slide scanning while providing predictive analytics for oncology and chronic disease management. The shift from traditional light microscopy to digital whole-slide imaging (WSI) is no longer a luxury but a necessity for laboratories aiming to improve turnaround times and diagnostic accuracy. Competitive benchmarking reveals that market leaders are pivoting toward cloud-native platforms to facilitate seamless telepathology and global collaboration, addressing the critical shortage of sub-specialized pathologists in remote regions.
- Largest Region: North America remains the dominant market shareholder, supported by early clinical adoption, a robust regulatory framework for primary diagnosis, and heavy investment in cancer research.
- Fastest Growing Region: Asia-Pacific is expected to witness the highest CAGR, fueled by rapid healthcare infrastructure modernization in China and India and an increasing volume of clinical trials in the region.
- Largest Segment by Product: The Scanners and Hardware segment currently holds the largest market share due to the initial high capital expenditure required for laboratory digitization.
- Largest Segment by Application: Drug Discovery and Development leads the market applications as pharmaceutical companies utilize digital pathology to streamline toxicological studies and biomarker identification.
- Leading End-User: Pharmaceutical and Biotechnology companies represent the primary revenue contributors, though Clinical Diagnostic Labs are the fastest-growing end-user segment.
Key Takeaways Digital Pathology Market Size & Forecast
The digital pathology market is characterized by a transition from standalone hardware sales to comprehensive, integrated software ecosystems. Market participants are focusing on interoperability and the adoption of DICOM standards to ensure that digital images can be shared across different hospital information systems (HIS) and laboratory information systems (LIS). The forecast period highlights a significant rise in the adoption of AI-based computational pathology tools, which are expected to reduce human error and provide quantitative data that was previously inaccessible through manual observation. This evolution is critical for the advancement of precision medicine and personalized therapeutic interventions.
- Strategic Market Valuation: The market is set to triple in value over the next decade, driven by a 13.8% CAGR, reflecting a high reinvestment rate in digital health technologies.
- Primary Diagnostic Approval: The FDA’s expanding approvals for digital pathology systems for primary diagnosis in the United States serve as a major catalyst for hospital-wide implementations.
- Prevalence of Chronic Diseases: The rising global incidence of cancer is the fundamental driver necessitating faster, more accurate diagnostic tools provided by digital imaging.
- Telepathology Expansion: Digital pathology is bridging the geographical gap between specialists and patients, particularly in the EMEA and APAC regions, enhancing the quality of secondary consultations.
- AI Integration: Over 60% of new digital pathology installations are expected to include some form of AI-assisted image analysis software by 2030.
Digital Pathology Market Drivers Analysis
The primary driver for the digital pathology market is the escalating global burden of oncological malignancies, which requires sophisticated diagnostic infrastructure to handle increasing sample volumes. Traditional pathology workflows are becoming bottlenecks in modern oncology centers; thus, digitization offers a scalable solution to increase throughput. Additionally, the growing emphasis on precision medicine necessitates the use of digital tools for complex biomarker scoring, such as HER2 and PD-L1, which are critical for determining patient eligibility for targeted therapies.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of AI and Deep Learning Algorithms | +4.2% | Global / North America | 2025 - 2034 |
| Increasing Prevalence of Cancer Worldwide | +3.8% | Global / Europe | 2025 - 2034 |
| Demand for Efficient Telepathology Services | +2.5% | Asia-Pacific / MEA | 2026 - 2030 |
| Government Initiatives for Healthcare Digitization | +1.9% | United Kingdom / China | 2025 - 2028 |
Digital Pathology Market Restraints Analysis
Despite the technological advantages, the market faces significant headwinds due to the high initial cost of digital pathology systems, which includes scanners, high-capacity servers, and specialized software licenses. This financial barrier often prevents small to mid-sized laboratories and clinics in developing economies from adopting these technologies. Furthermore, the lack of standardized regulatory guidelines across different jurisdictions for AI-based diagnostic tools creates uncertainty for manufacturers and slows down the commercialization process.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Capital Expenditure and Maintenance Costs | -2.1% | Latin America / Africa | 2025 - 2034 |
| Data Privacy and Cybersecurity Concerns | -1.4% | European Union (GDPR) | 2025 - 2034 |
| Resistance to Traditional Workflow Changes | -0.8% | Global | 2025 - 2027 |
Digital Pathology Market Opportunities Analysis
The emergence of cloud-based digital pathology platforms presents a significant opportunity for market players to offer Software-as-a-Service (SaaS) models, making technology more accessible through operational expenditure (OPEX) rather than capital expenditure (CAPEX). Furthermore, the integration of digital pathology with other -omics data (genomics, proteomics) allows for the development of multi-modal diagnostic platforms. This convergence is expected to create a new frontier in R&D, particularly for personalized vaccine development and advanced immunotherapy trials.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cloud-native Deployment and SaaS Models | +3.5% | Global | 2026 - 2034 |
| Expansion into Emerging Markets (India, Brazil) | +2.8% | BRIC Nations | 2027 - 2034 |
| Multi-modal Data Integration for Precision Medicine | +2.2% | North America / Japan | 2028 - 2034 |
Digital Pathology Market Challenges Impact Analysis
A major technical challenge in the digital pathology market is the management of massive data volumes generated by whole-slide imaging. A single scanned slide can exceed several gigabytes, leading to immense storage and bandwidth requirements for large-scale clinical implementation. Additionally, the interoperability between different vendor platforms remains a hurdle; many laboratories use equipment from multiple manufacturers, and the lack of a universal file format can complicate the seamless exchange of diagnostic information.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Large Data Storage and Management Requirements | -1.9% | Global | 2025 - 2034 |
| Interoperability and Vendor Lock-in Issues | -1.2% | Global | 2025 - 2030 |
| Shortage of Pathologists Trained in Digital Tools | -0.7% | Developed Economies | 2025 - 2028 |
Digital Pathology Market - Updated Report Scope
This comprehensive market report provides an in-depth analysis of the global digital pathology ecosystem, covering hardware, software, and service components across various clinical and research applications. The scope includes a detailed evaluation of current technological trends, regulatory shifts, and competitive dynamics across six major geographical regions. By synthesizing primary and secondary data, the report offers actionable insights into the growth drivers and barriers that will shape the industry over the next decade.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.35 Billion |
| Market Forecast in 2034 | USD 4.34 Billion |
| Growth Rate | 13.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Leica Biosystems (Danaher), F. Hoffmann-La Roche Ltd, Koninklijke Philips N.V., Hamamatsu Photonics K.K., Fujifilm Holdings Corporation, 3DHISTECH Ltd., Apollo Enterprise Imaging, Nikon Corporation, Olympus Corporation, Visiopharm A/S, Indica Labs, Inc., Sectra AB, Proscia Inc., Akoya Biosciences, Inc., ContextVision AB, Corista, Paige AI, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The digital pathology market is segmented based on product type, application area, and end-user profile to provide a granular view of the revenue distribution. The product segment is currently dominated by high-resolution scanners, although the software segment is poised for the fastest growth as laboratories transition to subscription-based AI analytics. Application-wise, disease diagnosis is seeing a surge in adoption due to the approval of digital slides for primary clinical use, whereas the end-user landscape remains centered on large-scale pharmaceutical research and academic centers that possess the capital for initial infrastructure deployment.
- By Product:
- Scanners (Brightfield, Fluorescence, Others)
- Software (Information Management Systems, Image Analysis Software)
- Communication Systems
- Storage Systems
- By Application:
- Drug Discovery & Development
- Clinical Disease Diagnosis (Oncology, Hematology, Neuropathology)
- Research & Development (R&D)
- Education and Training
- By End-User:
- Pharmaceutical and Biotechnology Companies
- Hospitals and Diagnostic Laboratories
- Academic and Research Institutes
- Contract Research Organizations (CROs)
Regional Highlights
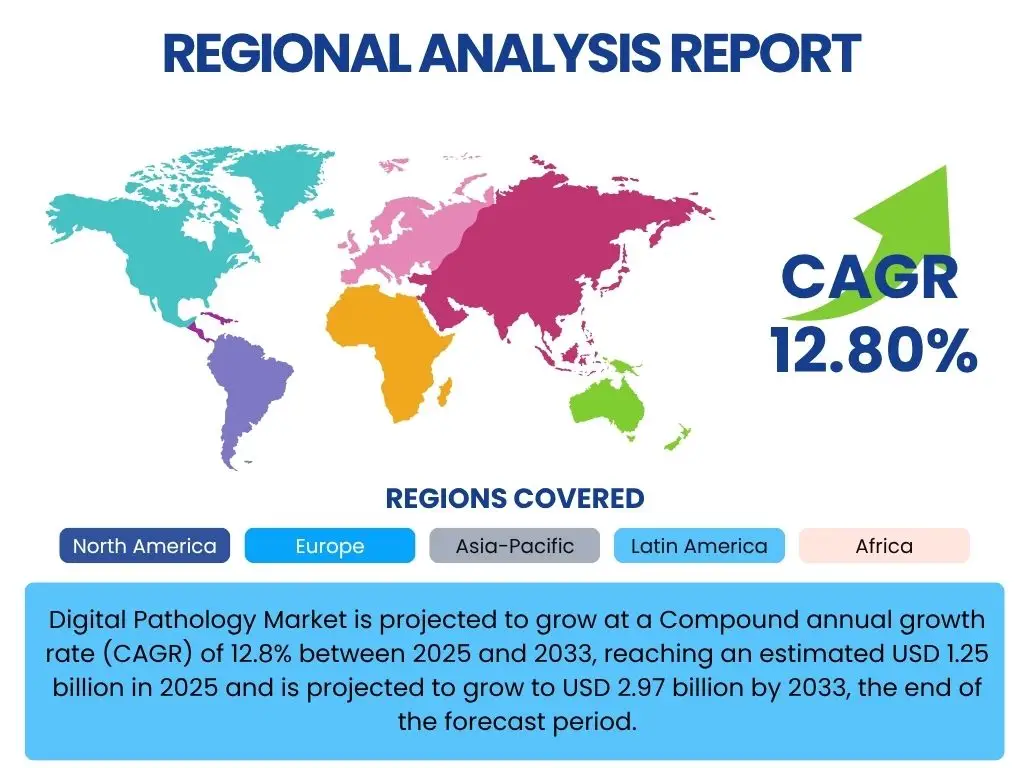
- North America: This region accounts for the largest market share (over 35%) due to favorable reimbursement policies, high healthcare spending, and the presence of major market players. The United States is the primary contributor, particularly with the FDA's clearance of digital systems for primary diagnostic workflows.
- Europe: Europe is the second-largest market, characterized by strong government support for cancer screening programs and a high level of laboratory automation in countries like Germany, the UK, and France.
- Asia-Pacific: The region is the fastest-growing market, driven by Japan's aging population, China's massive investment in healthcare AI, and the burgeoning clinical trials sector in India and South Korea.
- Latin America: Growth is primarily driven by Brazil and Mexico, where large private hospital chains are adopting digital pathology to address the shortage of specialized pathologists in rural areas.
- Middle East & Africa: The market is emerging, with significant growth in the GCC countries due to infrastructure development projects and a focus on medical tourism.
Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Digital Pathology Market.- Leica Biosystems (Danaher Corporation)
- F. Hoffmann-La Roche Ltd (Ventana Medical Systems)
- Koninklijke Philips N.V.
- Hamamatsu Photonics K.K.
- Fujifilm Holdings Corporation
- 3DHISTECH Ltd.
- Apollo Enterprise Imaging
- Nikon Corporation
- Olympus Corporation (Evident)
- Visiopharm A/S
- Indica Labs, Inc.
- Sectra AB
- Proscia Inc.
- Akoya Biosciences, Inc.
- ContextVision AB
- Corista
- Paige AI, Inc.
- Huron Digital Pathology
- Objective Pathology Services
Frequently Asked Questions
What is the current market size of the Digital Pathology market?
The global digital pathology market is estimated at approximately USD 1.35 Billion in 2025 and is projected to reach USD 4.34 Billion by 2034, growing at a CAGR of 13.8%.
How is Artificial Intelligence impacting the Digital Pathology industry?
AI is revolutionizing the industry by automating the identification of cancerous cells, providing precise biomarker quantification, and significantly reducing the workload of pathologists through predictive analytics.
Which region is expected to show the highest growth rate during the forecast period?
The Asia-Pacific region is expected to exhibit the highest CAGR due to rapid infrastructure modernization, increasing healthcare expenditure, and a rising volume of diagnostic procedures.
What are the main challenges hindering the adoption of Digital Pathology?
The primary challenges include high initial implementation costs, the need for massive data storage solutions, and a lack of universal standardization across different software and hardware vendors.
What are the key applications of Digital Pathology in healthcare?
Key applications include clinical disease diagnosis (particularly oncology), drug discovery, toxicological research, telepathology, and medical education for pathology students.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
