Dewatering Pump Market
Dewatering Pump Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711426 | Published On : November 01, 2026 |
Format : 


 | Author : Jonathan Sikka
Dewatering Pump Market Size
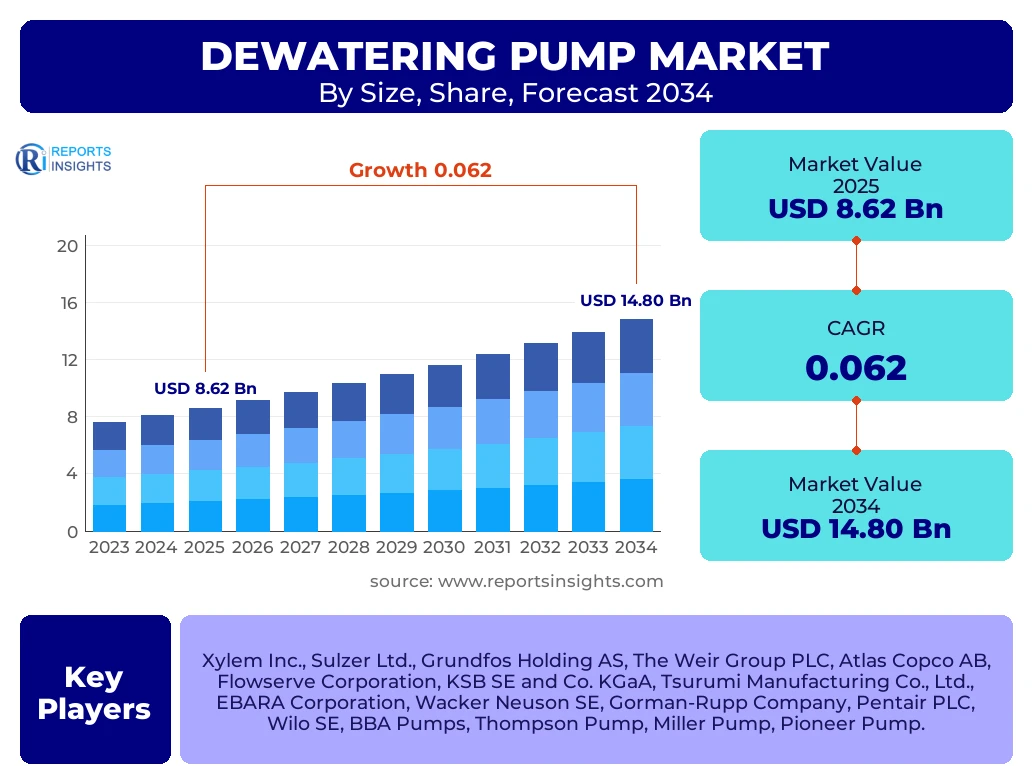
According to Reports Insights Consulting Pvt Ltd, The Dewatering Pump Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2025 and 2034. The market is estimated at USD 9.15 Billion in 2026 and is projected to reach USD 14.80 Billion by the end of the forecast period in 2034.
The global demand for dewatering pumps is intrinsically linked to the expansion of the construction and mining sectors, alongside an increasing frequency of flood-related events necessitating rapid water removal solutions. As urban landscapes expand, the requirement for robust infrastructure projects—ranging from subterranean transit systems to high-rise foundations—drives the need for continuous groundwater management. The integration of high-efficiency motor technologies and corrosion-resistant materials has further enhanced the lifecycle of these units, making them a staple in industrial utility fleets.
Furthermore, the shift toward sustainable industrial practices has spurred innovation in pump design, specifically focusing on energy consumption and the reduction of carbon footprints. Submersible dewatering pumps, in particular, have seen significant adoption due to their versatility and ability to operate in challenging environments without the risk of cavitation. As emerging economies in the Asia-Pacific and African regions invest heavily in domestic infrastructure and mineral extraction, the dewatering pump market is poised for steady, long-term capital appreciation and technological evolution.
Key Dewatering Pump Market Trends & Insights
The dewatering pump market is currently undergoing a transformative phase characterized by the integration of Digital Twin technology and Industrial Internet of Things (IIoT) sensors. These advancements allow operators to monitor pump health, flow rates, and energy usage in real-time, drastically reducing downtime through predictive maintenance. Regional analysis reveals that while North America and Europe are focusing on replacement cycles and high-efficiency upgrades, the Asia-Pacific region remains the primary engine for new equipment sales due to massive urbanization and large-scale mining operations in Australia and Southeast Asia.
- Asia-Pacific is the largest and fastest-growing region, fueled by infrastructure booms in China and India.
- Submersible pumps represent the largest segment in terms of market share due to their widespread use in construction and mining.
- The mining application segment holds a dominant position, as deep-pit mining requires continuous water table management.
- Smart pumping solutions equipped with remote monitoring capabilities are seeing a surge in adoption among municipal water authorities.
- Increasing investment in flood defense systems in coastal regions is a major emerging trend influencing product development.
Key Takeaways Dewatering Pump Market Size & Forecast
The forecast for the dewatering pump market suggests a period of sustained growth driven by global climate adaptation and industrial modernization. Stakeholders are increasingly prioritizing total cost of ownership (TCO) over initial capital expenditure, leading to a shift toward premium, long-lasting pump models. The convergence of municipal wastewater management and emergency flood response has created a dual-purpose market for portable, high-capacity dewatering units that can be deployed rapidly in varying geographic terrains.
- China and India are the leading countries in terms of volume consumption and infrastructure-led demand.
- The transition from diesel-driven to electric and solar-powered pumps is gaining momentum in environmentally sensitive zones.
- The construction industry remains the primary driver for portable dewatering units, specifically in residential and commercial basement development.
- Consolidation among key players is expected to continue as large engineering firms acquire niche pump manufacturers to diversify their portfolios.
- Advancements in wear-resistant hydraulic components are extending the service life of pumps handling abrasive slurries in mining.
Dewatering Pump Market Drivers Analysis
The primary catalysts for market expansion include the rapid pace of global urbanization, which necessitates complex underground construction, and the intensification of mining activities to meet the global demand for minerals and rare-earth elements. Additionally, the increasing severity of weather patterns leading to frequent flooding has transitioned dewatering pumps from optional equipment to essential disaster management infrastructure for municipalities worldwide.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rapid Global Urbanization and Infrastructure Growth | +2.1% | Global (High in India, China, SE Asia) | 2025 - 2034 |
| Expanding Mining Operations for Battery Minerals | +1.8% | Australia, Chile, Africa | 2026 - 2030 |
| Investment in Flood Mitigation and Emergency Response | +1.5% | North America, Europe, Coastal Asia | 2025 - 2034 |
| Technological Shift to IIoT-Enabled Smart Pumps | +0.8% | USA, Germany, Japan | 2027 - 2034 |
Dewatering Pump Market Restraints Analysis
Despite strong growth, the market faces hurdles such as high maintenance requirements in abrasive environments and stringent environmental regulations regarding the discharge of contaminated water. Furthermore, the high initial cost of advanced, automated pumping systems can be a deterrent for small-scale contractors in developing regions, leading them to opt for lower-cost, less efficient alternatives.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Environmental Regulations on Water Discharge | -0.9% | European Union, North America | 2025 - 2034 |
| High Operational and Maintenance Costs in Corrosive Media | -0.7% | Middle East, Mining Clusters | 2026 - 2032 |
| Volatility in Raw Material Prices (Steel and Copper) | -0.6% | Global | 2025 - 2028 |
Dewatering Pump Market Opportunities Analysis
Significant opportunities lie in the development of solar-powered dewatering solutions for remote mining and agricultural sites, reducing reliance on expensive diesel fuel. Additionally, the growing "Pump-as-a-Service" or rental model allows manufacturers to reach a broader customer base that prefers operational expenditure (OPEX) over capital expenditure (CAPEX), particularly in the volatile construction sector.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Renewable Energy-Powered Pumping Units | +1.4% | Africa, Latin America, Australia | 2027 - 2034 |
| Expansion of Rental and Leasing Business Models | +1.2% | North America, Europe | 2025 - 2034 |
| Increasing Demand in Wastewater Treatment Facility Upgrades | +1.1% | Global (Emerging Economies) | 2026 - 2034 |
Dewatering Pump Market Challenges Impact Analysis
The market must navigate challenges such as intense competition from low-cost manufacturers in the unorganized sector, which can erode profit margins for premium brands. Additionally, the logistical complexities of transporting heavy dewatering equipment to remote, disaster-stricken, or high-altitude mining sites remain a significant operational hurdle for service providers.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Disruptions for Specialized Components | -0.5% | Global | 2025 - 2027 |
| Competition from Local and Low-Cost Manufacturers | -0.8% | China, India, Brazil | 2025 - 2034 |
| Lack of Skilled Technicians for Smart Pump Maintenance | -0.4% | Middle East, Africa | 2028 - 2034 |
Dewatering Pump Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the global dewatering pump landscape, covering technological advancements, regulatory frameworks, and competitive dynamics. It provides granular data on market sizing across various pump types—submersible, centrifugal, and diaphragm—while evaluating their deployment across key industries such as construction, mining, oil and gas, and municipal utilities from 2020 through the forecast end-point of 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 8.62 Billion |
| Market Forecast in 2034 | USD 14.80 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Xylem Inc., Sulzer Ltd., Grundfos Holding AS, The Weir Group PLC, Atlas Copco AB, Flowserve Corporation, KSB SE and Co. KGaA, Tsurumi Manufacturing Co., Ltd., EBARA Corporation, Wacker Neuson SE, Gorman-Rupp Company, Pentair PLC, Wilo SE, BBA Pumps, Thompson Pump, Miller Pump, Pioneer Pump. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The dewatering pump market is segmented primarily by product technology and end-use application. Submersible pumps dominate the landscape due to their high efficiency in deep-well and subterranean applications, whereas centrifugal pumps remain the standard for high-volume surface water management. The application segment is led by construction and mining, with municipal demand growing rapidly in response to climate-induced flood management needs.
- By Pump Type: Submersible Pumps (Electric and Hydraulic), Centrifugal Pumps (Self-Priming and End-Suction), Diaphragm Pumps, and Rotary Pumps.
- By Application: Construction (Residential, Commercial, Civil Infrastructure), Mining and Quarrying (Open Pit, Underground), Municipal (Wastewater, Flood Control), Oil and Gas (Upstream and Midstream), and General Industrial.
- By Power Source: Electric-driven (High efficiency, low emissions), Diesel-driven (High portability, heavy-duty), and Solar-Hybrid (Emerging sustainable segment).
- By Capacity: Small (Up to 500 GPM), Medium (500–2,000 GPM), and Large (Above 2,000 GPM).
Regional Highlights
The Asia-Pacific region stands as the dominant market, contributing significantly to global revenue. This is driven by massive infrastructure investments in China’s "Belt and Road" projects and India’s "Smart Cities" initiative. Mining activities in Australia and Indonesia further bolster the demand for high-capacity dewatering units. North America and Europe follow, characterized by a focus on wastewater infrastructure modernization and the adoption of energy-efficient, IoT-integrated pumping systems. In the Middle East and Africa, the focus remains on large-scale oil and gas exploration and desalination-related dewatering projects, which require specialized, corrosion-resistant equipment.
- Asia-Pacific: Largest market share and fastest growth rate due to rapid industrialization and urbanization.
- North America: Significant demand for rental services and high-end technological upgrades in the municipal sector.
- Europe: Driven by strict environmental regulations and the shift toward electric and zero-emission pumping solutions.
- Latin America: Growth tied to mining sector recovery in Chile, Peru, and Brazil.
- Middle East and Africa: High demand for heavy-duty pumps in the energy sector and flood-prone coastal infrastructure projects.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Dewatering Pump Market.- Xylem Inc.
- Sulzer Ltd.
- Grundfos Holding AS
- The Weir Group PLC
- Atlas Copco AB
- Flowserve Corporation
- KSB SE and Co. KGaA
- Tsurumi Manufacturing Co., Ltd.
- EBARA Corporation
- Wacker Neuson SE
- Gorman-Rupp Company
- Pentair PLC
- Wilo SE
- BBA Pumps
- Thompson Pump
- Miller Pump
- Pioneer Pump (Franklin Electric)
- Prona Pump
- Varisco S.r.l.
- AllightSykes
Frequently Asked Questions
What is the current market size and projected growth of the Dewatering Pump industry?
The market is estimated at USD 9.15 Billion in 2026 and is expected to reach USD 14.80 Billion by 2034, growing at a CAGR of 6.2%.
Which region holds the largest share in the Dewatering Pump market?
The Asia-Pacific region currently holds the largest share, driven by extensive construction and mining activities in countries like China, India, and Australia.
What are the primary types of dewatering pumps used in the industry?
The primary types include Submersible Pumps, Centrifugal Pumps, and Diaphragm Pumps, with submersibles being the most widely used due to their versatility.
How is IoT affecting the Dewatering Pump market?
IoT allows for real-time monitoring of pump performance, predictive maintenance, and energy optimization, which significantly reduces downtime and operational costs.
What are the main drivers for the growth of the dewatering pump market?
Key drivers include global infrastructure development, increasing mining for green-energy minerals, and the rising need for municipal flood control systems.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
