Industrial Barrier System Market
Industrial Barrier System Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711350 | Published On : October 29, 2026 |
Format : 


 | Author : Jonathan Sikka
Industrial Barrier Systems Market Size
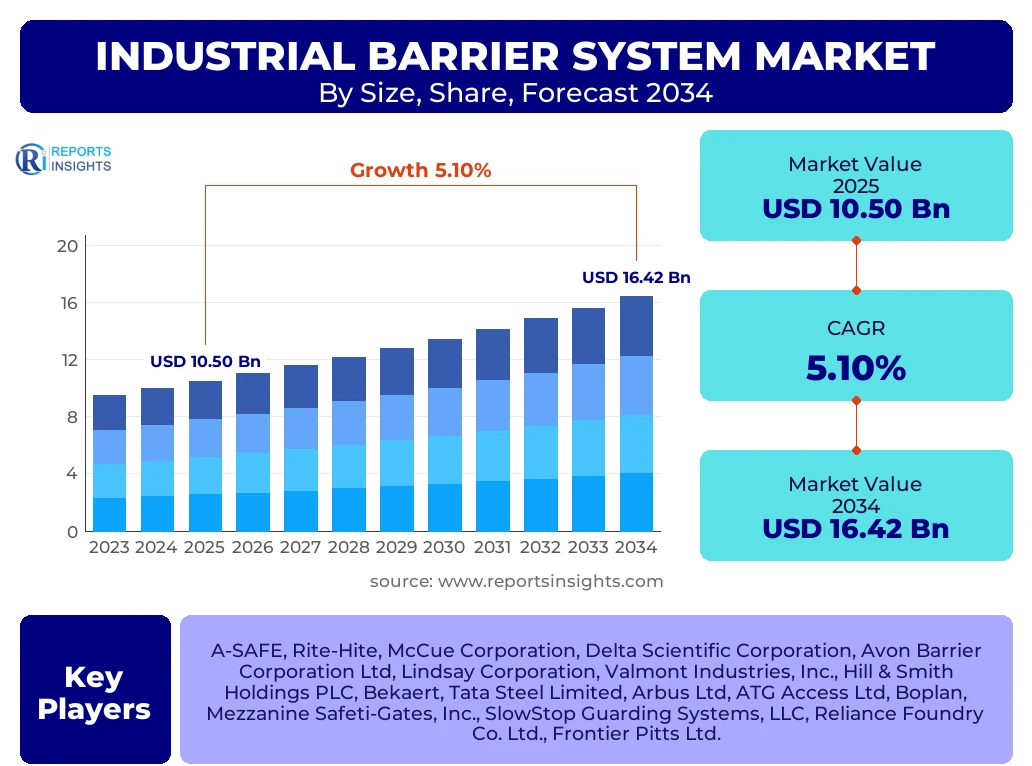
According to Reports Insights Consulting Pvt Ltd, The Industrial Barrier Systems Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.1% between 2025 and 2034. The market is estimated at USD 11.03 Billion in 2026 and is projected to reach USD 16.42 Billion by the end of the forecast period in 2034.
Key Industrial Barrier Systems Market Trends & Insights
The industrial barrier systems market is undergoing a significant transformation driven by the rapid expansion of global logistics and the tightening of workplace safety regulations. Modern industrial facilities are moving away from traditional rigid barriers toward flexible, impact-absorbing polymer solutions that minimize damage to vehicles, floors, and the barriers themselves upon collision. Furthermore, the integration of automation and the Internet of Things (IoT) is introducing "smart" barriers equipped with sensors that alert management to impacts or structural compromises in real-time, enhancing overall operational transparency and safety management.
- Asia Pacific is the fastest-growing region due to massive infrastructure investments and the rise of manufacturing hubs in India and Southeast Asia.
- The polymer-based flexible barrier segment is witnessing the highest growth rate as companies prioritize long-term cost savings on maintenance and floor repairs.
- North America remains the largest market by value, sustained by stringent OSHA (Occupational Safety and Health Administration) compliance requirements and a mature e-commerce warehousing sector.
- Increased adoption of automated guided vehicles (AGVs) and autonomous mobile robots (AMRs) in warehouses is necessitating specialized barrier configurations to protect sensitive robotic equipment.
- Sustainability is becoming a core trend, with manufacturers utilizing recycled materials for concrete and steel components to align with corporate ESG goals.
Key Takeaways Industrial Barrier Systems Market Size & Forecast
The global market for industrial barrier systems is characterized by a steady upward trajectory, fueled by the industrialization of emerging economies and the modernization of legacy facilities in developed nations. As safety protocols become more rigorous, the demand for certified, crash-tested barrier systems has become a standard requirement rather than an optional safety measure. Analysts note that the integration of barrier systems into the initial design phase of smart factories is a key driver for market expansion over the next decade.
- The Logistics and Warehousing segment is the leading end-user, accounting for over 35% of the total market share in 2025.
- Steel barriers continue to hold a significant market share in heavy industrial applications such as mining and heavy manufacturing due to their high structural integrity.
- The United States and China are the primary contributors to global revenue, representing the largest regional demand centers.
- Modular and portable barrier systems are gaining popularity in multi-use facilities where floor layouts change frequently to accommodate seasonal production demands.
- Technological advancements in energy-absorbing materials are significantly reducing the total cost of ownership by extending the lifespan of safety infrastructure.
Industrial Barrier Systems Market Drivers Analysis
The primary driver for the industrial barrier systems market is the escalating global focus on workplace safety and the reduction of occupational hazards. Governments across the globe are implementing stricter mandates to reduce workplace injuries, which significantly impact corporate productivity and insurance premiums. As industrial operations become more dense and fast-paced, particularly in high-throughput fulfillment centers, the risk of vehicle-to-pedestrian and vehicle-to-structure collisions increases, necessitating robust physical protection systems.
Additionally, the exponential growth of the e-commerce sector has led to a surge in warehouse construction and expansion. These facilities require extensive internal traffic management systems, including pedestrian walkways, rack end-protectors, and bollards, to ensure seamless flow and safety. The shift toward higher density storage also places greater emphasis on protecting vertical racking systems, which are vulnerable to forklift impacts, thus driving the demand for specialized barrier solutions.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Workplace Safety Regulations (OSHA, EU-OSHA) | +1.5% | Global (Strongest in US & EU) | 2025 - 2034 |
| E-commerce and Logistics Hub Expansion | +1.2% | China, India, USA | 2025 - 2030 |
| Adoption of Flexible Polymer Safety Solutions | +0.9% | Europe and North America | 2026 - 2034 |
| Industrial Automation and Robotic Integration | +0.8% | Japan, Germany, South Korea | 2027 - 2034 |
Industrial Barrier Systems Market Restraints Analysis
One of the significant restraints in the market is the high initial capital expenditure required for premium, high-performance barrier systems. While polymer-based flexible barriers offer long-term savings, their upfront cost is substantially higher than traditional steel or concrete alternatives, which can deter Small and Medium Enterprises (SMEs) with limited safety budgets. Furthermore, the installation process for heavy-duty fixed barriers often requires significant floor drilling and downtime, which can disrupt active industrial operations.
Volatility in raw material prices, particularly steel and high-grade plastics, also poses a challenge to market stability. Fluctuations in global commodity markets can lead to unpredictable pricing for barrier manufacturers, which is often passed down to the end-user, potentially slowing down large-scale procurement projects. Additionally, in certain developing regions, a lack of awareness regarding the long-term benefits of advanced barrier systems leads to the continued use of makeshift or non-certified safety solutions.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Installation and Material Costs | -0.7% | Developing Economies (Brazil, India) | 2025 - 2028 |
| Raw Material Price Volatility (Steel/Polymers) | -0.5% | Global | 2025 - 2034 |
Industrial Barrier Systems Market Opportunities Analysis
The emergence of "Industry 4.0" presents significant opportunities for the integration of smart technologies into barrier systems. Barriers equipped with impact sensors, LED warning lights, and connectivity to warehouse management systems (WMS) can provide invaluable data on safety "hotspots" within a facility. This allows management to implement proactive training or redesign traffic flows to prevent future accidents. The development of modular, "plug-and-play" barrier systems that can be easily reconfigured also addresses the needs of modern, agile manufacturing environments.
Furthermore, there is a burgeoning opportunity in the maintenance and service sector. As companies invest in high-end safety infrastructure, the demand for professional inspection, certification, and repair services is growing. Manufacturers who offer comprehensive safety-as-a-service models—including site audits, customized installation, and periodic safety testing—are likely to capture a larger share of the enterprise-level market. Expansion into emerging markets in Africa and Southeast Asia, where safety standards are currently being formalized, also offers long-term growth potential.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| IoT-Enabled Smart Barrier Systems | +1.1% | USA, Germany, Japan | 2026 - 2034 |
| Safety-as-a-Service and Maintenance Contracts | +0.6% | Western Europe | 2025 - 2034 |
| Development of Eco-friendly/Recycled Barriers | +0.4% | Global (ESG-focused firms) | 2028 - 2034 |
Industrial Barrier Systems Market Challenges Impact Analysis
The lack of a unified global standard for barrier impact ratings remains a critical challenge for the industry. While some regions follow specific protocols (such as PAS 13 in the UK), other markets lack rigorous testing standards, making it difficult for international manufacturers to harmonize their product lines and for customers to compare safety efficacy across different brands. This fragmentation can lead to the installation of under-performing barriers in high-risk environments.
Another challenge is the technical difficulty of retrofitting older industrial facilities with modern barrier systems. Legacy buildings often have thin or compromised floor slabs that cannot support the high-tension anchoring required for heavy-duty safety barriers. Addressing these structural limitations requires specialized engineering solutions, which can add complexity and cost to safety upgrade projects. Additionally, the rapid pace of change in warehouse automation means that barrier configurations must be constantly updated to keep up with new robotic and human traffic patterns.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fragmentation of Global Safety Standards | -0.4% | Global | 2025 - 2030 |
| Retrofitting Challenges in Legacy Facilities | -0.3% | Developed Markets (Older Industrial Zones) | 2025 - 2034 |
Industrial Barrier Systems Market - Updated Report Scope
This report provides a comprehensive analysis of the global industrial barrier systems market, covering various hardware types, material compositions, and end-user industries. It focuses on the strategic shift from passive safety to proactive, technology-driven protection in industrial environments. The scope includes detailed forecasting for regional markets and a granular breakdown of the competitive landscape, highlighting the strategies of market leaders and niche innovators.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 10.50 Billion |
| Market Forecast in 2034 | USD 16.42 Billion |
| Growth Rate | 5.1% CAGR |
| Number of Pages | 248 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | A-SAFE, Rite-Hite, McCue Corporation, Delta Scientific Corporation, Avon Barrier Corporation Ltd, Lindsay Corporation, Valmont Industries, Inc., Hill & Smith Holdings PLC, Bekaert, Tata Steel Limited, Arbus Ltd, ATG Access Ltd, Boplan, Mezzanine Safeti-Gates, Inc., SlowStop Guarding Systems, LLC, Reliance Foundry Co. Ltd., Frontier Pitts Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The industrial barrier systems market is segmented based on product type, material, and the specific functional application within a facility. The transition toward polymer materials is the most notable trend within the material segment, as these products offer superior energy dissipation and lower long-term costs. In terms of product type, guardrails and rack protectors hold the largest share due to the critical need to protect high-value inventory and structural support columns in warehouses.
- By Type: Includes heavy-duty guardrails, bollards for vehicle access control, rack end protectors, and pedestrian-segregated walkways.
- By Material: Steel remains dominant for heavy perimeter security, while polymers are leading in internal warehouse applications due to their non-corrosive and flexible properties.
- By End-User: The manufacturing sector is a key consumer, specifically in automotive and chemical plants where heavy machinery and hazardous materials require stringent containment and protection.
- By Technology: Passive barriers (stationary structures) currently dominate, but active barriers (automated gates and bollards) are growing in the security-sensitive energy and utility sectors.
Regional Highlights
- North America: The largest regional market, driven by highly developed logistics networks and a culture of strict safety compliance enforced by OSHA. The US market is characterized by high demand for advanced, crash-tested systems.
- Europe: A pioneer in safety standards such as PAS 13. The region shows high adoption of polymer-based flexible barriers and is a leader in integrating sustainability into safety infrastructure.
- Asia Pacific: The fastest-growing region, with China, India, and Vietnam seeing massive investments in new manufacturing zones and mega-warehouses. Rapid urbanization and infrastructure growth are key catalysts here.
- Middle East & Africa: Significant growth in the energy and utility sectors, where high-security perimeter barriers are essential for critical infrastructure protection.
- Latin America: Emerging market with increasing focus on industrial safety in Brazil and Mexico as they integrate more deeply into global supply chains.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Industrial Barrier Systems Market.- A-SAFE
- Rite-Hite
- McCue Corporation
- Delta Scientific Corporation
- Avon Barrier Corporation Ltd
- Lindsay Corporation
- Valmont Industries, Inc.
- Hill & Smith Holdings PLC
- Bekaert
- Tata Steel Limited
- Arbus Ltd
- ATG Access Ltd
- Boplan
- Mezzanine Safeti-Gates, Inc.
- SlowStop Guarding Systems, LLC
- Reliance Foundry Co. Ltd.
- Frontier Pitts Ltd.
- Kirchner Construction
- The SafeGate Group
- Protective Barriers Pty Ltd
Frequently Asked Questions
What is the current market size of the Industrial Barrier Systems Market?
The Industrial Barrier Systems Market is estimated to be valued at USD 11.03 Billion in 2026 and is expected to grow to USD 16.42 Billion by 2034.
Which material is growing fastest in the industrial barrier market?
Polymer-based (flexible) barriers are the fastest-growing segment due to their ability to absorb impacts without damaging floors or vehicles, reducing maintenance costs.
Which region holds the largest share of the market?
North America currently holds the largest market share, supported by stringent workplace safety regulations and a massive e-commerce and logistics sector.
What are the key drivers for market growth?
Key drivers include stricter government safety mandates, the global expansion of the warehouse and logistics industry, and the rising adoption of automated warehouse technologies.
Are smart technologies being integrated into industrial barriers?
Yes, there is an increasing trend toward integrating IoT sensors and LED warning systems into barriers to provide real-time data on collisions and enhance worker safety.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
