Dental Implant Market
Dental Implant Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_705120 | Published On : September 25, 2026 |
Format : 


 | Author : Erika Grotto
Dental Implant Market Size
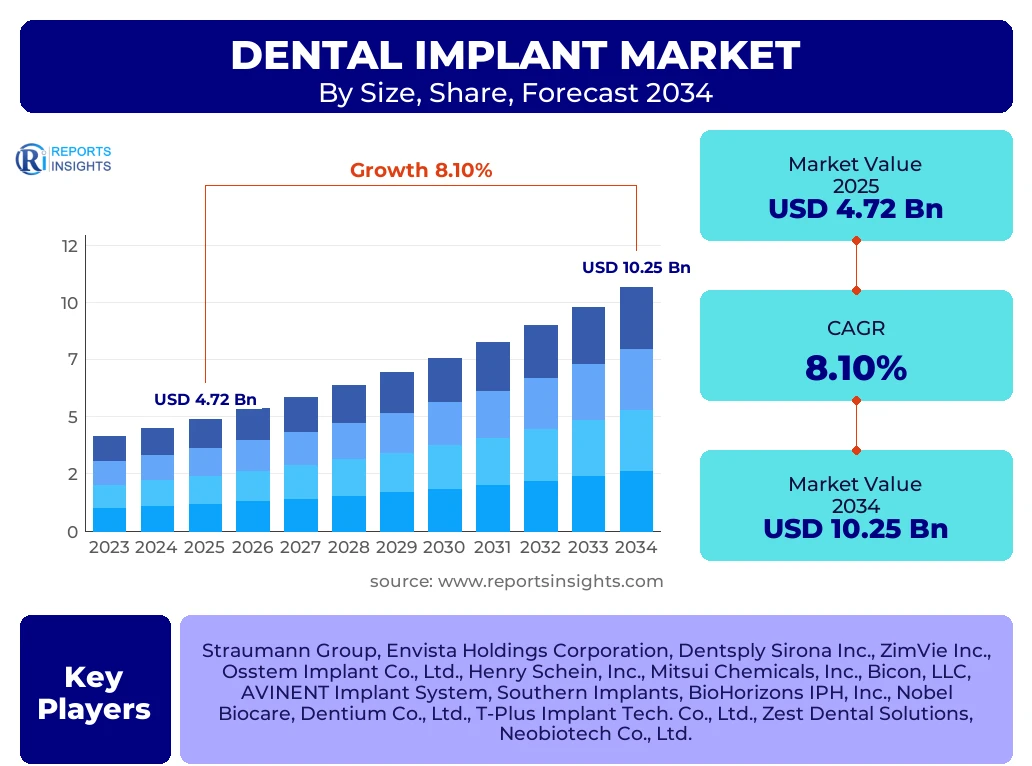
According to Reports Insights Consulting Pvt Ltd, The Dental Implant Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.1% between 2026 and 2034. The market is estimated at USD 5.1 Billion in 2026 and is projected to reach USD 10.25 Billion by the end of the forecast period in 2034.
Key Dental Implant Market Trends & Insights
The global Dental Implant landscape is undergoing a radical transformation driven by the integration of digital workflows and the rising preference for aesthetic restorative dentistry. Stakeholders are increasingly focusing on the shift from traditional titanium-based solutions to high-performance ceramic and zirconia alternatives, which offer superior biocompatibility and aesthetic outcomes. Furthermore, the market is witnessing a surge in point-of-care manufacturing through 3D printing and CAD/CAM technologies, which significantly reduce the turnaround time for prosthetic placement. Competitive benchmarking reveals that leading players are aggressively pursuing inorganic growth strategies, such as acquisitions of regional value-segment manufacturers, to expand their footprint in price-sensitive emerging economies across Asia and Latin America.
- Largest Region: North America remains the dominant regional market, accounting for a significant share of global revenue due to high healthcare expenditure and advanced clinical infrastructure.
- Fastest Growing Region: Asia Pacific is projected to be the fastest-growing region, fueled by expanding dental tourism in nations like India and Thailand and a growing middle-class population.
- Largest Segment by Material: Titanium implants continue to hold the largest market share owing to their proven long-term clinical success and high strength-to-weight ratio.
- Largest Segment by Design: Endosteal implants represent the primary design category used in modern clinical practice, favored for their stability and integration with the jawbone.
Key Takeaways Dental Implant Market Size & Forecast
The Dental Implant market is characterized by a structural shift toward the "value" segment as clinicians seek cost-effective solutions without compromising on clinical efficacy. Market size expansion is heavily influenced by the increasing prevalence of edentulism among the geriatric population and the growing social acceptance of dental aesthetics. Analysis of user inquiries suggests that clinical durability and the reduction of healing times are the primary concerns for end-users, prompting manufacturers to invest in bioactive surface treatments that accelerate osseointegration. The forecast period anticipates a consolidation of market shares among top-tier global entities while niche players focusing on robotic-assisted implant surgery gain traction in developed urban centers.
- Leading Country: The United States leads the global market, supported by a robust reimbursement framework for certain dental procedures and a high concentration of specialized oral surgeons.
- Market Consolidation: Strategic mergers and acquisitions are expected to intensify, particularly targeting companies with innovative digital scanning and diagnostic capabilities.
- Material Innovation: Zirconia implants are gaining rapid adoption in the premium segment as a metal-free alternative, catering to patients with metal sensitivities.
- Procedure Trends: Immediate loading protocols are becoming more common, reducing the total treatment time from months to a single day for eligible candidates.
Dental Implant Market Drivers Analysis
The primary driver for the Dental Implant market is the global demographic shift toward an aging population. As the life expectancy of individuals increases worldwide, the incidence of age-related tooth loss or edentulism rises proportionately. Unlike traditional dentures or bridges, Dental Implant provide a permanent, functional, and aesthetically pleasing solution that preserves bone density, making them the preferred choice for both clinicians and patients. This shift is further supported by the rising disposable income in developing nations, allowing a larger segment of the population to access high-end dental restorative services.
Additionally, technological advancements in diagnostic imaging, such as Cone Beam Computed Tomography (CBCT), have revolutionized treatment planning. These tools allow for high-precision placement of implants, reducing the risk of surgical complications and improving the overall success rate of the procedure. The integration of artificial intelligence in surgical planning software is also driving market growth by optimizing implant positioning and predicting long-term outcomes, thereby increasing patient confidence in the procedure.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Aging Global Population and Edentulism | +3.2% | Global (Japan, Germany, USA) | Long-term (2025-2034) |
| Advancements in CAD/CAM and 3D Printing | +2.1% | North America and Europe | Short to Mid-term |
| Growth in Dental Tourism | +1.5% | Mexico, India, Thailand, Hungary | Mid-term |
| Shift Toward Cosmetic Dentistry | +1.3% | Global (Urban Centers) | Long-term |
Dental Implant Market Restraints Analysis
Despite the high demand, the primary restraint remains the high cost of dental implant procedures, which often includes the cost of the implant itself, the abutment, the crown, and potential bone grafting surgeries. In many regions, dental insurance coverage is limited or nonexistent for "cosmetic" restorative procedures, placing a heavy financial burden on the patient. This economic barrier limits the market penetration of premium implant brands, particularly in low-to-middle-income countries where traditional dentures remain the standard of care due to affordability.
Furthermore, the complexity of the surgical procedure and the requirement for highly skilled professionals act as a bottleneck. There is a significant shortage of trained oral surgeons and periodontists in certain rural and developing areas. The potential for post-surgical complications, such as peri-implantitis, also remains a concern for patients, occasionally leading to a preference for non-invasive alternatives. Regulatory hurdles and the long duration required for clinical trials of new materials can also delay the entry of innovative products into the market.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Procedure Costs & Lack of Insurance | -2.4% | Latin America and SE Asia | Ongoing |
| Risk of Peri-implantitis and Complications | -0.8% | Global | Short-term |
Dental Implant Market Opportunities Analysis
The emergence of "Mini Dental Implant" (MDIs) presents a significant opportunity for market expansion. These smaller-diameter implants are less invasive, require less bone density for placement, and are generally more affordable than standard implants. They open the market to a demographic that may have previously been excluded due to anatomical limitations or financial constraints. As clinical data continues to validate the long-term stability of MDIs, their adoption in stabilizing lower dentures is expected to surge.
Moreover, the expansion of corporate dental chains and Dental Service Organizations (DSOs) provides a streamlined channel for manufacturers to distribute products at scale. DSOs often standardize their procurement processes, creating opportunities for long-term supply contracts. The integration of regenerative medicine, such as the use of Platelet-Rich Fibrin (PRF) and bone morphogenetic proteins, alongside implant surgery, offers another avenue for growth, as these technologies enhance the healing process and expand the pool of eligible candidates for implants.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Adoption of Zirconia (Metal-free) Implants | +1.8% | Europe (Germany, Switzerland) | 2026-2034 |
| Expansion of Dental Service Organizations (DSOs) | +1.4% | United States and China | Mid-term |
| Development of Bioactive Surface Coatings | +1.1% | Global (R&D Hubs) | Long-term |
Dental Implant Market Challenges Impact Analysis
One of the most pressing challenges is the intense price competition from "copycat" or discount implant manufacturers. As patents for earlier generations of implant designs expire, smaller regional players are entering the market with significantly cheaper alternatives that mimic the geometry of premium brands. This creates a pricing war that can erode the profit margins of established global leaders, forcing them to justify their higher price points through extensive clinical documentation and value-added services such as education and digital integration.
Additionally, the global supply chain for raw materials like medical-grade titanium and high-purity zirconia is subject to geopolitical tensions and logistical disruptions. Fluctuations in the prices of these materials can impact the manufacturing costs and final pricing of implants. Furthermore, the stringent and evolving regulatory landscape, such as the transition to the Medical Device Regulation (MDR) in the European Union, imposes higher compliance costs and longer lead times for product certifications, challenging the agility of manufacturers in bringing new innovations to market.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Price Erosion from Discount Manufacturers | -1.2% | Europe and Asia Pacific | Ongoing |
| Regulatory Stringency (EU MDR Compliance) | -0.7% | European Union | 2025-2027 |
Dental Implant Market - Updated Report Scope
This comprehensive report provides a detailed analysis of the global Dental Implant industry, covering technological advancements, regulatory frameworks, and competitive dynamics. The scope includes a granular breakdown of market size and forecast by material, design, price point, and end-user, ensuring that stakeholders have actionable intelligence to navigate the evolving dental landscape. The report also evaluates the impact of macroeconomic factors such as healthcare inflation and consumer spending patterns on the adoption of elective dental procedures.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 4.72 Billion |
| Market Forecast in 2034 | USD 10.25 Billion |
| Growth Rate | 8.1% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Straumann Group, Envista Holdings Corporation, Dentsply Sirona Inc., ZimVie Inc., Osstem Implant Co., Ltd., Henry Schein, Inc., Mitsui Chemicals, Inc., Bicon, LLC, AVINENT Implant System, Southern Implants, BioHorizons IPH, Inc., Nobel Biocare, Dentium Co., Ltd., T-Plus Implant Tech. Co., Ltd., Zest Dental Solutions, Neobiotech Co., Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Dental Implant market is segmented based on material, design, price point, and end-user environment. The material segment is currently dominated by titanium due to its exceptional biocompatibility and mechanical strength, though zirconia is rapidly gaining ground in the aesthetic and holistic dentistry sectors. Price point segmentation reveals a growing "Value" segment as manufacturers aim to capture the middle-class demographic in emerging economies. By end-user, dental clinics remain the primary site of service, though hospitals are seeing increased volumes for complex reconstructive cases involving maxillofacial trauma.
- By Material:
- Titanium Implants
- Zirconium (Ceramic) Implants
- By Design:
- Endosteal Implants (Screw, Cylinder, Blade)
- Subperiosteal Implants
- Transosteal Implants
- By Price Point:
- Premium Implants
- Value Implants
- Discount Implants
- By End-User:
- Independent Dental Clinics
- Hospitals and Multi-specialty Centers
- Dental Service Organizations (DSOs)
Regional Highlights
- North America: Holds the largest market share, driven by a high awareness of oral health, favorable reimbursement for medically necessary implants, and the presence of major industry players like Envista and Dentsply Sirona. The United States is the primary revenue contributor in this region.
- Europe: A mature market characterized by high penetration rates in Germany, Italy, and Spain. Germany is a global hub for dental technology innovation, particularly in zirconia implants and digital imaging systems.
- Asia Pacific: The fastest-growing region, with China and India leading the way. The growth is fueled by an increasing number of dental professionals, rising medical tourism in South East Asia, and expanding healthcare infrastructure.
- Latin America: Brazil is a key market in this region, known for its high number of cosmetic dental procedures and a robust local manufacturing base for value-segment implants.
- Middle East & Africa: Growing steadily due to increased investment in healthcare tourism hubs like Dubai and Riyadh, though high costs remain a challenge in African sub-regions.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Dental Implant Market.- Straumann Group
- Envista Holdings Corporation (Nobel Biocare)
- Dentsply Sirona Inc.
- ZimVie Inc. (Zimmer Biomet)
- Osstem Implant Co., Ltd.
- Henry Schein, Inc.
- Mitsui Chemicals, Inc. (Kyocera)
- Bicon, LLC
- AVINENT Implant System
- Southern Implants
- BioHorizons IPH, Inc.
- Dentium Co., Ltd.
- T-Plus Implant Tech. Co., Ltd.
- Zest Dental Solutions
- Neobiotech Co., Ltd.
- Cortex Dental Implant Industries Ltd.
- MegaGen Implant Co., Ltd.
- A.B. Dental Devices Ltd.
Frequently Asked Questions
What is the projected growth rate of the Dental Implant Market through 2034?
The Dental Implant Market is expected to grow at a CAGR of 8.1% from 2025 to 2034, reaching an estimated valuation of USD 10.25 Billion by the end of the forecast period.
Which material is preferred for Dental Implant, Titanium or Zirconia?
Titanium remains the industry standard due to its high success rate and durability. However, Zirconia is increasingly preferred for patients seeking metal-free alternatives and superior aesthetic results in the "smile zone."
What are the main drivers of the Dental Implant Market?
The key drivers include the aging global population, rising prevalence of tooth loss, technological advancements in CAD/CAM and 3D printing, and the growing demand for cosmetic dental procedures.
Which region is leading the Dental Implant industry in terms of revenue?
North America, specifically the United States, currently leads the market due to its advanced dental healthcare infrastructure and high consumer spending on restorative dentistry.
What is the difference between endosteal and subperiosteal implants?
Endosteal implants are placed directly into the jawbone and are the most common type, whereas subperiosteal implants are placed on top of the jawbone under the gum tissue, typically used for patients with insufficient bone height.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
