Dental Bonding Agent Market
Dental Bonding Agent Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711819 | Published On : November 17, 2026 |
Format : 


 | Author : Erika Grotto
Dental Bonding Agent Market Size
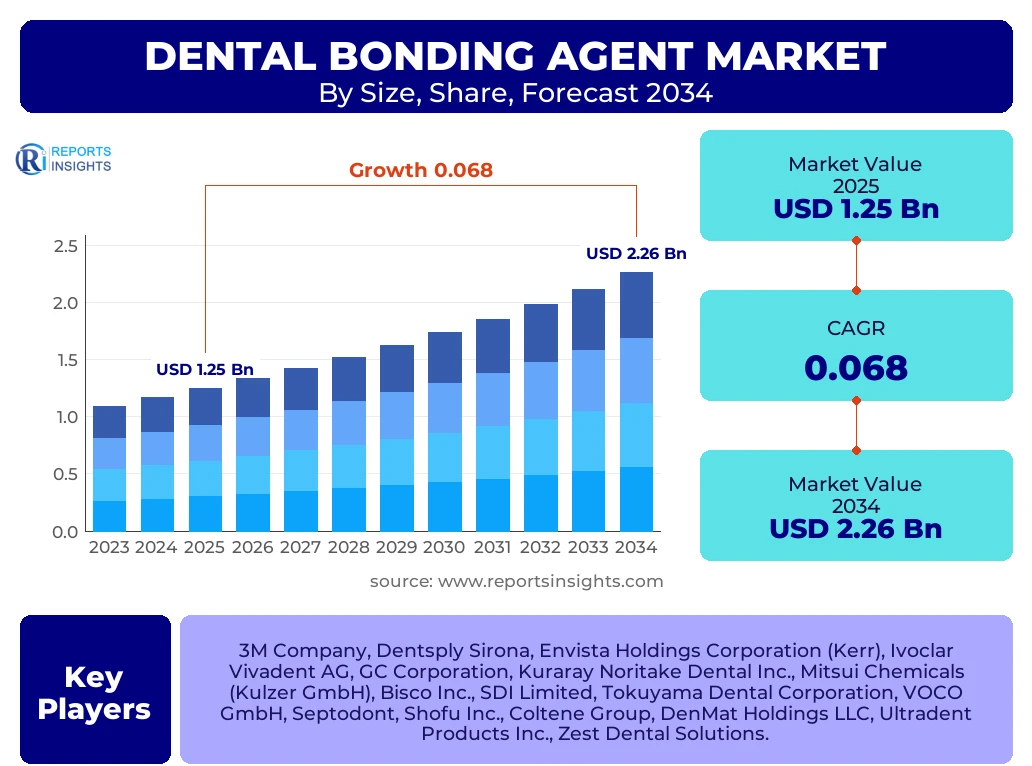
According to Reports Insights Consulting Pvt Ltd, The Dental Bonding Agent Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.8% between 2025 and 2034. The market is estimated at USD 1.33 Billion in 2026 and is projected to reach USD 2.26 Billion by the end of the forecast period in 2034.
Key Dental Bonding Agent Market Trends & Insights
The dental bonding agent market is currently experiencing a transformative phase characterized by a shift toward simplified clinical protocols and the integration of multifunctional chemical properties. Professional dental practitioners are increasingly prioritizing universal adhesives that offer compatibility with various etching techniques, including total-etch, self-etch, and selective-etch modes. This flexibility reduces inventory costs and mitigates technique sensitivity, which has historically been a significant barrier to achieving long-term bond durability. Furthermore, the rise of aesthetic dentistry and the growing middle-class population in emerging economies are fueling the demand for composite restorations, which directly correlates with the increased consumption of high-performance bonding agents.
- North America remains the largest regional market due to high healthcare expenditure and a strong emphasis on cosmetic dental procedures.
- The Asia-Pacific region is documented as the fastest-growing market, driven by expanding dental tourism and improving healthcare infrastructure in nations like China and India.
- The Universal Adhesives segment holds the largest market share as clinicians move away from multi-step systems to single-bottle solutions.
- Nanotechnology integration in bonding agents is a significant trend, enhancing the mechanical strength and film thickness of the adhesive layer.
- Growth in the geriatric population globally is increasing the prevalence of root caries and tooth fractures, necessitating more frequent use of bonding materials.
Key Takeaways Dental Bonding Agent Market Size & Forecast
The dental bonding agent market is poised for robust expansion as the global dental industry transitions from traditional amalgam restorations to more biocompatible and aesthetically pleasing resin-based composites. Advanced statistics indicate that the total-etch segment still maintains a loyal user base for specific high-stress clinical scenarios, yet the convenience of self-etch systems is rapidly closing the gap. Market stability is further supported by the high replacement rate of dental restorations, where bonding agents play a critical role in secondary caries prevention and marginal seal integrity.
- The United States is the leading country in terms of value, supported by a high density of specialized dental clinics and rapid adoption of 8th generation bonding agents.
- The "Universal" bonding category is expected to outpace all other generations in terms of adoption rate through 2034.
- Dental clinics represent the primary end-user segment, accounting for over 60% of the total market revenue.
- Strategic partnerships between adhesive manufacturers and CAD/CAM system providers are becoming a standard for seamless digital dentistry workflows.
- Inhibition of matrix metalloproteinases (MMPs) within the bonding agent formulation is emerging as a critical factor for improving the longevity of the hybrid layer.
Dental Bonding Agent Market Drivers Analysis
The primary catalysts for market growth include the rising global incidence of dental caries and the increasing consumer preference for minimally invasive dental procedures. As patients demand more conservative treatments that preserve natural tooth structure, the reliance on high-strength chemical bonding becomes paramount. Additionally, the proliferation of dental insurance coverage in developing regions and the technological evolution of light-curing units have enhanced the efficiency and reliability of bonding procedures in chairside settings.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shift Toward Aesthetic and Cosmetic Dentistry | +2.1% | Global (High in North America & Europe) | 2025 - 2034 |
| Technological Advancements in Universal Adhesives | +1.8% | Japan, Germany, USA | 2025 - 2030 |
| Rising Geriatric Population and Edentulism Risks | +1.5% | Western Europe, China, Japan | 2027 - 2034 |
| Growth in Dental Tourism | +1.4% | Mexico, Thailand, Hungary, India | 2025 - 2034 |
Dental Bonding Agent Market Restraints Analysis
Despite the positive trajectory, the market faces headwinds from the high cost of premium bonding systems and the stringent regulatory approval processes for new chemical formulations. In some price-sensitive markets, the continued use of traditional mechanical retention methods and lower-cost alternatives hampers the penetration of advanced 7th and 8th generation adhesives. Furthermore, the complexity of moisture control during the bonding process remains a clinical challenge that can lead to premature restoration failure.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Advanced Multi-mode Adhesives | -1.2% | Latin America, Africa | 2025 - 2030 |
| Technique Sensitivity and Risk of Post-operative Sensitivity | -0.8% | Global | Continuous |
| Limited Reimbursement for Cosmetic Procedures | -1.0% | UK, Canada, USA | 2025 - 2034 |
Dental Bonding Agent Market Opportunities Analysis
The integration of bioactive components into bonding agents represents a significant frontier for market expansion. Adhesives that can release fluoride or calcium/phosphate ions to promote remineralization at the resin-dentin interface offer a unique value proposition for preventing secondary decay. Moreover, the expansion of tele-dentistry and digital scanning allows for more precise restorative planning, where specialized bonding agents for zirconia and lithium disilicate materials are in high demand.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Bioactive and Antimicrobial Adhesives | +2.5% | USA, Germany, South Korea | 2026 - 2034 |
| Expansion in Emerging Economies (BRICS) | +2.2% | Brazil, India, China | 2025 - 2034 |
| Adhesives for Digital Workflow and CAD/CAM Blocks | +1.9% | Japan, Switzerland, USA | 2025 - 2032 |
Dental Bonding Agent Market Challenges Impact Analysis
The primary challenge remains the long-term degradation of the hybrid layer due to enzymatic hydrolysis and the presence of residual moisture in the dentinal tubules. Manufacturers are tasked with creating hydrophobic resins that can effectively penetrate hydrophilic collagen networks. Additionally, the disruption of global supply chains for specialized chemical monomers can lead to price volatility and availability issues for end-users.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Degradation of Collagen-Resin Interface Over Time | -0.9% | Global | 2025 - 2034 |
| Supply Chain Instability for Methacrylate Monomers | -0.7% | Europe, Asia | 2025 - 2027 |
| Strict Clinical Data Requirements for New Entrants | -0.5% | EU (MDR Regulations), USA (FDA) | 2025 - 2030 |
Dental Bonding Agent Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the global dental bonding agent landscape, segmented by product generation, etching technique, chemical composition, and end-user facilities. It provides a granular view of the competitive environment, regulatory frameworks, and technological breakthroughs that are defining the future of restorative dentistry. The study focuses on both the professional clinical sector and the academic research segment to provide a holistic view of market dynamics.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.25 Billion |
| Market Forecast in 2034 | USD 2.26 Billion |
| Growth Rate | 6.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | 3M Company, Dentsply Sirona, Envista Holdings Corporation (Kerr), Ivoclar Vivadent AG, GC Corporation, Kuraray Noritake Dental Inc., Mitsui Chemicals (Kulzer GmbH), Bisco Inc., SDI Limited, Tokuyama Dental Corporation, VOCO GmbH, Septodont, Shofu Inc., Coltene Group, DenMat Holdings LLC, Ultradent Products Inc., Zest Dental Solutions. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the dental bonding agent market reflects the diversity in clinical preferences and the evolution of adhesive chemistry. The market is primarily divided by the etching technique, which dictates the complexity and duration of the bonding procedure. Universal adhesives are currently the most significant growth driver as they bridge the gap between traditional and modern methodologies. Further segmentation by application highlights the shift toward bonding not just to natural tooth structure, but also to prosthetic substrates like zirconia, alumina, and various metal alloys.
- By Type of Adhesive:
- Total-Etch (Etch-and-Rinse) Systems: Preferred for high-enamel content cases.
- Self-Etch Systems: Noted for reduced post-operative sensitivity.
- Universal (Multi-mode) Adhesives: The current gold standard for versatility.
- By Generation:
- 4th and 5th Generation (Multi-step total-etch)
- 6th and 7th Generation (Self-etching primers and all-in-ones)
- 8th Generation (Nanofilled and universal systems)
- By Curing Method:
- Light-Cured: Most common for anterior and superficial posterior restorations.
- Dual-Cured: Essential for deep cavities and opaque indirect restorations.
- Self-Cured: Used in areas with limited light access.
- By End-User:
- Private Dental Clinics: Largest volume consumers.
- Dental Hospitals: Focus on high-complexity reconstructive cases.
- Educational Institutes: Significant for longitudinal clinical studies.
Regional Highlights
- North America: Holds the largest market share, driven by a mature dental industry, high awareness of oral health, and the presence of major industry players like 3M and Dentsply Sirona. The U.S. is the primary contributor to this region's dominance.
- Europe: Characterized by stringent regulatory standards and a strong preference for high-quality, durable restorative materials. Germany and Switzerland are key hubs for dental innovation and manufacturing.
- Asia-Pacific: The fastest-growing region. Rapid urbanization, increasing disposable income, and the expansion of corporate dental chains in China and India are creating significant demand for dental consumables.
- Latin America: Brazil is a standout market in this region, being one of the world leaders in cosmetic dentistry and dental research, particularly in the field of adhesive protocols.
- Middle East & Africa: Growing steadily as governments invest in healthcare infrastructure and dental tourism rises in hubs like Dubai and South Africa.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Dental Bonding Agent Market.- 3M Company
- Dentsply Sirona
- Envista Holdings Corporation (Kerr)
- Ivoclar Vivadent AG
- GC Corporation
- Kuraray Noritake Dental Inc.
- Kulzer GmbH (Mitsui Chemicals)
- Bisco Inc.
- SDI Limited
- Tokuyama Dental Corporation
- VOCO GmbH
- Septodont
- Shofu Inc.
- Coltene Group
- Ultradent Products Inc.
- DenMat Holdings LLC
- Zest Dental Solutions
- Prime Dental Products Pvt. Ltd.
- Pentron Clinical
- Huge Dental
Frequently Asked Questions
What is the difference between total-etch and self-etch dental bonding agents?
Total-etch systems require a separate phosphoric acid etching step to remove the smear layer and demineralize enamel/dentin before applying the adhesive. Self-etch systems incorporate acidic monomers into the primer or adhesive, allowing for etching and priming in fewer steps, which typically results in less post-operative sensitivity but may have slightly lower bond strength to un-cut enamel.
Why are universal bonding agents becoming the market leader?
Universal adhesives are gaining dominance because they allow dentists to use a single product for any etching protocol (total, self, or selective) and provide strong adhesion to various substrates including dentin, enamel, zirconia, and precious metals, simplifying the clinical workflow and reducing inventory.
How does the aging global population affect the dental bonding agent market?
An aging population increases the demand for restorative procedures due to higher rates of root caries, secondary decay, and tooth wear. This leads to a consistent and growing need for bonding agents to support fillings, crowns, and bridges in geriatric patients.
What is the role of MDP monomer in modern dental adhesives?
10-Methacryloyloxydecyl dihydrogen phosphate (MDP) is a functional monomer that creates a strong chemical bond with hydroxyapatite in tooth structure and metal oxides in ceramics like zirconia. It is a key ingredient in high-performance universal bonding agents for ensuring long-term durability.
Which region offers the most growth potential for manufacturers in the next decade?
The Asia-Pacific region offers the highest growth potential due to its massive population base, increasing dental healthcare spending, and the rapid expansion of dental clinic networks in emerging economies like India, China, and Vietnam.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
