Dacryocystitis Market
Dacryocystitis Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711218 | Published On : October 19, 2026 |
Format : 


 | Author : Erika Grotto
Dacryocystitis Market Size
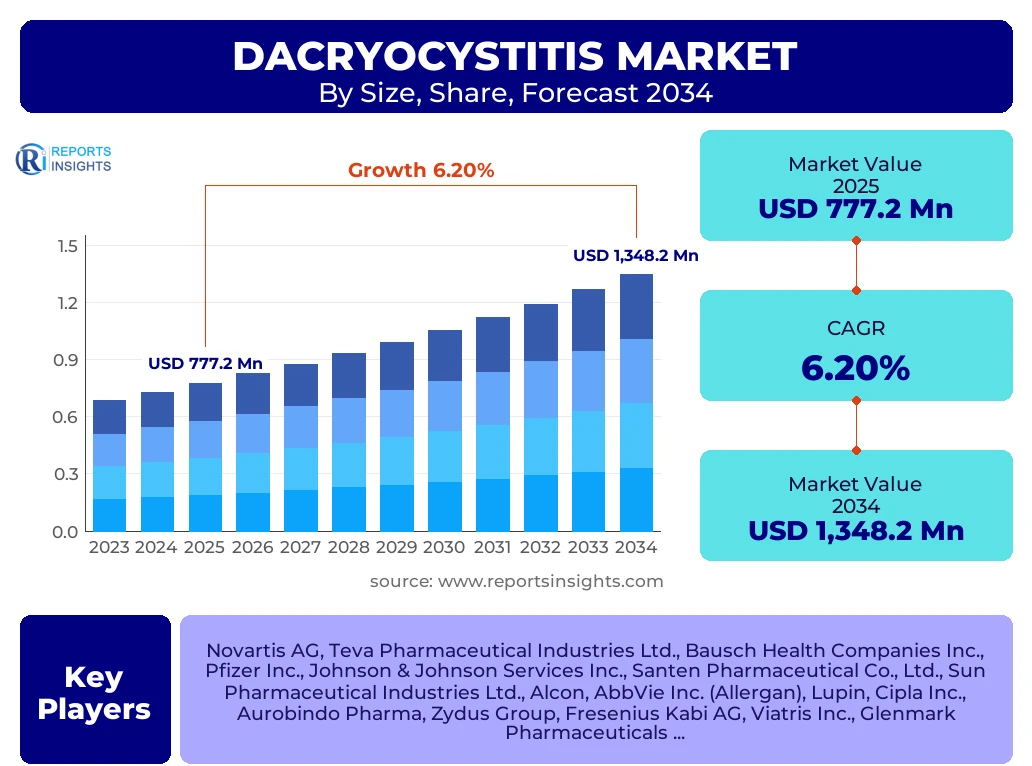
According to Reports Insights Consulting Pvt Ltd, The Dacryocystitis Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2025 and 2034. The market is estimated at USD 825.4 Million in 2026 and is projected to reach USD 1,348.2 Million by the end of the forecast period in 2034.
Key Dacryocystitis Market Trends & Insights
The global dacryocystitis market is undergoing a significant transformation driven by the evolution of surgical techniques and the increasing prevalence of ophthalmic disorders. Stakeholders are increasingly focusing on minimally invasive procedures, particularly endoscopic dacryocystorhinostomy (DCR), which offers reduced recovery times and minimal scarring compared to traditional external approaches. The integration of advanced imaging technologies such as high-resolution computed tomography and magnetic resonance dacryocystography has improved diagnostic accuracy, allowing for more tailored treatment plans. Furthermore, the rising geriatric population, which is more susceptible to nasolacrimal duct obstructions, remains a primary catalyst for market expansion across both developed and emerging economies.
- North America currently stands as the largest region by market share, attributed to its advanced healthcare infrastructure and high adoption of premium surgical technologies.
- The Asia Pacific region is identified as the fastest-growing market, fueled by improving healthcare access and an increasing volume of ophthalmic surgeries in India and China.
- Chronic dacryocystitis represents the largest segment by type, as the persistent nature of the condition necessitates long-term management and frequent surgical intervention.
- Hospitals remain the leading end-user segment, though ambulatory surgical centers are gaining ground due to the shift toward outpatient ophthalmic procedures.
Key Takeaways Dacryocystitis Market Size & Forecast
The dacryocystitis market is characterized by a steady growth trajectory, supported by constant innovations in lacrimal duct stents and pharmacological interventions. Market participants are prioritizing the development of localized antibiotic delivery systems to manage acute infections more effectively while reducing systemic side effects. Forecast data suggests that while surgical interventions provide the bulk of the market value, the diagnostic segment is poised for significant growth as early detection becomes a priority in preventing secondary complications such as orbital cellulitis. The competitive landscape is shifting toward strategic collaborations between medical device manufacturers and ophthalmology clinics to streamline the patient care pathway.
- The United States is the leading country globally, driven by high healthcare expenditure and a robust presence of key market players.
- Endoscopic DCR techniques are witnessing a higher adoption rate over external DCR due to better aesthetic outcomes and patient preference.
- Advancements in laser-assisted dacryocystorhinostomy are providing new avenues for market growth in the specialized ophthalmic surgery sector.
- Rising awareness regarding congenital dacryocystitis and its early management is boosting the pediatric ophthalmology segment.
- The integration of telemedicine in post-operative monitoring is enhancing patient compliance and clinical outcomes.
Dacryocystitis Market Drivers Analysis
The primary drivers for the dacryocystitis market include the rising incidence of nasolacrimal duct obstructions across diverse age groups and the technological leap in surgical instrumentation. As the global population ages, the physiological changes in the lacrimal drainage system become more prevalent, necessitating medical intervention. Additionally, the increasing availability of sophisticated diagnostic tools enables clinicians to differentiate between various lacrimal disorders with greater precision, leading to higher treatment rates.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Technological Advancements in Endoscopic Surgery | +2.1% | Global / Highly relevant in North America and Europe | 2025 - 2034 |
| Increasing Geriatric Population Base | +1.8% | Japan, Germany, United States | 2025 - 2034 |
| Rise in Prevalence of Congenital Nasolacrimal Duct Obstruction | +1.2% | Global / High impact in APAC | 2026 - 2030 |
| Higher Healthcare Spending in Emerging Markets | +1.1% | China, India, Brazil | 2027 - 2034 |
Dacryocystitis Market Restraints Analysis
Despite the positive growth outlook, the market faces restraints such as the high cost of specialized surgical procedures and a lack of skilled ophthalmologists in developing regions. Furthermore, the risk of post-operative complications and the high recurrence rate associated with certain types of lacrimal surgeries can deter patients from opting for elective procedures, particularly in cost-sensitive markets.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Endoscopic DCR Equipment | -1.5% | Low and Middle-Income Countries | 2025 - 2029 |
| Risk of Post-Surgical Scarring and Infection | -0.8% | Global | 2025 - 2034 |
Dacryocystitis Market Opportunities Analysis
The market presents substantial opportunities in the development of bio-absorbable stents and the expansion of specialized eye care clinics in under-penetrated rural areas. The move toward personalized medicine and the use of 3D printing for customized lacrimal implants represent futuristic growth frontiers that could redefine surgical standards and improve long-term patency rates in dacryocystorhinostomy patients.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Bio-absorbable Lacrimal Stents | +1.9% | Europe and North America | 2027 - 2034 |
| Expansion of Ophthalmic Infrastructure in APAC | +2.3% | India, Indonesia, Vietnam | 2026 - 2034 |
Dacryocystitis Market Challenges Impact Analysis
Key challenges include stringent regulatory approval processes for new medical devices and the ongoing shortage of specialized training for advanced dacryocystitis surgeries. Additionally, the competitive pressure from alternative non-surgical therapies and the need for standardized clinical protocols across different regions present hurdles for global market harmonization.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Regulatory Pathways for Implants | -1.2% | United States (FDA), European Union (MDR) | 2025 - 2030 |
| Shortage of Sub-specialized Oculoplastic Surgeons | -1.0% | Global / Particularly MEA | 2025 - 2034 |
Dacryocystitis Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the dacryocystitis market, covering therapeutic interventions, diagnostic modalities, and surgical procedures. The research focuses on the global landscape, providing a granular view of market dynamics, competitive benchmarking, and future growth projections from 2025 to 2034. It evaluates the impact of macro-economic factors and healthcare policy changes on market accessibility and adoption rates.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 777.2 Million |
| Market Forecast in 2034 | USD 1,348.2 Million |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Novartis AG, Teva Pharmaceutical Industries Ltd., Bausch Health Companies Inc., Pfizer Inc., Johnson & Johnson Services Inc., Santen Pharmaceutical Co., Ltd., Sun Pharmaceutical Industries Ltd., Alcon, AbbVie Inc. (Allergan), Lupin, Cipla Inc., Aurobindo Pharma, Zydus Group, Fresenius Kabi AG, Viatris Inc., Glenmark Pharmaceuticals, Amneal Pharmaceuticals LLC, Hikma Pharmaceuticals PLC. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The dacryocystitis market is segmented to provide a comprehensive understanding of the various factors influencing patient care and product demand. The type-based segmentation highlights the distinct management protocols required for acute versus chronic conditions. Treatment segmentation delves into the pharmacological and surgical landscapes, highlighting the move from conventional drug therapy to sophisticated surgical interventions that address the root cause of nasolacrimal duct obstruction.
- By Type:
- Acute Dacryocystitis
- Chronic Dacryocystitis
- By Diagnosis:
- Physical Examination
- Lacrimal Syringing
- Imaging (Computed Tomography, Magnetic Resonance Imaging)
- Dacryoscintigraphy
- By Treatment:
- Medications (Antibiotics, Corticosteroids, Non-steroidal Anti-inflammatory Drugs)
- Surgery (External Dacryocystorhinostomy, Endoscopic Dacryocystorhinostomy, Laser-Assisted Dacryocystorhinostomy)
- Lacrimal Stenting and Intubation
- By End-user:
- Hospitals
- Specialized Ophthalmic Clinics
- Ambulatory Surgical Centers
Regional Highlights
The regional analysis provides insights into the geographic distribution of market share and identifies high-growth zones. North America remains the dominant player due to high awareness levels and a mature reimbursement framework. Europe follows closely, with significant contributions from Germany, France, and the UK, where advanced surgical techniques are standard practice. The Asia Pacific region is expected to exhibit the highest growth rate during the forecast period.
- North America: The largest market share holder, with the United States leading in technological integration and clinical research in oculoplastics.
- Europe: Characterized by a strong emphasis on minimally invasive surgeries and a well-established network of public and private healthcare providers.
- Asia Pacific: The fastest-growing region, driven by large patient populations in India and China and expanding medical tourism for eye surgeries.
- Latin America: Growing at a steady pace as healthcare infrastructure improves in nations like Brazil and Mexico.
- Middle East and Africa: A developing market where growth is spurred by increasing investments in specialized healthcare centers and rising awareness of ocular health.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Dacryocystitis Market.- Novartis AG
- Teva Pharmaceutical Industries Ltd.
- Bausch Health Companies Inc.
- Pfizer Inc.
- Johnson & Johnson Services Inc.
- Santen Pharmaceutical Co., Ltd.
- Sun Pharmaceutical Industries Ltd.
- Alcon
- AbbVie Inc. (Allergan)
- Lupin
- Cipla Inc.
- Aurobindo Pharma
- Zydus Group
- Fresenius Kabi AG
- Viatris Inc.
- Glenmark Pharmaceuticals
- Amneal Pharmaceuticals LLC
- Hikma Pharmaceuticals PLC
Frequently Asked Questions
What is the primary cause of dacryocystitis mentioned in the market analysis?
The primary cause is the obstruction of the nasolacrimal duct, which leads to the accumulation of tears and subsequent bacterial infection in the lacrimal sac. This condition is prevalent among infants as a congenital issue and among older adults due to age-related physiological changes.
Which treatment segment holds the largest share in the dacryocystitis market?
The surgical segment, specifically dacryocystorhinostomy (DCR), holds the largest market share as it provides a definitive cure for chronic and recurrent dacryocystitis by creating a new drainage pathway between the lacrimal sac and the nasal cavity.
How is technology impacting the dacryocystitis market growth?
Technology is driving growth through the introduction of endoscopic and laser-assisted DCR, which reduce surgical trauma, minimize recovery time, and eliminate external scars. Advanced imaging tools also improve diagnostic precision, leading to higher success rates in treatment.
What region is expected to grow the fastest during the forecast period?
The Asia Pacific region is expected to be the fastest-growing market between 2025 and 2034, due to improving healthcare access, a rising middle-class population with higher disposable income, and government initiatives to reduce the burden of preventable blindness.
What are the key challenges for companies in this market?
Key challenges include navigating complex regulatory environments for new surgical devices, addressing the shortage of trained oculoplastic surgeons, and managing the high costs associated with advanced endoscopic equipment in price-sensitive regions.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
