Cotton Market
Cotton Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711069 | Published On : October 03, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Cotton Market Size
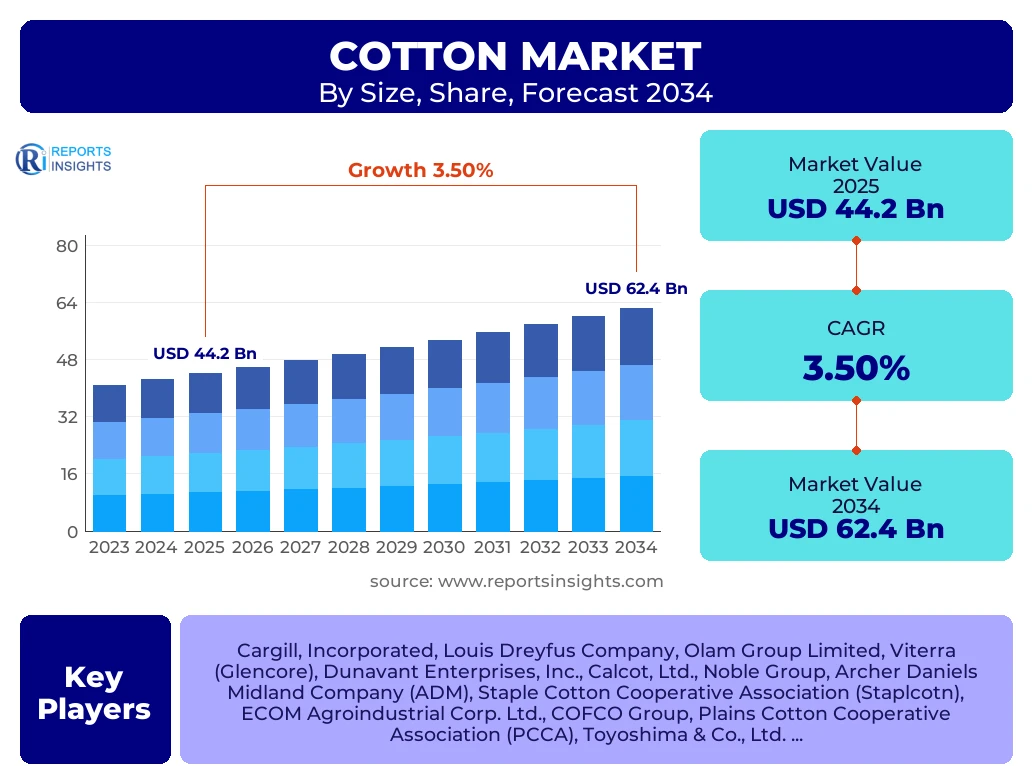
According to Reports Insights Consulting Pvt Ltd, The Cotton Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 3.5% between 2026 and 2034. The market is estimated at USD 45.8 Billion in 2026 and is projected to reach USD 62.4 Billion by the end of the forecast period in 2034.
Key Cotton Market Trends & Insights
The global cotton market is undergoing a significant transformation driven by the integration of sustainable agricultural practices and the rapid digitalization of the textile supply chain. As consumer preferences shift toward ethical fashion, the demand for Better Cotton Initiative (BCI) certified and organic cotton has surged, forcing producers to adopt transparent traceability systems. Market participants are increasingly focusing on the vertical integration of ginning and spinning operations to minimize logistical bottlenecks. Furthermore, the development of climate-resilient cotton varieties through advanced biotechnological interventions is becoming a critical strategy for mitigating the risks associated with unpredictable weather patterns in major producing regions such as the Mississippi Delta, the Indian subcontinent, and the Yangtze River basin.
Technological advancements in precision farming, including the use of satellite imagery and AI-driven soil moisture sensors, are optimizing yields while reducing input costs. The competitive landscape is characterized by strategic alliances between global commodity traders and local farming cooperatives to ensure a steady supply of high-quality staple fibers. Additionally, the rise of regional textile hubs in Southeast Asia and East Africa is reshaping global trade flows, as these regions emerge as prominent consumption centers for raw cotton, challenging the traditional dominance of established manufacturing powerhouses.
- Largest Region: Asia-Pacific remains the dominant region, accounting for over 55% of global production and consumption, led by India and China.
- Fastest Growing Region: Sub-Saharan Africa is projected to experience the highest growth rate due to expanding cultivation areas and increasing foreign direct investment in textile manufacturing.
- Largest Segment by Type: Upland Cotton continues to hold the largest market share, exceeding 85%, due to its versatility across apparel and industrial applications.
- Leading End-Use Segment: The apparel industry remains the primary driver of demand, specifically in the fast-fashion and denim sectors.
Key Takeaways Cotton Market Size & Forecast
The cotton market is anticipated to maintain a steady growth trajectory, supported by the rising demand for natural fibers in the garment and home textile sectors. While synthetic alternatives like polyester pose a threat, the inherent breathability and biodegradability of cotton provide it with a sustained competitive advantage in the premium and eco-conscious market segments. Strategic inventory management and the stabilization of global logistics are expected to reduce price volatility, providing a more predictable environment for long-term investments in ginning and processing infrastructure. Analysts suggest that the convergence of regenerative agriculture and circular fashion will define the market's evolution over the next decade.
- India is positioned as the world’s leading cotton producer, with government initiatives like the PM MITRA scheme boosting domestic value addition.
- The United States remains the most significant exporter of high-quality cotton, leveraging advanced harvesting technology and robust export credit programs.
- Sustainability Certification: Over 30% of the global cotton supply is expected to be under sustainability frameworks by 2030.
- Price Stability: Increased adoption of hedging instruments and futures contracts is moderating the impact of commodity price fluctuations on textile manufacturers.
Cotton Market Drivers Analysis
The primary growth engine for the cotton market is the burgeoning textile industry in emerging economies, coupled with a renewed global emphasis on natural, biodegradable materials. The expansion of middle-class populations in Asia and Africa has led to increased per capita fiber consumption, particularly in the apparel and home furnishing segments. Furthermore, government subsidies and minimum support price (MSP) mechanisms in leading producing nations provide a financial cushion to farmers, ensuring consistent acreage and production volumes.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Demand for Sustainable and Organic Textiles | +1.2% | Europe and North America | 2025-2034 |
| Expansion of Textile Manufacturing Hubs | +0.9% | Vietnam, Bangladesh, and India | 2026-2030 |
| Technological Innovations in Seed Biotechnology | +0.7% | United States and Brazil | 2025-2034 |
Cotton Market Restraints Analysis
Market growth is hindered by the escalating impact of climate change, characterized by frequent droughts and erratic rainfall, which directly affect crop yields and fiber quality. Additionally, the intense competition from low-cost synthetic fibers, such as polyester and nylon, remains a significant restraint, particularly in price-sensitive market segments. Regulatory pressures regarding water usage and pesticide application in cotton cultivation also pose operational challenges for producers in strictly regulated environments.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Climate Volatility and Water Scarcity | -0.8% | Central Asia and Australia | Ongoing |
| Competition from Synthetic Fiber Alternatives | -0.6% | Global | 2025-2034 |
Cotton Market Opportunities Analysis
The shift toward circular economy models presents substantial opportunities for the development of recycled cotton fibers, allowing brands to reduce their environmental footprint. There is also significant potential in the industrial application of cotton-based non-wovens for hygiene and medical products. Emerging markets in Africa offer untapped potential for large-scale mechanized cotton farming, which could significantly lower global production costs and diversify supply chains.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advancements in Mechanical Harvesting in Developing Markets | +1.1% | Africa and India | 2027-2034 |
| Growth in Eco-Friendly and Biodegradable Personal Care Products | +0.5% | China and Japan | 2026-2032 |
Cotton Market Challenges Impact Analysis
The primary challenge remains the volatility of global commodity prices, which is often influenced by geopolitical tensions and trade policy shifts. Furthermore, labor shortages and rising wage costs in traditional cotton-growing regions are forcing a transition toward expensive automation. Ensuring ethical labor practices across a highly fragmented global supply chain remains a complex challenge for multinational retailers and fashion houses.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Geopolitical Trade Barriers and Tariffs | -0.4% | US-China Trade Relations | 2025-2028 |
| Pest Resistance to Existing Transgenic Traits | -0.3% | India and Pakistan | 2026-2030 |
Cotton Market - Updated Report Scope
This comprehensive market analysis encompasses the entire cotton value chain, from seed development and cultivation to ginning, spinning, and final end-use applications. The report provides a granular evaluation of market dynamics across key geographic regions, highlighting the impact of technological integration and sustainability mandates. By examining both the raw commodity and processed fiber segments, this study offers a holistic view of the factors influencing price mechanisms, supply-demand equilibrium, and competitive positioning within the global textile landscape.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 44.2 Billion |
| Market Forecast in 2034 | USD 62.4 Billion |
| Growth Rate | 3.5% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Cargill, Incorporated, Louis Dreyfus Company, Olam Group Limited, Viterra (Glencore), Dunavant Enterprises, Inc., Calcot, Ltd., Noble Group, Archer Daniels Midland Company (ADM), Staple Cotton Cooperative Association (Staplcotn), ECOM Agroindustrial Corp. Ltd., COFCO Group, Plains Cotton Cooperative Association (PCCA), Toyoshima & Co., Ltd., Reinhart Corp, Namoi Cotton Limited, Gujarat State Co-operative Cotton Federation Ltd, Xinjiang Zhongtai Chemical Co., Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The global cotton market is segmented based on botanical type, staple length, and end-use application, reflecting the diverse requirements of the textile and industrial sectors. Upland cotton dominates the market due to its cost-effectiveness and adaptability, while Extra-Long Staple (ELS) varieties such as Pima and Egyptian cotton command a premium in the high-end luxury apparel segment. Segment-specific growth is increasingly tied to the functionality of the fiber, with home textiles and medical grade cotton showing significant resilience against economic fluctuations.
- By Type:
- Upland Cotton (Gossypium hirsutum)
- Extra-Long Staple (ELS) / Pima (Gossypium barbadense)
- Tree Cotton (Gossypium arboreum)
- Levant Cotton (Gossypium herbaceum)
- By Application:
- Apparel (Woven, Knitted, Denim)
- Home Textiles (Bedding, Towels, Curtains)
- Medical & Hygiene (Absorbent Cotton, Bandages, Wipes)
- Industrial (Tarpaulins, Tents, Bookbinding)
- By End-Use:
- Spinning Mills
- Weaving and Knitting Units
- Non-woven Fabric Manufacturers
Regional Highlights
The Asia-Pacific region maintains its status as the epicenter of the cotton market, driven by massive production volumes in India and China and a sophisticated downstream textile industry. India has recently emerged as the world's largest producer, benefiting from large-scale cultivation areas, while China remains the primary consumer of raw cotton to fuel its export-oriented garment industry. In North America, the United States continues to be a dominant force in the export market, utilizing highly mechanized farming techniques and rigorous quality grading standards to maintain a competitive edge.
- Asia-Pacific: Largest market share; India leads in production while Bangladesh and Vietnam lead in import growth for manufacturing.
- North America: The United States is the leading exporter, focusing on high-tech agricultural practices and sustainability labeling.
- Latin America: Brazil is a major global player, showing significant growth in cotton exports to Asian markets.
- Europe: High demand for organic and recycled cotton, driven by strict environmental regulations and consumer awareness.
- Africa: Rapidly emerging as a low-cost production hub with significant potential for yield improvement through technology transfer.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Cotton Market.- Cargill, Incorporated
- Louis Dreyfus Company
- Olam Group Limited
- Viterra (Glencore)
- Dunavant Enterprises, Inc.
- Calcot, Ltd.
- Noble Group
- Archer Daniels Midland Company (ADM)
- Staple Cotton Cooperative Association (Staplcotn)
- ECOM Agroindustrial Corp. Ltd.
- COFCO Group
- Plains Cotton Cooperative Association (PCCA)
- Toyoshima & Co., Ltd.
- Reinhart Corp
- Namoi Cotton Limited
- Gujarat State Co-operative Cotton Federation Ltd
- Xinjiang Zhongtai Chemical Co., Ltd.
- Allenberg Cotton Co.
- LDC Metals
Frequently Asked Questions
What is the current global market size of the cotton industry?
The global cotton market is estimated at USD 44.2 Billion in 2025 and is projected to grow to USD 62.4 Billion by 2034, driven by textile demand and sustainable fiber adoption.
Which country is the largest producer of cotton?
India is currently the world's largest producer of cotton, followed closely by China and the United States, supported by favorable climatic conditions and large-scale cultivation.
What are the major factors driving the demand for organic cotton?
Demand for organic cotton is driven by increasing consumer awareness of environmental issues, corporate sustainability goals of major fashion brands, and government regulations on pesticide use.
How is climate change affecting the cotton market?
Climate change impacts cotton through water scarcity, heat stress, and unpredictable weather patterns, which lead to yield fluctuations and higher production costs in key regions.
What are the key technological trends in cotton farming?
Key trends include the use of precision agriculture, AI-driven irrigation systems, drone-based crop monitoring, and the development of genetically modified seeds for pest resistance and drought tolerance.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted