Construction Films Market
Construction Films Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710870 | Published On : September 12, 2026 |
Format : 


 | Author : Jonathan Sikka
Construction Films Market Size
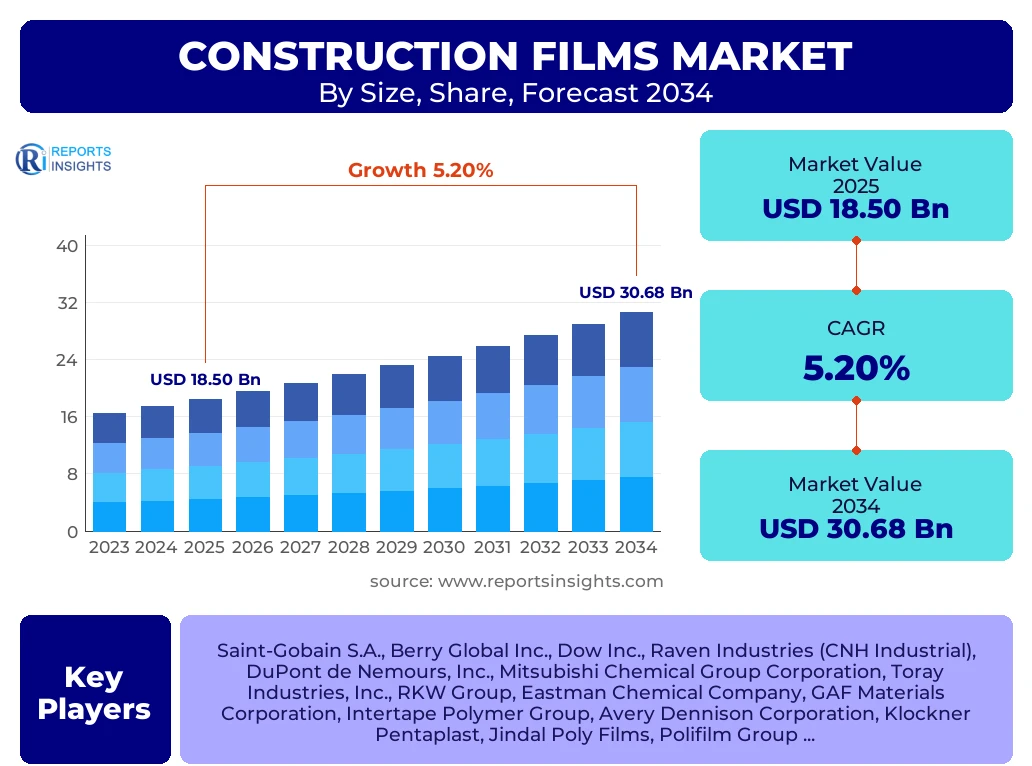
According to Reports Insights Consulting Pvt Ltd, The Construction Films Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.2% between 2026 and 2034. The market is estimated at USD 19.46 Billion in 2026 and is projected to reach USD 30.68 Billion by the end of the forecast period in 2034.
Key Construction Films Market Trends & Insights
The construction films market is undergoing a significant transformation driven by the global emphasis on energy-efficient building envelopes and the integration of advanced polymer technologies. Current research indicates that the demand for high-performance vapor barriers and gas membranes is escalating as building codes become more stringent regarding moisture control and indoor air quality. Furthermore, the industry is witnessing a pivot toward sustainable materials, with manufacturers increasingly investing in bio-based polyethylene and recycled resin formulations to align with circular economy goals. Digitalization in construction management is also influencing material selection, as contractors prioritize films with enhanced durability and ease of installation to reduce onsite labor costs and long-term maintenance liabilities.
- Asia Pacific represents the largest and fastest-growing regional market, fueled by massive infrastructure projects and rapid urbanization in India and China.
- The LDPE and LLDPE segment remains the largest in terms of market share due to its versatility, cost-effectiveness, and excellent moisture resistance properties.
- Residential construction continues to be the dominant end-use segment, particularly in emerging economies where housing demand is peaking.
- Increased adoption of perforated films for scaffolding protection is a notable trend in high-rise urban developments across Europe and North America.
Key Takeaways Construction Films Market Size & Forecast
The market trajectory for construction films is characterized by steady expansion, supported by the modernization of aging infrastructure in developed nations and the construction of new mega-cities in developing regions. Strategic analysis reveals that market players are focusing on product differentiation through multi-layer extrusion technologies that provide superior puncture resistance and thermal insulation. The forecast period is expected to see a rise in specialty films, such as those integrated with UV stabilizers and flame retardants, to meet specialized industrial requirements. Stakeholders are increasingly valuing transparency in the supply chain and environmental certifications, which are becoming critical benchmarks for competitive benchmarking in the global marketplace.
- China is the leading country globally, accounting for a significant portion of the total production and consumption of industrial-grade construction films.
- The shift toward green building certifications like LEED and BREEAM is a primary catalyst for the growth of high-performance moisture management films.
- Vapor barriers are the most critical application segment, essential for preventing structural damage and mold growth in modern building designs.
- Technological advancements in co-extrusion are allowing for thinner, stronger films, optimizing material usage and reducing transportation footprints.
Construction Films Market Drivers Analysis
The primary driver for the construction films market is the escalating global investment in infrastructure and residential housing. As governments across the globe initiate large-scale public works projects and housing schemes to accommodate growing populations, the requirement for protective and functional films has surged. Additionally, the implementation of stringent energy efficiency regulations necessitates the use of advanced vapor and air barriers to minimize thermal leakage, thereby driving the adoption of high-quality polymer films in the building envelope.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Infrastructure Development | +1.8% | India, China, Southeast Asia | 2025 - 2034 |
| Stringent Energy Efficiency Mandates | +1.5% | European Union, North America | 2026 - 2034 |
| Modernization of Aging Residential Buildings | +1.1% | United States, Germany, Japan | 2025 - 2030 |
Construction Films Market Restraints Analysis
The market faces significant restraints from the volatility of raw material prices, particularly petrochemical-derived resins like polyethylene and polypropylene. Fluctuations in crude oil prices directly impact the production costs of construction films, creating uncertainty for manufacturers and end-users alike. Moreover, increasing environmental concerns and regulations regarding plastic waste management pose a challenge to traditional non-biodegradable film products, requiring heavy investment in alternative material R and D.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Volatility | -0.9% | Global | 2025 - 2034 |
| Environmental Regulations on Plastics | -0.7% | Europe, North America | 2027 - 2034 |
Construction Films Market Opportunities Analysis
There is a burgeoning opportunity in the development and commercialization of biodegradable and compostable construction films. As the construction industry seeks to reduce its carbon footprint, films made from renewable resources or those with high recycled content are gaining traction. Furthermore, the expansion of the commercial sector in emerging markets, including retail hubs and office complexes, provides a fertile ground for the application of high-durability protective films and window insulation solutions.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Bio-based Polymers | +1.4% | Germany, Nordic Countries, Canada | 2026 - 2034 |
| Expansion in Middle Eastern Urban Projects | +1.2% | Saudi Arabia, UAE | 2025 - 2032 |
Construction Films Market Challenges Impact Analysis
One of the most pressing challenges is the intense competition from alternative building technologies, such as spray-applied weather barriers and advanced coating systems that claim to offer similar or superior protection with lower labor requirements. Additionally, maintaining quality control across fragmented supply chains in developing regions remains a hurdle for multinational companies seeking to standardize their product offerings globally while managing localized production costs.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Competition from Spray-applied Barriers | -0.6% | North America, Australia | 2025 - 2034 |
| Supply Chain Fragmentation | -0.4% | Southeast Asia, Africa | 2025 - 2028 |
Construction Films Market - Updated Report Scope
This comprehensive report provides an in-depth analysis of the global construction films landscape, covering material types, application areas, and end-use sectors across all major geographic regions. The scope includes historical data, current market valuations, and rigorous forecasting based on macroeconomic indicators and industry-specific drivers. The report also features a detailed competitive analysis of leading market participants and an evaluation of emerging technological trends that are set to redefine the industry over the next decade.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 18.50 Billion |
| Market Forecast in 2034 | USD 30.68 Billion |
| Growth Rate | 5.2% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Saint-Gobain S.A., Berry Global Inc., Dow Inc., Raven Industries (CNH Industrial), DuPont de Nemours, Inc., Mitsubishi Chemical Group Corporation, Toray Industries, Inc., RKW Group, Eastman Chemical Company, GAF Materials Corporation, Intertape Polymer Group, Avery Dennison Corporation, Klockner Pentaplast, Jindal Poly Films, Polifilm Group, Plastika Kritis S.A., Skymark Packaging, Layfield Group, Britpac, and Polythene UK. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The construction films market is segmented based on material chemistry, functional application, and the nature of the construction project. This granular segmentation allows stakeholders to identify high-growth niches, such as the rising demand for high-density polyethylene (HDPE) in heavy infrastructure projects versus the dominance of linear low-density polyethylene (LLDPE) in residential protective applications. The application-based segmentation further highlights the critical role of moisture management and environmental protection in modern architecture.
- By Material Type:
- LDPE and LLDPE: Preferred for flexibility and moisture resistance.
- HDPE: Utilized for high-strength applications like geomembranes and heavy-duty barriers.
- Polypropylene (PP): Gaining share in roofing underlayments and high-temperature environments.
- PVC: Used specifically for waterproofing and decorative window applications.
- PET: Valued for high tensile strength and thermal stability in specialty laminates.
- By Application:
- Vapor Barriers: Essential for protecting structures from internal and external humidity.
- Gas Membranes: Specialized films for radon and methane mitigation in brownfield sites.
- Scaffolding Films: Protective wraps for workers and environmental containment.
- Window Films: Solar control and security films for commercial glazing.
- Roofing Films: Underlayment and weather-resistant membranes.
- By End-Use:
- Residential: Driven by new housing starts and home renovations.
- Commercial: Includes retail, office buildings, and hospitality sectors.
- Industrial: Factories, warehouses, and energy facilities requiring robust protection.
- Infrastructure: Bridges, tunnels, and roadworks utilizing durable containment films.
Regional Highlights
- Asia Pacific: Holds the largest market share, with China and India leading consumption due to massive urbanization, large-scale infrastructure investments, and a robust manufacturing base for polymer resins.
- North America: A mature market focused on high-performance materials and stringent building codes. The United States is a key innovator in specialty vapor barriers and energy-efficient window films.
- Europe: Driven by sustainability mandates and the renovation of historic building stock. Germany and France are major markets for recycled-content films and advanced moisture management systems.
- Middle East and Africa: Experiencing rapid growth in the infrastructure segment, particularly in GCC countries where extreme weather conditions necessitate UV-stabilized and heat-resistant construction films.
- Latin America: Showing steady growth in the residential sector, with Brazil and Mexico emerging as key production hubs for regional distribution.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Construction Films Market.- Saint-Gobain S.A.
- Berry Global Inc.
- Dow Inc.
- Raven Industries (CNH Industrial)
- DuPont de Nemours, Inc.
- Mitsubishi Chemical Group Corporation
- Toray Industries, Inc.
- RKW Group
- Eastman Chemical Company
- GAF Materials Corporation
- Intertape Polymer Group
- Avery Dennison Corporation
- Klockner Pentaplast
- Jindal Poly Films
- Polifilm Group
- Plastika Kritis S.A.
- Skymark Packaging
- Layfield Group
- Britpac
- Polythene UK
Frequently Asked Questions
What is the projected growth of the Construction Films Market through 2034?
The Construction Films Market is expected to grow at a CAGR of 5.2% from 2025 to 2034, reaching a projected valuation of USD 30.68 Billion by the end of the forecast period.
Which material type dominates the Construction Films Market?
The LDPE and LLDPE segment currently dominates the market due to its excellent balance of cost-efficiency, moisture resistance, and flexibility across various construction applications.
What are the main drivers for the adoption of construction films in North America and Europe?
In North America and Europe, the primary drivers are stringent building energy efficiency regulations (such as LEED standards) and the high demand for advanced vapor and gas barriers in building envelopes.
Who are the leading players in the global Construction Films Market?
Top market players include Saint-Gobain, Berry Global, Dow, Raven Industries, and DuPont, which are recognized for their extensive product portfolios and focus on technological innovation.
How is sustainability impacting the Construction Films Market?
Sustainability is driving the development of films with higher recycled content and bio-based polymers, as well as the creation of thinner but stronger films that reduce overall material waste and environmental impact.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted