Computer Aided Engineering Market
Computer Aided Engineering Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711160 | Published On : October 13, 2026 |
Format : 


 | Author : Ashraf Shehata
Computer Aided Engineering Market Size
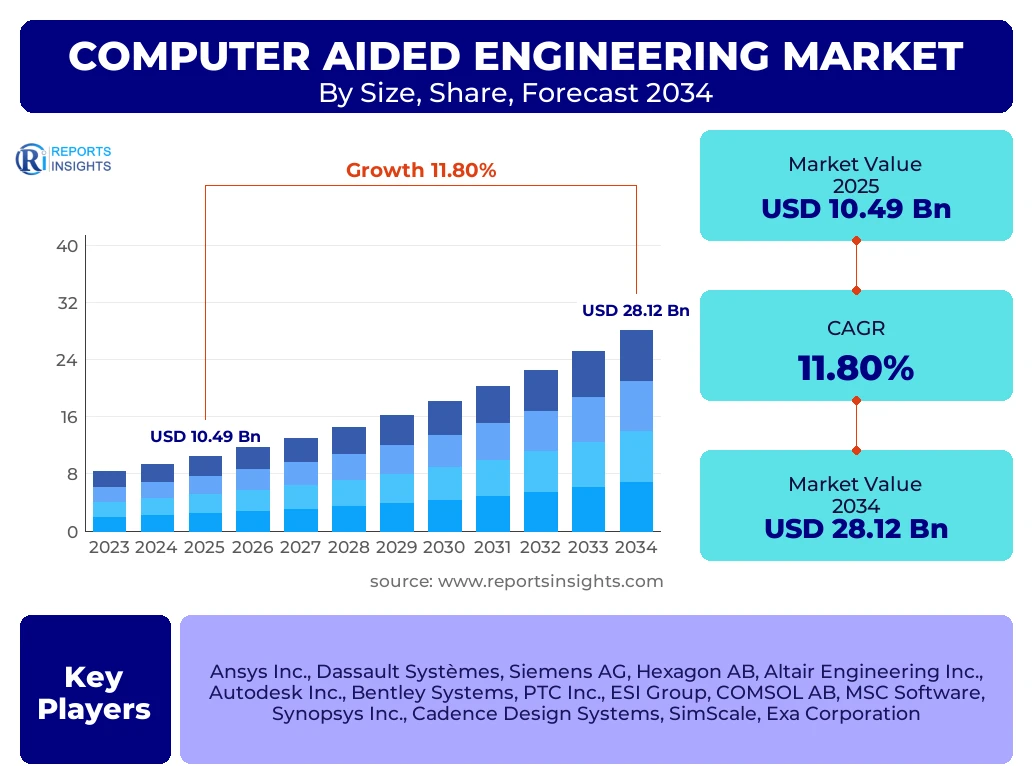
According to Reports Insights Consulting Pvt Ltd, The Computer Aided Engineering Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 11.8% between 2025 and 2034. The market is estimated at USD 11.73 Billion in 2026 and is projected to reach USD 28.12 Billion by the end of the forecast period in 2034.
Key Computer Aided Engineering Market Trends & Insights
The global Computer Aided Engineering (CAE) market is undergoing a significant transformation driven by the integration of Artificial Intelligence (AI) and Machine Learning (ML) into simulation workflows. Users are increasingly seeking regional insights into how cloud-native CAE platforms are democratizing high-performance computing (HPC) for small and medium-sized enterprises. Modern trends indicate a pivot from traditional validation-only simulation toward generative design and predictive maintenance, where CAE tools are used to simulate thousands of design iterations autonomously. Competitive benchmarking shows that market leaders are focusing on multi-physics simulation capabilities to address the increasing complexity of smart, connected products in the IoT era.
- Largest Region: North America remains the largest regional market due to early adoption of advanced manufacturing technologies and a robust aerospace and defense sector.
- Fastest Growing Region: Asia-Pacific is the fastest-growing region, fueled by rapid industrialization in China and India and the expansion of the automotive and electronics manufacturing hubs.
- Largest Segment by Share: The Finite Element Analysis (FEA) segment currently holds the largest market share owing to its extensive application in structural and thermal analysis across various industries.
- Growth Trend: The Cloud-based deployment segment is witnessing the highest growth rate as companies move away from capital-intensive on-premise infrastructure to scalable, subscription-based models.
Key Takeaways Computer Aided Engineering Market Size & Forecast
Market analysts and enterprise stakeholders are focusing on the long-term viability of simulation-driven design as a means to reduce physical prototyping costs and accelerate the time-to-market. The forecast suggests that the automotive sector will continue to be a primary driver for CAE adoption, specifically in the development of electric vehicles (EVs) and autonomous driving systems. Additionally, the shift toward sustainable manufacturing is pushing firms to use CAE for optimizing material usage and energy efficiency, further stabilizing the market’s upward trajectory through 2034.
- Leading Country: The United States leads the market in terms of value, supported by high R&D investments and the presence of major CAE software vendors.
- Dominant End-Use Industry: The Automotive industry is the primary consumer of CAE solutions, utilizing simulation for crash testing, aerodynamics, and battery thermal management.
- Emerging Technology: Digital Twin technology is becoming a critical component of the CAE ecosystem, allowing for real-time simulation and monitoring of physical assets throughout their lifecycle.
- Market Stability: Increasing demand for high-fidelity simulations in the medical device and biotechnology sectors provides a new, high-growth revenue stream for market participants.
Computer Aided Engineering Market Drivers Analysis
The primary driver for the CAE market is the urgent need for industrial manufacturers to reduce product development cycles and minimize the costs associated with physical prototyping. As global competition intensifies, companies are turning to advanced simulation tools to identify design flaws early in the development phase, thereby avoiding expensive recalls and engineering changes later in the process. Furthermore, the rising complexity of modern engineering systems, particularly in the aerospace and automotive sectors, necessitates the use of multi-physics simulation to ensure safety and performance standards.
Another significant driver is the rapid evolution of the Electric Vehicle (EV) market. The transition from internal combustion engines to electric powertrains requires specialized simulation for battery chemistry, thermal management, and electromagnetic interference. This specialized demand is pushing CAE vendors to develop more niche, high-accuracy tools. Additionally, the integration of CAE with the Internet of Things (IoT) allows for the creation of digital twins, which provides manufacturers with continuous data-driven insights into product performance under real-world conditions.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Increased Demand for EV and Autonomous Vehicle Simulation | +3.2% | Global (China/USA Leading) | 2025 - 2034 |
| Democratization of HPC via Cloud-Based CAE Platforms | +2.8% | Europe and North America | 2026 - 2030 |
| Integration of AI and Generative Design Features | +2.1% | Global | 2027 - 2034 |
Computer Aided Engineering Market Restraints Analysis
Despite the growth, the CAE market faces restraints such as the high cost of software licensing and the substantial investment required for the high-performance computing hardware necessary for complex simulations. For small and mid-sized enterprises (SMEs), these upfront costs can be a significant barrier to entry, often leading them to rely on simplified or less accurate design methods. Furthermore, the lack of a highly skilled workforce capable of operating sophisticated CAE software and interpreting complex simulation results remains a critical bottleneck for widespread adoption.
Data security concerns associated with cloud-based CAE deployments also act as a restraint, particularly in sensitive sectors like defense and aerospace. Companies are often hesitant to upload proprietary design data to the cloud, fearing intellectual property theft or data breaches. Additionally, the lack of standardized data formats between different CAD and CAE platforms creates interoperability issues, leading to data loss or inaccuracies during the translation process, which can delay project timelines and increase costs.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Licensing Costs and Maintenance Fees | -1.5% | Emerging Markets (India/Brazil) | 2025 - 2034 |
| Security Risks in Public Cloud Simulation Environments | -0.8% | Global (Defense Focused) | 2025 - 2029 |
Computer Aided Engineering Market Opportunities Analysis
The shift toward additive manufacturing (3D printing) presents a massive opportunity for the CAE market. Traditional design tools are often insufficient for the complex geometries made possible by 3D printing. CAE tools optimized for additive manufacturing can help engineers simulate the printing process itself, predicting potential distortions and internal stresses before the part is even built. This synergy is expected to create a new niche for specialized CAE software tailored to structural optimization and lattice design.
Moreover, the expansion of CAE into non-traditional industries such as healthcare and biotechnology offers significant growth potential. Simulation is increasingly used to model the human body for the development of personalized medical implants, cardiovascular stents, and drug delivery systems. As regulatory bodies like the FDA begin to accept simulation data as valid evidence in clinical trials, the adoption of CAE in the medical field is expected to surge, providing vendors with a highly profitable and steady revenue stream.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into Biomedical and Healthcare Simulation | +2.4% | North America and Europe | 2026 - 2034 |
| Development of Specialized Additive Manufacturing CAE Tools | +1.9% | Germany and Japan | 2025 - 2032 |
Computer Aided Engineering Market Challenges Impact Analysis
One of the primary challenges in the CAE market is the maintenance of data integrity across fragmented multi-software environments. In many large-scale engineering projects, different teams use different simulation tools for thermal, structural, and fluid analysis. Ensuring that these disparate models communicate effectively and maintain a single source of truth is a constant hurdle. This fragmentation often leads to engineering silos, which can result in inconsistent design data and project delays.
Another challenge is the rapid pace of technological change. As AI and ML become more integrated into CAE, vendors must constantly update their legacy systems to remain competitive. This requires significant R&D investment and can alienate existing users who are accustomed to traditional workflows. Furthermore, the challenge of validating AI-generated designs remains, as engineers must ensure that the "black box" algorithms of ML-driven CAE are producing results that are physically sound and meet safety regulations.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Interoperability and Data Translation Issues | -1.2% | Global | 2025 - 2034 |
| Shortage of Certified Simulation Experts | -1.0% | Global | 2025 - 2030 |
Computer Aided Engineering Market - Updated Report Scope
This report provides a granular analysis of the global Computer Aided Engineering market, covering technological advancements, competitive landscapes, and regulatory frameworks across major geographies. The scope includes a detailed breakdown of software types, deployment modes, and end-use industries, providing stakeholders with the actionable intelligence needed to navigate the evolving simulation-driven design ecosystem.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 10.49 Billion |
| Market Forecast in 2034 | USD 28.12 Billion |
| Growth Rate | 11.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Ansys Inc., Dassault Systèmes, Siemens AG, Hexagon AB, Altair Engineering Inc., Autodesk Inc., Bentley Systems, PTC Inc., ESI Group, COMSOL AB, MSC Software, Synopsys Inc., Cadence Design Systems, SimScale, Exa Corporation |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Computer Aided Engineering market is segmented based on analysis type, deployment model, and end-use industry. Finite Element Analysis (FEA) continues to dominate the type segment due to its versatility in solving complex structural problems. However, Computational Fluid Dynamics (CFD) is seeing rapid growth in the aerospace and automotive sectors for optimizing fuel efficiency and cooling systems. The shift from on-premise to cloud deployment is perhaps the most significant structural change in the market, enabling real-time collaboration and access to massive computing power without the need for local hardware maintenance.
- By Analysis Type:
- Finite Element Analysis (FEA)
- Computational Fluid Dynamics (CFD)
- Multibody Dynamics
- Electromagnetic Analysis
- Optimization & Simulation
- By Deployment Model:
- On-premise
- Cloud-based (SaaS/Public/Private)
- By End-Use Industry:
- Automotive (EV, AV, Conventional)
- Aerospace & Defense
- Electrical & Electronics
- Medical Devices & Healthcare
- Industrial Equipment
- Energy & Materials
Regional Highlights
- North America: The largest market share holder, dominated by the United States. High concentration of aerospace firms and leading software vendors drives continuous innovation.
- Europe: A mature market with strong growth in Germany and France, primarily driven by the automotive industry’s transition to green energy and rigorous safety standards.
- Asia-Pacific: The fastest-growing region. Massive manufacturing investments in China, Japan, and South Korea, coupled with a booming electronics sector, are creating high demand for CAE tools.
- Latin America: Steady growth observed in Brazil and Mexico as they expand their automotive manufacturing capacities for export.
- Middle East & Africa: Emerging demand in the energy and construction sectors, particularly for structural analysis in large-scale infrastructure projects.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Computer Aided Engineering Market.- Ansys Inc.
- Dassault Systèmes
- Siemens AG
- Hexagon AB (MSC Software)
- Altair Engineering Inc.
- Autodesk Inc.
- Bentley Systems
- PTC Inc.
- ESI Group
- COMSOL AB
- Synopsys Inc.
- Cadence Design Systems
- SimScale
- Exa Corporation
- Beta CAE Systems
- Dlubal Software
- Midas IT
Frequently Asked Questions
What is the projected growth rate of the Computer Aided Engineering market?
The Computer Aided Engineering (CAE) market is expected to grow at a CAGR of 11.8% from 2025 to 2034, driven by the shift toward digital manufacturing and the integration of AI-driven simulation tools.
Which industry is the largest consumer of CAE software?
The automotive industry is currently the largest consumer of CAE software, utilizing it for crashworthiness, aerodynamics, and the development of electric vehicle battery systems.
How is cloud computing impacting the CAE market?
Cloud computing is democratizing the CAE market by providing scalable access to high-performance computing (HPC) resources on a pay-per-use basis, significantly reducing the entry barrier for small and medium-sized enterprises.
What are the main differences between FEA and CFD in the CAE market?
Finite Element Analysis (FEA) is primarily used for structural and thermal stress analysis, while Computational Fluid Dynamics (CFD) is focused on simulating fluid flow, heat transfer, and chemical reactions.
Which region offers the most growth opportunities for CAE vendors?
Asia-Pacific offers the most significant growth opportunities due to rapid industrialization, the rise of domestic manufacturing hubs in China and India, and increasing government support for high-tech industries.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
