Engineered Foam Market
Engineered Foam Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711744 | Published On : November 15, 2026 |
Format : 


 | Author : Ashraf Shehata
Engineered Foam Market Size
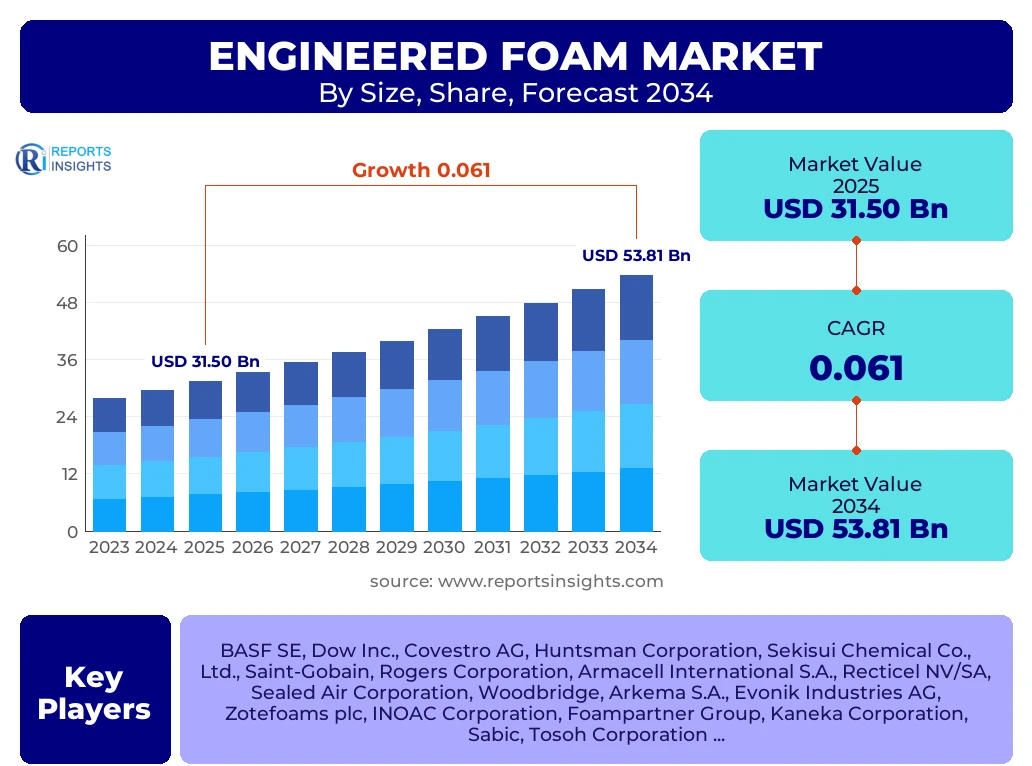
According to Reports Insights Consulting Pvt Ltd, The Engineered Foam Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.1% between 2025 and 2034. The market is estimated at USD 33.42 Billion in 2026 and is projected to reach USD 53.81 Billion by the end of the forecast period in 2034.
Key Engineered Foam Market Trends & Insights
The global engineered foam landscape is currently undergoing a transformative shift driven by the dual imperatives of high-performance material science and stringent environmental sustainability regulations. Modern industrial applications increasingly demand foams that offer superior thermal stability, acoustic dampening, and vibration isolation while maintaining a low carbon footprint. Research and development efforts are heavily concentrated on the synthesis of bio-based polyols and the implementation of advanced CO2 blowing technologies to mitigate the environmental impact of traditional petroleum-based foaming processes. Furthermore, the rapid expansion of the electric vehicle (EV) sector has catalyzed the demand for specialized flame-retardant and thermally conductive foams used in battery enclosures and power electronics. Competitive benchmarking reveals that market leaders are pivoting toward vertical integration to secure raw material supplies, such as isocyanates and polyols, while simultaneously investing in chemical recycling technologies to address the end-of-life challenges associated with thermoset foam products.
- Largest Region: Asia-Pacific remains the dominant global force, accounting for over 42% of the total market share, fueled by massive manufacturing hubs in China, India, and Southeast Asia.
- Fastest Growing Region: Asia-Pacific is also projected to be the fastest-growing region, with an anticipated CAGR of 6.8% through 2034, driven by rapid urbanization and infrastructure development.
- Largest Material Segment: Polyurethane (PU) foams continue to hold the largest market share due to their exceptional versatility across the automotive, construction, and bedding industries.
- High-Growth Application: The Medical and Healthcare segment is emerging as a critical growth vertical, particularly for specialized reticulated foams used in advanced wound care and orthopedic applications.
- Strategic Trend: Adoption of circular economy models and the transition from HFC-based blowing agents to low-GWP (Global Warming Potential) alternatives like Hydrofluoroolefins (HFOs).
Key Takeaways Engineered Foam Market Size & Forecast
Analyzing the long-term trajectory of the engineered foam market indicates a robust recovery and expansion phase following global supply chain stabilization. Stakeholders are focusing on the convergence of material durability and lightweighting, which is essential for meeting fuel efficiency standards in the aerospace and automotive sectors. The market forecast reflects a significant uptick in demand for rigid foams within the building and construction sector as global energy codes become more rigorous, requiring superior R-value insulation materials. Additionally, the proliferation of e-commerce has sustained a high demand for protective packaging solutions that utilize expanded polystyrene (EPS) and polyethylene (PE) foams to minimize shipping damage. The integration of digital manufacturing and 3D printing with foam materials is also beginning to create niche opportunities for customized high-precision components in specialized industrial sectors.
- Dominant Country: China represents the largest single-country market, serving as both a massive producer and consumer of engineered foams for consumer electronics and automotive manufacturing.
- Key Growth Lever: The transition to Electric Vehicles (EVs) requires advanced foam solutions for NVH (Noise, Vibration, and Harshness) reduction and battery thermal management, providing a massive tailwind for the specialty foam segment.
- Sustainability Impact: Regulations such as the EU Green Deal are forcing a shift toward recyclable and biodegradable foam variants, significantly impacting material selection strategies for global manufacturers.
- Infrastructure Demand: Massive government spending on smart city projects and energy-efficient building renovations in North America and Europe is securing steady demand for high-performance rigid insulation foams.
- Supply Chain Dynamics: Strategic shifts toward localizing production to reduce logistics costs and lead times are becoming a standard operational procedure for tier-1 foam suppliers.
Engineered Foam Market Drivers Analysis
The primary catalysts for the engineered foam market are rooted in the global drive for energy efficiency and the technical requirements of modern transportation. In the construction industry, the implementation of stringent building energy ratings necessitates the use of high-performance insulation materials that can provide long-term thermal resistance and structural integrity. Simultaneously, the automotive and aerospace industries are undergoing a massive "lightweighting" revolution to improve fuel economy and extend the range of electric batteries. Engineered foams, with their high strength-to-weight ratios, are indispensable in this transition. Furthermore, the rise of the global middle class in emerging economies has led to increased consumption of premium consumer goods, such as high-end furniture and electronics, both of which utilize engineered foams for comfort and protection.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Electric Vehicle (EV) Production | +1.8% | Global (Strongest in China & Germany) | 2025 - 2034 |
| Strict Energy Efficiency Regulations in Construction | +1.5% | North America & European Union | 2025 - 2030 |
| Growth in Cold Chain Logistics for Pharmaceuticals | +1.2% | Global (Strongest in India & Brazil) | 2026 - 2034 |
| Advancements in Aerospace Interior Comfort | +0.9% | United States & France | 2027 - 2034 |
Engineered Foam Market Restraints Analysis
Despite robust growth prospects, the market faces significant headwinds from volatile raw material pricing and increasingly stringent environmental mandates. The production of many engineered foams relies heavily on petrochemical derivatives, such as benzene, toluene, and propylene, which are subject to global oil price fluctuations. These price instabilities can squeeze the profit margins of foam converters and end-users. Additionally, the environmental concerns surrounding the disposal of non-biodegradable foams and the emissions of Volatile Organic Compounds (VOCs) during the manufacturing process have led to a complex regulatory landscape that increases compliance costs for manufacturers.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fluctuating Costs of Crude Oil & Feedstocks | -1.2% | Global | Continuous |
| Strict Regulations on VOC Emissions | -0.8% | Europe & North America | 2025 - 2034 |
| Challenges in Recycling Cross-linked Foams | -0.5% | Developed Economies | 2026 - 2034 |
Engineered Foam Market Opportunities Analysis
The evolving landscape presents significant opportunities in the development of "green" chemistry and specialty medical foams. As consumers and corporations prioritize sustainability, there is a burgeoning market for bio-based foams derived from soy, castor, or CO2-based polyols. These materials offer a lower carbon footprint while maintaining comparable performance to traditional foams. Furthermore, the aging global population is driving demand for advanced medical-grade foams used in pressure-relieving mattresses, prosthetic padding, and advanced wound dressings. The integration of antimicrobial properties into these foams represents a high-value niche that is currently underserved.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Bio-based and Biodegradable Foams | +2.1% | European Union & United States | 2026 - 2034 |
| Medical Grade Foams for Aging Population | +1.4% | Japan, Germany, & United States | 2025 - 2034 |
| Smart Foams with Embedded Sensors | +0.7% | South Korea & Taiwan | 2028 - 2034 |
Engineered Foam Market Challenges Impact Analysis
One of the most persistent challenges in the engineered foam sector is the technical difficulty of achieving high performance without the use of hazardous chemicals. Traditional flame retardants and blowing agents are often under scrutiny for their toxicological profiles. Replacing these with safer alternatives while maintaining the foam's fire safety ratings and physical properties is a complex engineering task. Moreover, the fragmented nature of the global supply chain, coupled with geopolitical tensions, can lead to localized shortages of critical chemical precursors, disrupting production schedules and increasing lead times for high-precision industrial projects.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Replacement of Halogenated Flame Retardants | -0.9% | Global (High in Electronics Sector) | 2025 - 2030 |
| Geopolitical Disruptions in Chemical Supply Chains | -0.7% | Global | Continuous |
| High Initial Investment for Advanced Foaming Tech | -0.4% | Emerging Markets | 2025 - 2034 |
Engineered Foam Market - Updated Report Scope
The scope of this comprehensive report encompasses a detailed quantitative and qualitative analysis of the global engineered foam market across various material types, forms, and end-use industries. It provides a granular look at the competitive landscape, identifying key strategic moves such as mergers, acquisitions, and technology licensing agreements that are shaping the future of the industry. The analysis extends to the evaluation of raw material trends, regulatory shifts, and technological breakthroughs that influence market dynamics. By providing a 10-year forecast, the report assists stakeholders in identifying long-term growth pockets and potential risks associated with shifting consumer preferences and industrial requirements.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 31.50 Billion |
| Market Forecast in 2034 | USD 53.81 Billion |
| Growth Rate | 6.1% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, Dow Inc., Covestro AG, Huntsman Corporation, Sekisui Chemical Co., Ltd., Saint-Gobain, Rogers Corporation, Armacell International S.A., Recticel NV/SA, Sealed Air Corporation, Woodbridge, Arkema S.A., Evonik Industries AG, Zotefoams plc, INOAC Corporation, Foampartner Group, Kaneka Corporation, Sabic, Tosoh Corporation, and Nitto Denko Corporation. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The engineered foam market is characterized by a diverse range of materials tailored for specific industrial functionalities. The segmentation is primarily driven by the physical properties required by the end-use application, such as flexibility, rigidity, or resistance to environmental factors. Polyurethane remains the most widely used material due to its adaptability, while Polystyrene is preferred in rigid insulation and packaging. Each segment is evolving under the influence of technological advancements, such as the development of cross-linked polyethylene foams for high-impact absorption and the use of specialty PVC foams for marine and wind energy applications. The following list outlines the core segments analyzed in this report:
- By Material Type:
- Polyurethane (PU): Dominant in furniture, automotive, and construction.
- Polystyrene (PS): Key for EPS and XPS insulation boards.
- Polyethylene (PE): High demand in protective packaging and sports equipment.
- Polyvinyl Chloride (PVC): Specialized use in marine cores and wind blades.
- Polypropylene (PP): Growing use in automotive interior components.
- Specialty Foams: Including Melamine, Silicone, and Polyimide foams for high-temp applications.
- By Form:
- Flexible Foams: Used in seating, bedding, and acoustic dampening.
- Rigid Foams: Essential for structural insulation and cold chain storage.
- Spray Foams: High-growth segment in residential and commercial building retrofitting.
- By End-Use Industry:
- Automotive: NVH solutions, seating, and battery protection.
- Aerospace & Defense: Lightweight interior panels and cryo-insulation.
- Building & Construction: Roof and wall insulation, pipe lagging.
- Medical & Healthcare: Orthotics, wound care, and specialized diagnostics.
- Packaging: High-value electronics and fragile goods protection.
- Consumer Goods: Bedding, furniture, and footwear.
Regional Highlights
The regional distribution of the engineered foam market reflects the global manufacturing landscape and the uneven adoption of environmental regulations. Asia-Pacific is the undeniable leader, supported by the massive industrial output of China, which acts as a global supplier for both foam raw materials and finished foam products. India is also emerging as a significant market due to its expanding automotive sector and government-led infrastructure projects. In North America, the market is driven by high-value applications in the medical and aerospace sectors, alongside a strong focus on high-performance building insulation in the United States and Canada. Europe is the epicenter of sustainability-driven innovation, where the demand for bio-based and recyclable foams is highest due to strict EU directives. Latin America and the MEA regions are experiencing steady growth, primarily driven by the expansion of the construction and food packaging industries in countries like Brazil, Mexico, and the GCC nations.
- Asia-Pacific (APAC): The largest and fastest-growing region, holding over 40% of the market share. China and India are the primary growth engines, particularly in the consumer electronics and automotive sectors.
- North America: A major hub for technological innovation in specialty foams. The U.S. market is heavily influenced by the aerospace, defense, and high-tech medical sectors.
- Europe: Leading the world in the adoption of sustainable foam solutions and low-GWP blowing agents. Germany is the regional powerhouse, specifically in automotive and industrial foam applications.
- Latin America: Growth is concentrated in Brazil and Mexico, focusing on the packaging and automotive manufacturing clusters.
- Middle East & Africa (MEA): Demand is primarily driven by the construction sector and the need for high-performance insulation in extreme climates.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Engineered Foam Market.- BASF SE
- Dow Inc.
- Covestro AG
- Huntsman Corporation
- Sekisui Chemical Co., Ltd.
- Saint-Gobain
- Rogers Corporation
- Armacell International S.A.
- Recticel NV/SA
- Sealed Air Corporation
- Woodbridge
- Arkema S.A.
- Evonik Industries AG
- Zotefoams plc
- INOAC Corporation
- Foampartner Group
- Kaneka Corporation
- Sabic
- Tosoh Corporation
- Nitto Denko Corporation
Frequently Asked Questions
Detailed analysis of common stakeholder inquiries regarding market dynamics, technological shifts, and investment opportunities in the Engineered Foam sector.
What are the primary drivers for the growth of the Engineered Foam market?
The growth is primarily driven by the increasing demand for lightweight and energy-efficient materials in the automotive and aerospace sectors. Additionally, stringent building energy codes globally are boosting the demand for high-performance rigid insulation foams in the construction industry.
Which material segment currently dominates the Engineered Foam market?
Polyurethane (PU) foams currently dominate the market due to their extreme versatility. They can be formulated into flexible, rigid, or spray forms, making them suitable for a wide range of applications from furniture cushioning to high-performance industrial insulation.
How is the move toward sustainability affecting foam manufacturers?
Sustainability is forcing a shift toward bio-based raw materials and the development of chemical recycling processes for thermoset foams. Manufacturers are also transitioning to blowing agents with zero ozone depletion potential and low global warming potential to comply with environmental regulations.
What region offers the most significant growth opportunities for the next decade?
Asia-Pacific offers the most significant growth opportunities due to rapid industrialization, the presence of major automotive hubs, and increasing government investments in infrastructure. China and India are the key markets within this region.
What are the main technical challenges in the production of engineered foams?
The main challenges include maintaining high performance while eliminating hazardous chemicals like halogenated flame retardants, managing the volatility of raw material costs, and developing efficient end-of-life recycling solutions for complex foam structures.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
