Compostable Food Service Disposables Market
Compostable Food Service Disposables Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711726 | Published On : November 13, 2026 |
Format : 


 | Author : Hameer Thakur
Compostable Food Service Disposables Market Size
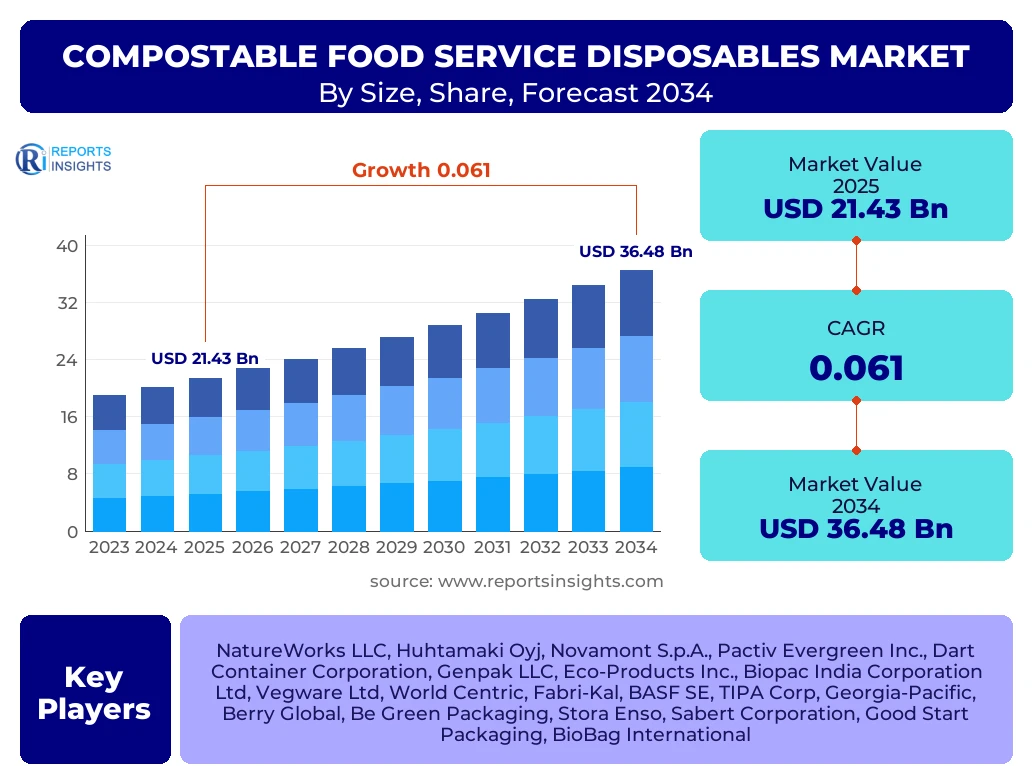
According to Reports Insights Consulting Pvt Ltd, The Compostable Food Service Disposables Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.1% between 2025 and 2034. The market is estimated at USD 22.74 Billion in 2026 and is projected to reach USD 36.48 Billion by the end of the forecast period in 2034.
The global shift toward sustainable food packaging solutions is a primary catalyst for this market expansion. As regulatory frameworks increasingly penalize the use of single-use plastics, enterprises are pivoting toward compostable alternatives that align with circular economy principles. This growth is further supported by advancements in material science, particularly in the refinement of Polylactic Acid (PLA) and bagasse-based products, which offer functional parity to traditional polymers while ensuring complete biodegradability under industrial composting conditions.
The valuation reflects a robust transition within the quick-service restaurant (QSR) and catering sectors, where high-volume consumption of disposables necessitates a transition to environmentally benign materials. Strategic investments by key packaging manufacturers to scale up production capacities and optimize supply chains are expected to reduce the price gap between compostable and conventional products, thereby accelerating adoption rates across both developed and emerging economies during the forecast window.
Key Compostable Food Service Disposables Market Trends & Insights
The compostable food service disposables market is undergoing a significant transformation driven by consumer demand for transparency and corporate sustainability mandates. Modern users are increasingly questioning the origin of packaging materials and the viability of disposal routes, leading to a rise in "soil-to-soil" product lifecycles. Furthermore, competitive benchmarking reveals that industry leaders are focusing on multi-functional barrier coatings that prevent moisture and oil seepage without compromising the compostability of the substrate. Regional insights indicate that while Europe remains a pioneer in regulatory compliance, the Asia-Pacific region is emerging as a manufacturing powerhouse for bio-based raw materials.
- Largest Region: North America remains the largest market by revenue share, driven by stringent state-level bans on polystyrene and a highly developed commercial composting infrastructure.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR, fueled by rapid urbanization, expanding food delivery sectors in India and China, and new government initiatives targeting plastic waste reduction.
- Largest Product Segment: Plates and trays currently hold the largest market share due to their high consumption frequency in institutional catering and large-scale public events.
- Dominant Material Segment: Paper and paperboard composites lead the material segment, though bagasse (sugarcane fiber) is gaining ground rapidly due to its superior thermal properties and lower carbon footprint during production.
Key Takeaways Compostable Food Service Disposables Market Size & Forecast
The market forecast indicates a steady upward trajectory, underpinned by the integration of compostable solutions into mainstream retail and hospitality operations. Stakeholders are focusing on the total cost of ownership and the logistical benefits of standardized composting protocols. Analysis of user inquiries suggests a high interest in the certification standards, such as ASTM D6400 and EN 13432, which serve as benchmarks for product legitimacy in an increasingly scrutinized marketplace. The forecast also highlights a move toward specialized end-use applications, including heat-resistant cutlery and leak-proof clamshells designed specifically for the delivery economy.
- Global Market Maturity: The market is transitioning from a niche environmental segment to a core component of the global packaging industry.
- Leading Country (USA): The United States leads in the adoption of compostable PLA-based cups and cutlery, supported by a growing network of industrial composting facilities.
- Material Innovation: Mushroom-based packaging and seaweed-derived coatings are emerging as high-potential disruptive technologies that could reshape the market by 2030.
- Institutional Demand: Educational institutions and corporate campuses are the primary early adopters, frequently mandating 100% compostable food service environments to meet zero-waste goals.
Compostable Food Service Disposables Market Drivers Analysis
The primary drivers of the compostable food service disposables market include the escalating global crisis of plastic pollution and the subsequent implementation of Extended Producer Responsibility (EPR) laws. These factors compel manufacturers and food service providers to internalize the environmental costs of packaging waste. Additionally, the rise of the conscious consumer, particularly among Millennial and Gen Z demographics, has made sustainable packaging a critical brand differentiator for food brands and restaurant chains.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Single-Use Plastic Bans | +1.8% | European Union, Canada | 2025 - 2034 |
| Expansion of Online Food Delivery | +1.5% | China, India, Brazil | 2026 - 2032 |
| Corporate ESG Initiatives | +1.2% | Global / Multi-national | 2025 - 2030 |
| Advancements in Bio-polymer Resin Yields | +0.9% | USA, Germany, Japan | 2027 - 2034 |
Compostable Food Service Disposables Market Restraints Analysis
Despite the positive growth outlook, several restraints hinder the universal adoption of compostable disposables. The most significant challenge is the disparity in cost; compostable resins and plant-based fibers often carry a price premium of 20% to 50% over conventional petroleum-based plastics. Furthermore, the lack of standardized industrial composting infrastructure in many developing regions means that even "compostable" items may end up in landfills, where they do not degrade as intended, leading to consumer skepticism and "greenwashing" allegations.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Raw Material Costs (PLA/PHA) | -1.1% | Global | Short to Medium Term |
| Inadequate Composting Infrastructure | -1.4% | Southeast Asia, Africa | 2025 - 2034 |
| Performance Limitations (Heat/Moisture) | -0.7% | Global | 2025 - 2029 |
Compostable Food Service Disposables Market Opportunities Analysis
The market presents substantial opportunities in the development of home-compostable materials that do not require high-heat industrial facilities to break down. This segment is poised for rapid growth as it bypasses the infrastructure bottleneck. Additionally, the integration of smart packaging features, such as QR codes that track the lifecycle of the packaging or provide local disposal instructions, offers a new avenue for consumer engagement. There is also a significant untapped opportunity in the healthcare and airline catering sectors, where massive volumes of disposables are used daily.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Home-Compostable Fibers | +2.1% | UK, France, Australia | 2026 - 2034 |
| Aviation and Institutional Catering Contracts | +1.4% | Middle East (Hubs), USA | 2027 - 2033 |
| Waste-to-Energy Integration | +0.8% | Northern Europe | 2028 - 2034 |
Compostable Food Service Disposables Market Challenges Impact Analysis
Operational challenges include the complexity of international certification alignment. Different regions have varying definitions of what constitutes "compostable," leading to export-import friction and labeling confusion. Moreover, the competition from the "reusable" movement poses a challenge to the disposable model itself, as some environmental advocates push for the elimination of all single-use items regardless of their material composition. Maintaining structural integrity for high-temperature liquids remains a technical hurdle for some plant-based materials.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fragmented Regulatory Standards | -0.9% | EU vs. NA vs. APAC | Ongoing |
| Contamination in Recycling Streams | -1.2% | Global Municipalities | 2025 - 2034 |
| Competition from Reusable Alternatives | -1.0% | Urban Centers | 2026 - 2034 |
Compostable Food Service Disposables Market - Updated Report Scope
This report provides a granular analysis of the global compostable food service disposables market, encompassing a detailed evaluation of material types, product categories, and end-user segments. The scope extends to the investigation of the entire value chain, from raw material suppliers of agricultural residues and bio-polymers to the final distribution networks in the hospitality sector. The research focuses on identifying high-growth pockets and assessing the impact of geopolitical shifts on the supply of sustainable resins. By synthesizing quantitative data with qualitative market sentiments, the report offers a 360-degree view of the competitive landscape and technological roadmap for the next decade.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 21.43 Billion |
| Market Forecast in 2034 | USD 36.48 Billion |
| Growth Rate | 6.1% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | NatureWorks LLC, Huhtamaki Oyj, Novamont S.p.A., Pactiv Evergreen Inc., Dart Container Corporation, Genpak LLC, Eco-Products Inc., Biopac India Corporation Ltd, Vegware Ltd, World Centric, Fabri-Kal, BASF SE, TIPA Corp, Georgia-Pacific, Berry Global, Be Green Packaging, Stora Enso, Sabert Corporation, Good Start Packaging, BioBag International |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the compostable food service disposables market is based on the necessity for high-performance functionality across diverse culinary applications. The market is bifurcated into material-specific categories, where the dominance of paper-based solutions is being challenged by advanced bio-plastics like PHA and starch blends. Product-based segmentation highlights the high volume of cups and lids, which represent a significant portion of the waste stream in urban environments. Furthermore, end-use segmentation demonstrates a growing divergence between the requirements of high-end catering and the cost-sensitive QSR market.
- By Product Type:
- Plates and Bowls (Highest revenue contributor)
- Cups and Lids (Fastest moving inventory)
- Cutlery (Knives, Forks, Spoons)
- Clamshells and Containers
- Trays and Platters
- Straws, Stirrers, and Accessories
- By Material:
- Polylactic Acid (PLA) (Dominant bio-plastic)
- Bagasse / Sugarcane Fiber (Popular for heat resistance)
- Paper and Paperboard (Traditional base, growing through coatings)
- Molded Fiber (Preferred for institutional use)
- Bamboo and Wood (High aesthetic appeal for premium dining)
- By End-User:
- Restaurants and Cafes
- Quick Service Restaurants (QSRs)
- Catering and Banquets
- Institutions (Schools, Corporate Offices, Healthcare)
- Retail and Online Food Delivery
Regional Highlights
- North America: The region holds the largest market share, with the United States leading due to aggressive sustainability targets by major food chains and statewide bans on expanded polystyrene (EPS) in California, New York, and Washington.
- Europe: The most mature market in terms of regulations, Europe excels in home-compostability standards. Germany, France, and the UK are major contributors, driven by the EU Single-Use Plastics Directive.
- Asia-Pacific: The fastest-growing region, APAC is benefiting from the massive expansion of the food delivery ecosystem in China and India. The presence of large-scale agricultural residue makes it a hub for bagasse-based manufacturing.
- Latin America: Growth is concentrated in Brazil and Mexico, where urban centers are increasingly adopting eco-friendly hospitality practices to attract international tourism and comply with emerging local waste laws.
- Middle East & Africa: The market is nascent but growing, particularly in tourism hubs like the UAE and Qatar, where mega-events and luxury hospitality sectors are mandating high-end compostable solutions.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Compostable Food Service Disposables Market.- NatureWorks LLC
- Huhtamaki Oyj
- Novamont S.p.A.
- Pactiv Evergreen Inc.
- Dart Container Corporation
- Genpak LLC
- Eco-Products, Inc.
- Biopac India Corporation Ltd
- Vegware Ltd
- World Centric
- Fabri-Kal
- BASF SE
- TIPA Corp
- Georgia-Pacific
- Berry Global
- Be Green Packaging
- Stora Enso
- Sabert Corporation
- Good Start Packaging
- BioBag International
Frequently Asked Questions
What is driving the growth of the compostable food service disposables market?
The market is primarily driven by global bans on single-use plastics, increasing consumer demand for sustainable packaging, and the rise of corporate ESG mandates among major food service chains like Starbucks and McDonald's.
Which material segment is expected to dominate by 2034?
While paper and paperboard currently lead, bagasse (sugarcane fiber) and PLA (Polylactic Acid) are expected to see the highest growth due to their superior performance in hot food applications and clear aesthetic appeal.
What are the main challenges facing the compostable packaging industry?
The primary challenges include the high cost of raw materials compared to plastic, the limited availability of industrial composting facilities in many regions, and technical issues related to moisture barrier performance for hot liquids.
Which region offers the most significant growth opportunities?
The Asia-Pacific region offers the most significant growth opportunities due to rapid urbanization, a booming food delivery market, and increasing government pressure to reduce plastic waste in countries like China and India.
How do compostable disposables differ from biodegradable ones?
Compostable products are designed to break down into nutrient-rich compost under specific conditions (usually industrial heat) without leaving toxic residues, whereas "biodegradable" is a broader term that doesn't guarantee a specific timeframe or environmental safety level.
Author
H
Hameer Thakur is a Manger Food and Beverages Research with over 8+ years of experience in the Food and Beverages Industry. He possesses extensive expertise in food and beverage market intelligence, consumer behavior analysis, demand forecasting, competitive benchmarking, product innovation assessment, pricing strategy, supply chain evaluation, regulatory compliance analysis, and market trend forecasting across packaged foods and beverage segments. His comprehensive research and data-driven insights enable organizations to make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, respond to evolving consumer preferences, and strengthen their competitive positioning in the global food and beverages market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
