Sugarcane Bottles Market
Sugarcane Bottles Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711697 | Published On : November 12, 2026 |
Format : 


 | Author : Hameer Thakur
Sugarcane Bottles Market Size
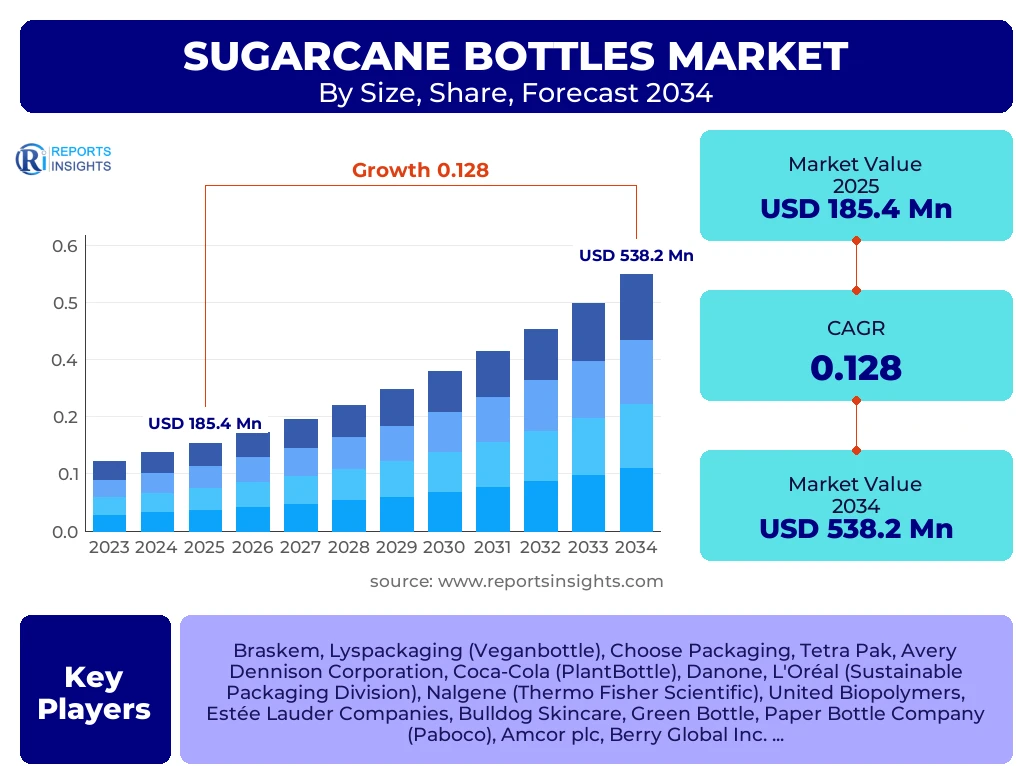
According to Reports Insights Consulting Pvt Ltd, The Sugarcane Bottles Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 12.8% between 2025 and 2034. The market is estimated at USD 209.1 Million in 2026 and is projected to reach USD 538.2 Million by the end of the forecast period in 2034.
The global shift toward sustainable packaging has positioned sugarcane-based bottles as a primary alternative to traditional petroleum-derived plastics. These bottles, often referred to as Bio-PE (polyethylene) or "PlantBottles," are derived from sugarcane ethanol, a renewable resource that significantly reduces the carbon footprint compared to fossil-fuel-based containers. The market's expansion is fundamentally driven by the convergence of stringent government regulations regarding single-use plastics and a profound shift in consumer preference for eco-friendly products. As multinational corporations in the beverage, cosmetic, and pharmaceutical sectors commit to carbon-neutrality goals, the demand for sugarcane bottles has transitioned from a niche segment to a mainstream packaging solution.
From a statistical perspective, the market is characterized by high growth in regions with robust environmental legislation and mature recycling infrastructures. The integration of sugarcane bottles into circular economy models is a critical factor in the projected CAGR. Unlike some bioplastics that require industrial composting, sugarcane-based Bio-PE is chemically identical to traditional PE, making it 100% recyclable within existing infrastructure. This "drop-in" capability has accelerated its adoption across global supply chains, allowing manufacturers to switch materials without overhauling their bottling lines or consumer recycling habits. The forecast period highlights a significant scaling of production capacity, particularly in Brazil and Southeast Asia, to meet the rising global demand for renewable packaging substrates.
Key Sugarcane Bottles Market Trends & Insights
The Sugarcane Bottles market is undergoing a transformative phase characterized by technological advancements in material science and strategic rebranding by major FMCG players. One of the most prominent trends is the move toward 100% plant-based materials, moving beyond earlier iterations that blended bio-based content with traditional plastic. Regional insights indicate that while Europe remains a regulatory pioneer, the Asia-Pacific region is emerging as the fastest-growing market due to rapid industrialization and the adoption of green packaging initiatives in China and India. Competitive benchmarking reveals that leading companies are focusing on lifecycle assessments (LCA) to prove the environmental superiority of sugarcane bottles, emphasizing that sugarcane absorbs CO2 during its growth cycle, effectively acting as a carbon sink. This narrative is resonating strongly with eco-conscious demographics, particularly in the premium personal care and luxury beverage segments.
- Largest Region: North America remains the largest market by value, driven by high consumer awareness and the presence of major beverage and cosmetic brands adopting sustainable packaging.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR due to expanding manufacturing sectors and government-led bans on single-use plastics.
- Leading Segment: The beverage industry holds the largest market share, specifically in bottled water and juice categories, where brands utilize bio-based packaging to align with health and wellness themes.
- Material Innovation: Increasing R&D investment in high-density bio-polyethylene (HDPE) derived from sugarcane to enhance bottle durability and barrier properties.
- Circular Economy Integration: Enhanced focus on "Drop-in" bioplastics that ensure sugarcane bottles are fully compatible with existing PET/PE recycling streams.
Key Takeaways Sugarcane Bottles Market Size & Forecast
The Sugarcane Bottles market is poised for a decade of robust expansion, underpinned by the global transition toward a low-carbon economy. Analysis of market dynamics suggests that the forecast period will see a stabilization of production costs as sugarcane ethanol processing achieves greater economies of scale. Stakeholders are increasingly prioritizing transparency in the supply chain, leading to certifications such as Bonsucro, which ensure that the sugarcane used for packaging is sourced sustainably and ethically. The convergence of corporate ESG (Environmental, Social, and Governance) mandates and legislative pressures like the EU’s Packaging and Packaging Waste Regulation (PPWR) serves as a primary catalyst for long-term growth. Furthermore, the market is benefiting from the development of "smart packaging" solutions where bio-based bottles are integrated with digital tracking for better waste management and recycling efficiency.
- Global Market Valuation: The market is expected to surpass the half-billion-dollar mark by 2034, reflecting a consistent upward trajectory in volume and value.
- Dominant Country: The United States leads in adoption, supported by corporate initiatives from major soft drink manufacturers.
- Strategic Shift: Brands are moving from "recyclable" messaging to "renewable" messaging, leveraging the plant-based origin of sugarcane bottles as a key differentiator.
- Economic Resilience: Despite fluctuations in raw material prices, the demand for sugarcane bottles remains resilient due to long-term sustainability contracts between suppliers and brands.
- Supply Chain Concentration: Brazil remains the critical hub for raw material supply, though diversification efforts are underway in India and Thailand.
Sugarcane Bottles Market Drivers Analysis
The primary drivers of the sugarcane bottles market include the escalating global plastic crisis, which has prompted both legislative action and consumer boycotts of traditional plastics. The carbon-negative potential of sugarcane-derived polyethylene is a decisive factor for companies aiming to meet Science Based Targets (SBTi). Additionally, the rising cost and environmental impact of petroleum extraction make bio-based alternatives increasingly attractive to long-term strategic planners in the packaging industry.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Government Regulations on Single-Use Plastics | +4.2% | European Union, Canada, China | 2025 - 2034 |
| Corporate ESG Commitments and Carbon Neutrality Goals | +3.8% | Global (Multinational Corporations) | 2025 - 2030 |
| Consumer Preference for Plant-Based Products | +2.5% | North America, Western Europe | 2026 - 2034 |
| Advances in Bio-Ethanol Conversion Technologies | +2.3% | Brazil, India | 2027 - 2034 |
Sugarcane Bottles Market Restraints Analysis
Despite the positive outlook, the market faces constraints such as the higher production cost of bio-PE compared to fossil-fuel-derived PE. Supply chain vulnerabilities, particularly the concentration of sugarcane production in specific geographical zones, also pose risks related to climate-induced crop failures and logistics disruptions.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Higher Price Point vs. Conventional Plastics | -1.8% | Global (Price-sensitive markets) | 2025 - 2029 |
| Limited Raw Material Availability and Land Use Concerns | -1.2% | Brazil, Southeast Asia | 2025 - 2034 |
Sugarcane Bottles Market Opportunities Analysis
Significant opportunities lie in the diversification of sugarcane bottles into the pharmaceutical and clinical healthcare sectors, where sterile, sustainable packaging is gaining traction. Furthermore, the development of multi-layered bio-packaging that combines sugarcane PE with other bio-polymers to improve gas barrier properties opens doors for the carbonated soft drink and alcoholic beverage markets.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into Personal Care and Cosmetic Industry | +3.1% | France, South Korea, Japan | 2026 - 2034 |
| Technological Innovation in High-Barrier Bio-Packaging | +2.7% | Germany, USA | 2027 - 2034 |
Sugarcane Bottles Market Challenges Impact Analysis
A major challenge is the potential for consumer confusion regarding biodegradability versus recyclability. Because sugarcane bottles (Bio-PE) are chemically identical to conventional PE, they are recyclable but not biodegradable in natural environments. This leads to marketing challenges and the risk of "greenwashing" accusations if not communicated clearly to the end user.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Consumer Misconceptions Regarding End-of-Life Processing | -1.5% | Global Markets | 2025 - 2030 |
| Competition from Other Bioplastics (PLA, PHA) | -0.9% | Global | 2026 - 2034 |
Sugarcane Bottles Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the global sugarcane bottles landscape, covering the entire value chain from sugarcane ethanol production to final bottle manufacturing and distribution. It evaluates various material types, including Bio-PE and Bio-PET, and examines their application across diverse end-use industries. The report provides quantitative data on market size and growth, alongside qualitative insights into the regulatory environment, competitive strategies, and technological innovations shaping the industry through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 185.4 Million |
| Market Forecast in 2034 | USD 538.2 Million |
| Growth Rate | 12.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Braskem, Lyspackaging (Veganbottle), Choose Packaging, Tetra Pak, Avery Dennison Corporation, Coca-Cola (PlantBottle), Danone, L'Oréal (Sustainable Packaging Division), Nalgene (Thermo Fisher Scientific), United Biopolymers, Estée Lauder Companies, Bulldog Skincare, Green Bottle, Paper Bottle Company (Paboco), Amcor plc, Berry Global Inc., Gerresheimer AG, Alpla |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the sugarcane bottles market is based on material composition, capacity, and the specific requirements of the end-use sectors. Bio-Polyethylene (Bio-PE) is the dominant material segment, favored for its versatility and recycling compatibility. In terms of end-use, the beverage segment leads the market, particularly for health-oriented brands that want to communicate a consistent "natural" message from product to packaging. The personal care segment is the fastest-growing area, as luxury beauty brands increasingly adopt sugarcane-based tubes and bottles to appeal to the "Clean Beauty" movement. Capacity-wise, the 250ml to 500ml range is most common, catering to the standard single-serve beverage and personal care sizes.
- By Material Type:
- Bio-Polyethylene (Bio-PE) (High Density and Low Density)
- Bio-Polyethylene Terephthalate (Bio-PET)
- Bio-Polypropylene (Bio-PP)
- By Capacity:
- Small (Up to 250ml)
- Medium (250ml to 750ml)
- Large (Above 750ml)
- By End-Use Industry:
- Beverage Industry (Water, Carbonated, Non-Carbonated)
- Personal Care & Cosmetics (Lotions, Shampoos, Skin Care)
- Household Chemicals (Detergents, Cleaners)
- Pharmaceuticals & Healthcare
- Food Service & Condiments
Regional Highlights
The global distribution of the sugarcane bottles market reveals distinct regional dynamics driven by local raw material availability and regulatory frameworks. North America currently holds the largest market share, largely due to the early adoption of bio-based materials by major beverage corporations and a consumer base willing to pay a premium for sustainable products. The United States and Canada have implemented various local-level bans on traditional plastics, further propelling the market. Europe follows closely, with the most stringent environmental regulations in the world, including the EU’s circular economy action plan, which mandates a reduction in fossil-fuel-based packaging. Germany, France, and the UK are key hubs for innovation in sustainable packaging design.
The Asia-Pacific region is the most dynamic area, projected to grow at the fastest rate during the forecast period. China's national policy to phase out non-degradable plastics has created a massive surge in demand for bio-based alternatives. Additionally, the presence of large sugarcane producers in India, Thailand, and Indonesia provides a strategic advantage for localized manufacturing of sugarcane ethanol and its derivatives. Latin America, specifically Brazil, remains the world's primary source of the raw material, and the region is increasingly moving from exporting ethanol to producing finished bio-based resin and packaging products. The Middle East and Africa are in the nascent stages but show potential as sustainability mandates begin to reach major urban centers and the tourism-driven hospitality sectors.
- North America: Largest market share; high adoption in beverage and retail sectors; strong presence of multinational brand owners.
- Europe: Regulatory leader; high focus on recyclability and "drop-in" bioplastics; mature collection and recycling infrastructure.
- Asia-Pacific: Fastest CAGR; government-led bans on single-use plastics in China and India; massive expansion in manufacturing capacity.
- Latin America: Primary raw material hub; growing domestic production of sugarcane-based resins; Brazil as a global leader in bio-ethanol.
- Middle East & Africa: Emerging market; growth driven by premium tourism sectors and luxury hospitality packaging needs.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Sugarcane Bottles Market.- Braskem
- Lyspackaging (Veganbottle)
- Choose Packaging
- Tetra Pak
- Avery Dennison Corporation
- Coca-Cola (PlantBottle Initiative)
- Danone
- L'Oréal (Sustainable Packaging Division)
- Nalgene (Thermo Fisher Scientific)
- United Biopolymers
- Estée Lauder Companies
- Bulldog Skincare
- Green Bottle
- Paper Bottle Company (Paboco)
- Amcor plc
- Berry Global Inc.
- Gerresheimer AG
- Alpla
Frequently Asked Questions
Are sugarcane bottles biodegradable or compostable?
Most sugarcane bottles on the market today are made from Bio-Polyethylene (Bio-PE), which is chemically identical to traditional plastic. This means they are 100% recyclable but not biodegradable or compostable. However, they are carbon-negative during production because sugarcane absorbs CO2 as it grows.
How does the cost of sugarcane bottles compare to traditional plastic bottles?
Currently, sugarcane bottles are generally 15% to 30% more expensive than petroleum-based plastics. This is due to the costs associated with bio-ethanol processing and smaller scales of production. However, as production scales and oil prices fluctuate, the price gap is expected to narrow.
Can sugarcane bottles be recycled with regular plastics?
Yes, Bio-PE sugarcane bottles are "drop-in" bioplastics. They can be recycled in the same streams as conventional high-density polyethylene (HDPE) or low-density polyethylene (LDPE) without contaminating the recycling process, which is a major advantage over other bioplastics like PLA.
Which industries are the biggest adopters of sugarcane packaging?
The beverage industry is the largest adopter, followed closely by personal care and cosmetics. Brands in these sectors use sugarcane bottles to appeal to environmentally conscious consumers and to meet corporate sustainability goals regarding renewable material use.
What is the environmental benefit of using sugarcane over corn-based bioplastics?
Sugarcane is often considered more sustainable than corn because it is a perennial crop that requires fewer pesticides and less intensive irrigation. Additionally, sugarcane has a higher energy-to-fuel ratio, making the conversion into bio-ethanol more efficient and lowering the overall carbon footprint.
Author
H
Hameer Thakur is a Manger Food and Beverages Research with over 8+ years of experience in the Food and Beverages Industry. He possesses extensive expertise in food and beverage market intelligence, consumer behavior analysis, demand forecasting, competitive benchmarking, product innovation assessment, pricing strategy, supply chain evaluation, regulatory compliance analysis, and market trend forecasting across packaged foods and beverage segments. His comprehensive research and data-driven insights enable organizations to make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, respond to evolving consumer preferences, and strengthen their competitive positioning in the global food and beverages market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
