Canned Foods Market
Canned Foods Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710985 | Published On : September 25, 2026 |
Format : 


 | Author : Hameer Thakur
Canned Foods Market Size
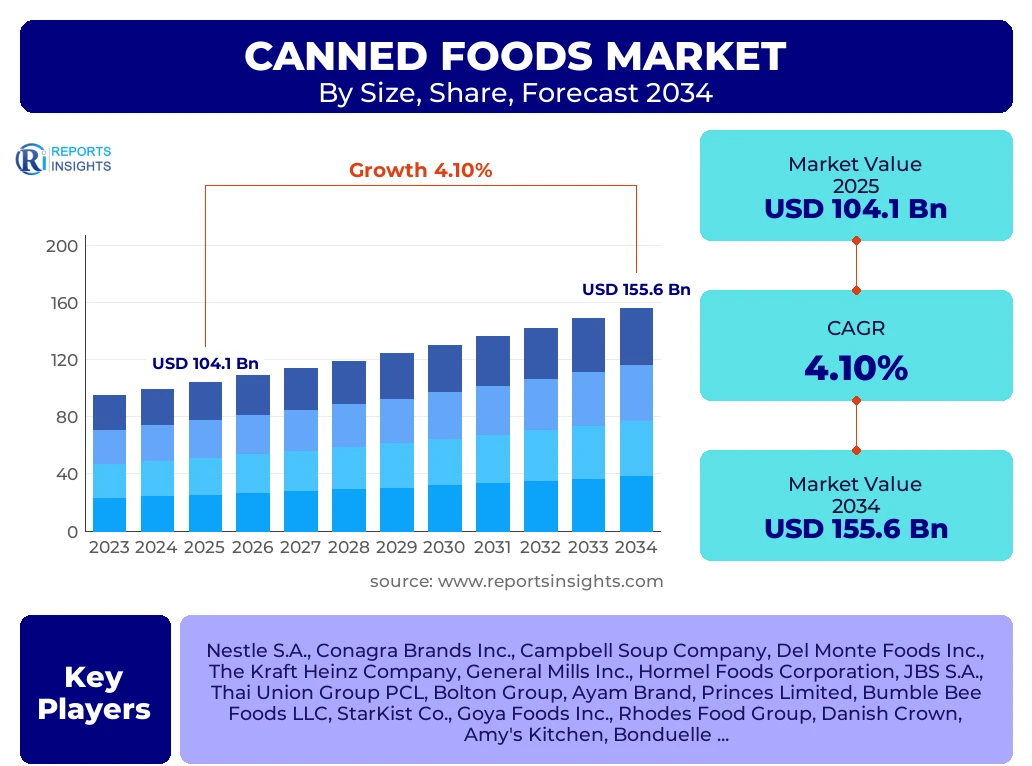
According to Reports Insights Consulting Pvt Ltd, The Canned Foods Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 4.1% between 2026 and 2034. The market is estimated at USD 108.4 Billion in 2026 and is projected to reach USD 155.6 Billion by the end of the forecast period in 2034.
Key Canned Foods Market Trends & Insights
The global canned foods landscape is undergoing a significant transformation driven by shifting consumer lifestyles and advancements in preservation technology. Historically viewed as a pantry staple for emergencies, canned goods are now being repositioned as premium, nutritious, and convenient meal solutions. Analysis of regional insights reveals that while mature markets like North America and Europe maintain a steady demand due to established consumption habits, the Asia-Pacific region is emerging as a high-growth hub fueled by rapid urbanization and an expanding middle class. Market trends indicate a move toward clean-label products, BPA-free packaging, and low-sodium variants to cater to health-conscious demographics. Furthermore, competitive benchmarking shows that key players are focusing on portfolio diversification, integrating ethnic flavors and organic ingredients to differentiate themselves in a crowded retail environment. The integration of sustainable packaging solutions remains a critical focal point as regulatory pressures regarding plastic waste increase, pushing metal and glass canning to the forefront of circular economy initiatives.
- North America currently stands as the largest region by market share, supported by high per capita consumption and a robust retail infrastructure.
- The Asia-Pacific region is identified as the fastest-growing market, driven by the increasing adoption of Westernized diets and the proliferation of organized retail chains in China and India.
- The Canned Meat and Seafood segment remains the largest in terms of value share, owing to the high cost of protein and the convenience of shelf-stable meat products.
- Canned Ready Meals are witnessing the highest growth trajectory among segments as consumers seek time-saving options that do not compromise on taste or variety.
- Digitalization of the supply chain and the rise of e-commerce platforms have significantly enhanced the accessibility of niche canned food brands globally.
Key Takeaways Canned Foods Market Size & Forecast
The global canned foods market is characterized by its resilience and ability to adapt to macro-economic shifts. Forecast models suggest a steady upward trajectory, supported by the rising demand for shelf-stable products in the face of global supply chain uncertainties. Strategic analysis of user queries suggests that consumers are increasingly concerned with the origin of ingredients and the nutritional integrity of processed foods. Leading countries such as the United States, Germany, and Japan are at the forefront of innovation, particularly in the development of functional canned foods enriched with vitamins and minerals. The market forecast emphasizes a transition from high-volume, low-margin products to value-added offerings that align with contemporary dietary trends such as keto, vegan, and gluten-free lifestyles. This shift is expected to bolster profit margins for manufacturers who can successfully navigate the complexities of modern food labeling and sustainability requirements.
- The United States is the leading country in the global canned foods market, representing a significant portion of the North American revenue share.
- Sustainability in packaging is no longer optional; aluminum and steel cans are being promoted for their infinite recyclability, influencing consumer purchasing decisions.
- The forecast period 2026-2034 will see a surge in plant-based canned options, mirroring the global decline in traditional meat consumption in specific demographics.
- Logistical efficiency and extended shelf life remain the primary value propositions for canned foods in developing economies with developing cold-chain infrastructures.
- Strategic mergers and acquisitions are expected to intensify as dominant players seek to acquire niche organic and ethnic canned food labels to broaden their market reach.
Canned Foods Market Drivers Analysis
The growth of the canned foods market is primarily propelled by the intensifying demand for convenience in urban environments where time-poverty is a major factor for consumers. As more households transition to dual-income structures, the reliance on ready-to-eat or easy-to-prepare meal components has increased substantially. Additionally, the inherent long shelf life of canned products provides a sense of food security, which has become a priority for many global populations following recent geopolitical and environmental disruptions. The ongoing evolution of canning technology, which now better preserves the texture and nutrient profile of fruits and vegetables, has also mitigated the historical perception of canned food as being nutritionally inferior to fresh produce.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Urbanization and Busy Lifestyles | +1.5% | Global (High in APAC) | 2025 - 2034 |
| Advancements in Preservation Technology | +0.8% | North America, Europe | 2026 - 2030 |
| Rising Demand for High-Protein Shelf-Stable Food | +1.1% | Latin America, MEA | 2025 - 2034 |
| Expansion of E-commerce and Grocery Delivery | +0.7% | Global | 2025 - 2034 |
Canned Foods Market Restraints Analysis
Despite steady growth, the market faces significant restraints, most notably the lingering consumer perception regarding the use of synthetic preservatives and high sodium content. In health-conscious regions like Western Europe, the "fresh-is-best" movement continues to challenge the growth of processed food segments. Furthermore, the volatility in raw material prices, particularly for steel and aluminum used in packaging, can lead to fluctuating profit margins for manufacturers. Regulatory scrutiny over Bisphenol A (BPA) linings in cans has also forced the industry to invest heavily in alternative coating technologies, increasing production costs in the short term.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Health Concerns Regarding Sodium and Preservatives | -0.6% | Europe, North America | 2025 - 2034 |
| Fluctuating Raw Material Prices (Metal) | -0.4% | Global | 2026 - 2029 |
| Strict Environmental and Packaging Regulations | -0.3% | European Union | 2025 - 2030 |
Canned Foods Market Opportunities Analysis
The market is ripe with opportunities, particularly in the premiumization and diversification of product lines. There is a burgeoning market for "gourmet" canned foods, such as high-quality canned seafood (tuna, sardines, octopus) and organic vegetable medleys that appeal to the epicurean consumer. Additionally, the rise of the "flexitarian" diet presents a massive opportunity for canned legumes and plant-based ready meals. Emerging markets in Africa and Southeast Asia offer untapped potential for basic canned staples as cold chain infrastructure remains underdeveloped, making shelf-stable options the most viable solution for food distribution in these regions.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into Organic and Non-GMO Segments | +1.2% | North America, Germany | 2026 - 2034 |
| Development of BPA-Free and Eco-Friendly Packaging | +0.9% | Western Europe, Japan | 2025 - 2034 |
| Targeting Underdeveloped Markets with Basic Staples | +1.4% | Africa, Southeast Asia | 2027 - 2034 |
| Customized Ethnic and Regional Canned Flavors | +0.6% | Global | 2025 - 2030 |
Canned Foods Market Challenges Impact Analysis
Operational challenges in the canned foods market include managing complex global supply chains and mitigating the environmental impact of industrial canning processes. Maintaining quality consistency while scaling production to meet global demand requires significant investment in automated quality control systems. Additionally, competition from other food preservation methods, such as freezing and vacuum-packing, continues to intensify. The industry must also navigate the logistical challenges of transporting heavy canned goods, which contributes to a higher carbon footprint compared to lighter packaging alternatives like pouches or cartons.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Competition from Frozen and Fresh Food Categories | -0.5% | Global | 2025 - 2034 |
| High Transportation Costs due to Weight | -0.3% | Global | 2025 - 2034 |
| Sustainability Pressures on Traditional Metal Cans | -0.2% | Global (Mainly Developed Markets) | 2026 - 2030 |
Canned Foods Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the global canned foods industry, covering multiple product categories, distribution channels, and geographic regions. It evaluates the impact of technological innovations in food processing and packaging on market growth. The study provides detailed insights into consumer behavior, regulatory frameworks, and competitive dynamics, offering a 360-degree view of the market's evolution from 2020 to 2034. By examining both historical data and future projections, the report identifies high-growth segments and provides actionable intelligence for stakeholders looking to capitalize on emerging trends in the shelf-stable food sector.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 104.1 Billion |
| Market Forecast in 2034 | USD 155.6 Billion |
| Growth Rate | 4.1% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Nestle S.A., Conagra Brands Inc., Campbell Soup Company, Del Monte Foods Inc., The Kraft Heinz Company, General Mills Inc., Hormel Foods Corporation, JBS S.A., Thai Union Group PCL, Bolton Group, Ayam Brand, Princes Limited, Bumble Bee Foods LLC, StarKist Co., Goya Foods Inc., Rhodes Food Group, Danish Crown, Amy's Kitchen, Bonduelle, Wild Planet Foods |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The canned foods market is intricately segmented to reflect the diverse dietary needs and purchasing behaviors of global consumers. The Product Type segmentation reveals that Canned Meat and Seafood dominate the value share, driven by the convenience of having high-protein sources readily available without the need for refrigeration or extensive preparation. Canned Vegetables and Fruits follow closely, serving as essential ingredients for both home cooking and the food service industry. The Distribution Channel analysis shows that Supermarkets and Hypermarkets remain the primary point of sale, though Online Retail is experiencing the fastest growth as consumers become more comfortable purchasing heavy grocery items through digital platforms. Packaging Material is another critical segment, where the shift toward lightweight and easily recyclable aluminum is gaining momentum over traditional tinplate. Finally, the distinction between Organic and Conventional types highlights a growing niche for premium, pesticide-free canned goods among health-conscious urban populations.
- Canned Meat: Includes beef, pork, poultry, and processed meat products; valued for high protein content and shelf stability.
- Canned Seafood: Encompasses tuna, salmon, sardines, and shellfish; a major segment driven by global seafood consumption and convenience.
- Canned Vegetables: Comprises corn, peas, tomatoes, beans, and mixed vegetables; essential for year-round availability of seasonal produce.
- Canned Fruits: Includes pineapples, peaches, pears, and fruit cocktails; popular in both retail and bakery/confectionery sectors.
- Canned Ready Meals: Covers pasta, stews, and ethnic dishes; the fastest-growing segment due to time-constrained consumer lifestyles.
- Canned Soups and Sauces: A mature segment with high penetration in North America and Europe, focusing on flavor innovation.
- Supermarkets/Hypermarkets: The leading distribution channel providing a wide variety of brands and competitive pricing.
- Online Retail: Growing rapidly due to subscription models and the convenience of home delivery for bulk purchases.
- Institutional Sales: Includes sales to hospitals, schools, and the military, where long shelf life is a logistical requirement.
Regional Highlights
- North America: The largest market for canned foods, characterized by high consumer awareness, a preference for convenience, and a mature retail sector. The U.S. leads the region with a strong demand for canned soups and meat products.
- Europe: A highly diverse market where Western Europe shows a preference for organic and gourmet canned seafood, while Eastern Europe relies heavily on canned staples. Germany, France, and the UK are the key revenue generators.
- Asia-Pacific: The fastest-growing region, driven by rapid urbanization in China, India, and Southeast Asia. The expanding middle class and the westernization of diets are boosting the consumption of canned fruits and ready meals.
- Latin America: Shows steady growth, particularly in Brazil and Mexico, where canned beans and meat products are integral to the local diet.
- Middle East & Africa: Represents a significant opportunity for growth due to the lack of cold chain infrastructure in many areas, making canned foods a vital source of nutrition and food security.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Canned Foods Market.- Nestle S.A.
- Conagra Brands Inc.
- Campbell Soup Company
- Del Monte Foods Inc.
- The Kraft Heinz Company
- General Mills Inc.
- Hormel Foods Corporation
- JBS S.A.
- Thai Union Group PCL
- Bolton Group
- Ayam Brand
- Princes Limited
- Bumble Bee Foods LLC
- StarKist Co.
- Goya Foods Inc.
- Rhodes Food Group
- Danish Crown
- Amy's Kitchen
- Bonduelle
- Wild Planet Foods
Frequently Asked Questions
What is the current global market size of the Canned Foods industry?
The global canned foods market is estimated to be valued at USD 104.1 Billion in 2025 and is projected to reach USD 155.6 Billion by 2034, growing at a CAGR of 4.1% during the forecast period.
Which region is expected to show the highest growth in the canned foods market?
The Asia-Pacific region is expected to witness the highest CAGR from 2025 to 2034, driven by urbanization, rising disposable incomes, and an expanding retail network in countries like China and India.
What are the primary factors driving the demand for canned foods?
The primary drivers include the increasing demand for convenient meal solutions, the long shelf life of canned products, advancements in food preservation technology, and the rising global demand for protein-rich, shelf-stable foods.
Who are the leading players in the global canned foods market?
Key players include Nestle S.A., Conagra Brands Inc., Campbell Soup Company, Del Monte Foods, and The Kraft Heinz Company, along with specialized firms like Thai Union Group and Bonduelle.
How is the market addressing sustainability and health concerns?
Manufacturers are increasingly adopting BPA-free linings for cans, utilizing 100% recyclable aluminum and steel, and launching low-sodium, organic, and preservative-free product lines to appeal to health-conscious and eco-aware consumers.
Author
H
Hameer Thakur is a Manger Food and Beverages Research with over 8+ years of experience in the Food and Beverages Industry. He possesses extensive expertise in food and beverage market intelligence, consumer behavior analysis, demand forecasting, competitive benchmarking, product innovation assessment, pricing strategy, supply chain evaluation, regulatory compliance analysis, and market trend forecasting across packaged foods and beverage segments. His comprehensive research and data-driven insights enable organizations to make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, respond to evolving consumer preferences, and strengthen their competitive positioning in the global food and beverages market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
