Blood Glucose Monitoring Devices Market
Blood Glucose Monitoring Devices Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711042 | Published On : October 01, 2026 |
Format : 


 | Author : Erika Grotto
Blood Glucose Monitoring Devices Market Size
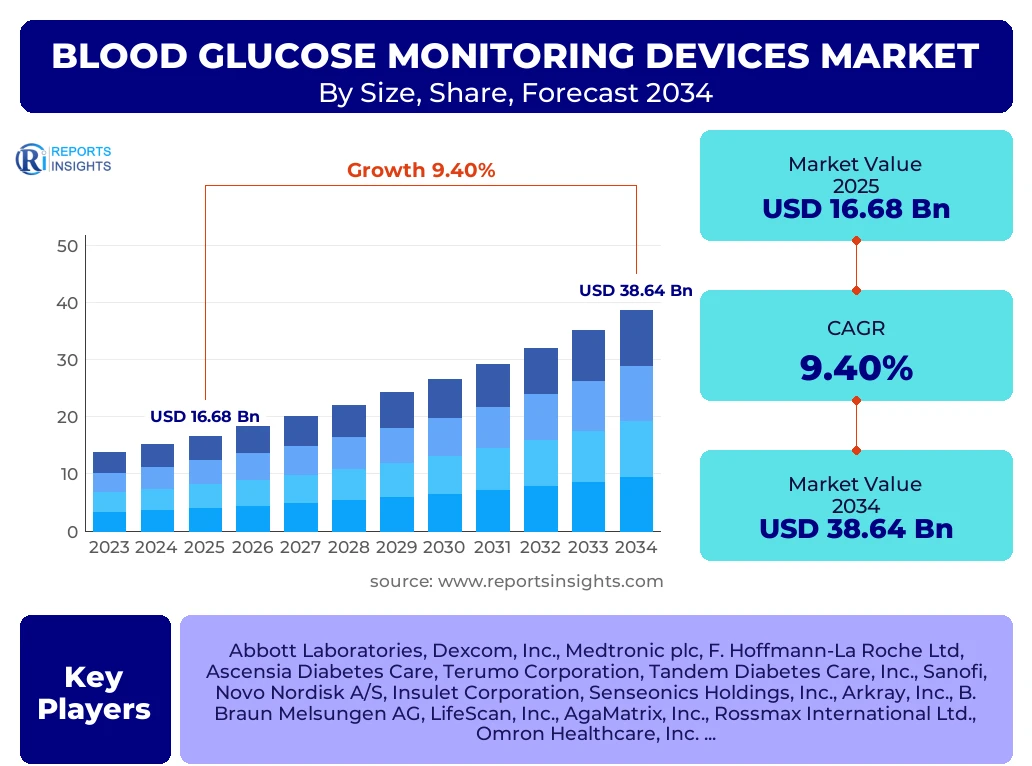
According to Reports Insights Consulting Pvt Ltd, The Blood Glucose Monitoring Devices Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 9.4% between 2026 and 2034. The market is estimated at USD 18.25 Billion in 2026 and is projected to reach USD 38.64 Billion by the end of the forecast period in 2034.
Key Blood Glucose Monitoring Devices Market Trends & Insights
The Blood Glucose Monitoring Devices market is undergoing a significant paradigm shift, transitioning from traditional self-monitoring blood glucose (SMBG) systems toward sophisticated Continuous Glucose Monitoring (CGM) technologies. This evolution is primarily driven by the increasing demand for real-time data analytics and minimally invasive solutions that enhance patient compliance and clinical outcomes. Current market intelligence indicates that the integration of artificial intelligence (AI) and machine learning (ML) into monitoring software is revolutionizing glycemic management by providing predictive insights into hypoglycemic and hyperglycemic events. Furthermore, the convergence of glucose monitoring with automated insulin delivery systems—often referred to as artificial pancreas systems—is setting a new standard for Type 1 diabetes management globally. Regional analysis suggests that while North America remains the primary revenue generator due to high healthcare expenditure and early technology adoption, the Asia-Pacific region is poised for the most rapid expansion, fueled by rising obesity rates and improving diagnostic infrastructure in emerging economies.
- Largest Market Region: North America, holding a dominant share exceeding 40% due to established reimbursement frameworks and high prevalence of Type 1 and Type 2 diabetes.
- Fastest Growing Region: Asia-Pacific, expected to exhibit a CAGR of over 11% as healthcare accessibility improves in China, India, and Southeast Asia.
- Largest Segment by Component: Sensors and Transmitters within the CGM category, which command the highest market share due to their recurring replacement cycles.
- Primary End-User Segment: Home Care Settings, reflecting a broader healthcare trend toward decentralized patient management and remote monitoring.
- Key Technological Trend: Non-invasive glucose monitoring research and the development of multi-sensor wearables that track glucose alongside other vital signs.
Key Takeaways Blood Glucose Monitoring Devices Market Size & Forecast
The global outlook for the Blood Glucose Monitoring Devices market remains exceptionally bullish, characterized by a steady upward trajectory in both valuation and volume through 2034. Stakeholders are increasingly focusing on the digitalization of diabetes care, where hardware sales are supplemented by subscription-based data services and telehealth integration. Market forecasts indicate that the CGM segment will continue to cannibalize the SMBG market share as sensor costs decrease and clinical evidence of superior long-term health outcomes becomes more robust. Strategic investments are currently concentrated on improving sensor longevity and reducing the calibration requirements of monitoring devices to minimize user burden. Additionally, the expansion of healthcare insurance coverage for glucose monitors in middle-income countries is expected to unlock significant untapped market potential during the latter half of the forecast period.
- Dominant Country: The United States leads the global landscape, supported by a proactive regulatory environment and significant R&D investments by major medical technology firms.
- Forecast Growth: The market is anticipated to double its current valuation within the next decade, driven by a global diabetic population projected to exceed 600 million by 2030.
- Product Evolution: Transition from intermittent testing to continuous data streaming is the single most important factor influencing market dynamics.
- Competitive Landscape: Market consolidation is expected as major players acquire innovative startups specializing in non-invasive sensing and digital health platforms.
- Sustainability Focus: Growing pressure to develop eco-friendly, biodegradable sensor components to address the environmental impact of disposable medical devices.
Blood Glucose Monitoring Devices Market Drivers Analysis
The primary catalysts for the Blood Glucose Monitoring Devices market include the skyrocketing global incidence of diabetes, exacerbated by sedentary lifestyles and dietary shifts. Technological breakthroughs in sensor miniaturization and the expansion of the geriatric population, who require frequent monitoring, serve as foundational growth pillars for the industry. Moreover, the increasing adoption of telehealth and mobile health (mHealth) applications has created a seamless ecosystem for glucose data transmission, encouraging both patients and clinicians to utilize advanced monitoring hardware.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Global Prevalence of Diabetes | +3.2% | Global (High impact in India/China) | 2025 - 2034 |
| Technological Shift Toward CGM Systems | +2.8% | North America and Western Europe | 2025 - 2030 |
| Integration with Wearable Smart Devices | +1.5% | United States, Japan, South Korea | 2026 - 2032 |
| Expanding Reimbursement Policies | +1.1% | Germany, France, United Kingdom | 2025 - 2029 |
| Increasing Health Awareness and Early Diagnosis | +0.8% | Latin America and Southeast Asia | 2027 - 2034 |
Blood Glucose Monitoring Devices Market Restraints Analysis
Despite the positive growth outlook, several factors impede the full-scale adoption of advanced glucose monitoring solutions. The high cost associated with Continuous Glucose Monitoring sensors and transmitters remains a significant barrier in developing nations where out-of-pocket expenses are high. Furthermore, stringent regulatory approval processes for new medical devices and the lack of standardized data protocols across different platforms can delay market entry and limit interoperability between devices and healthcare systems.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of CGM Maintenance and Consumables | -1.4% | Middle East, Africa, and parts of Asia | 2025 - 2034 |
| Stringent Regulatory and Compliance Requirements | -0.9% | European Union (MDR), United States (FDA) | 2025 - 2028 |
| Inconsistent Reimbursement Frameworks | -0.7% | Brazil, Mexico, and India | 2025 - 2030 |
| Data Privacy and Cybersecurity Concerns | -0.5% | North America and Europe | 2026 - 2034 |
Blood Glucose Monitoring Devices Market Opportunities Analysis
The market presents lucrative opportunities in the development of non-invasive monitoring technologies, such as optical sensors and sweat-based analysis, which could eliminate the need for painful skin penetration. There is also substantial potential in the integration of glucose data with comprehensive chronic disease management platforms that address comorbidities like hypertension and obesity. Expanding into emerging markets with affordable, stripped-down versions of smart monitors represents a major strategic opportunity for global manufacturers looking to diversify their revenue streams.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Emergence of Non-Invasive Sensing Technologies | +2.4% | United States, Israel, Germany | 2028 - 2034 |
| Expansion into Tier 2 and Tier 3 Cities in APAC | +1.8% | China and India | 2026 - 2034 |
| AI-Driven Predictive Glycemic Analytics | +1.2% | Global (Medical Software segment) | 2025 - 2031 |
| Integration with Corporate Wellness Programs | +0.9% | North America and Western Europe | 2026 - 2030 |
Blood Glucose Monitoring Devices Market Challenges Impact Analysis
Key challenges facing the industry include the technical difficulty of maintaining sensor accuracy over long periods without frequent calibration. The market also faces intense competition from low-cost manufacturers of traditional test strips, particularly in price-sensitive regions. Additionally, the environmental challenge of managing electronic waste from disposable sensors and the complexity of ensuring user adherence to sophisticated digital monitoring systems pose long-term operational hurdles for manufacturers.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Environmental Impact of Disposable Bio-Sensors | -0.6% | European Union and Scandinavia | 2027 - 2034 |
| Maintaining Sensor Accuracy and Bio-compatibility | -0.8% | Global R&D centers | 2025 - 2034 |
| Intense Price Competition in SMBG Strips | -1.2% | Global (Generic manufacturers) | 2025 - 2029 |
| User Resistance to Continuous Wearables | -0.4% | Elderly populations globally | 2025 - 2032 |
Blood Glucose Monitoring Devices Market - Updated Report Scope
The scope of this comprehensive market analysis encompasses the entire ecosystem of glucose monitoring, ranging from traditional invasive finger-prick devices to the latest generation of subcutaneous continuous sensors. The report evaluates the market based on product types, components, end-users, and distribution channels across six major geographic regions. It provides a detailed examination of the competitive landscape, focusing on technological roadmaps, strategic collaborations, and the regulatory environment that shapes the commercialization of next-generation medical devices.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 16.68 Billion |
| Market Forecast in 2034 | USD 38.64 Billion |
| Growth Rate | 9.4% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Abbott Laboratories, Dexcom, Inc., Medtronic plc, F. Hoffmann-La Roche Ltd, Ascensia Diabetes Care, Terumo Corporation, Tandem Diabetes Care, Inc., Sanofi, Novo Nordisk A/S, Insulet Corporation, Senseonics Holdings, Inc., Arkray, Inc., B. Braun Melsungen AG, LifeScan, Inc., AgaMatrix, Inc., Rossmax International Ltd., Omron Healthcare, Inc., Prodigy Diabetes Care, LLC, Nipro Corporation. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Blood Glucose Monitoring Devices market is strategically segmented to reflect the diverse clinical needs and technological preferences of different patient demographics. The primary division between SMBG and CGM systems represents the shift from intermittent to longitudinal data collection, which is fundamental to modern diabetes management strategies. Component-level segmentation highlights the shift from revenue models based on high-volume test strip sales to value-based models focused on long-duration sensors and data-driven insights. End-user segmentation further identifies the home care setting as the most significant growth area, as healthcare providers increasingly decentralize chronic disease management to reduce hospital burdens and improve patient autonomy.
- By Product Type:
- Self-Monitoring Blood Glucose (SMBG) Systems: Including portable meters used for periodic testing.
- Continuous Glucose Monitoring (CGM) Systems: Including real-time (rtCGM) and intermittently viewed (iCGM) systems.
- By Component:
- Testing Strips: The high-volume consumable segment for SMBG users.
- Sensors: The critical high-value component for CGM systems with varying lifespans (7 to 180 days).
- Transmitters and Receivers: The hardware responsible for data processing and display.
- Lancets and Lancing Devices: Essential accessories for capillary blood sampling.
- By Application/Patient Type:
- Type 1 Diabetes: Heavily reliant on CGM for intensive insulin management.
- Type 2 Diabetes: A massive and growing segment transitioning toward monitoring for lifestyle adjustment.
- Gestational Diabetes: Short-term monitoring segment with specialized clinical requirements.
- By Distribution Channel:
- Institutional Sales (Hospitals and Clinics)
- Retail Pharmacies
- Online Channels/E-commerce
Regional Highlights
- North America: Currently the largest market, driven by the United States' robust healthcare infrastructure and high adoption rates of advanced medical technologies. The presence of major industry leaders like Dexcom and Abbott facilitates rapid market penetration of new products.
- Europe: The second-largest market, characterized by comprehensive socialized healthcare systems that increasingly cover CGM costs. Germany, France, and the UK are key contributors to the regional growth, focusing on patient outcomes and cost-effectiveness.
- Asia-Pacific: Identified as the fastest-growing region. Massive diabetic populations in China and India, coupled with rising disposable incomes and government initiatives to curb chronic diseases, are propelling market demand.
- Latin America: Showing significant potential in countries like Brazil and Mexico. Market growth is supported by improving diagnostic capabilities and a growing middle class seeking better health management tools.
- Middle East and Africa: A region with high diabetes prevalence rates, particularly in the GCC countries. Growth is currently moderated by varying healthcare access but is expected to accelerate as private healthcare investments increase.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Blood Glucose Monitoring Devices Market.- Abbott Laboratories
- Dexcom, Inc.
- Medtronic plc
- F. Hoffmann-La Roche Ltd
- Ascensia Diabetes Care
- Terumo Corporation
- Tandem Diabetes Care, Inc.
- Sanofi
- Novo Nordisk A/S
- Insulet Corporation
- Senseonics Holdings, Inc.
- Arkray, Inc.
- B. Braun Melsungen AG
- LifeScan, Inc.
- AgaMatrix, Inc.
- Rossmax International Ltd.
- Omron Healthcare, Inc.
- Prodigy Diabetes Care, LLC
- Nipro Corporation
Frequently Asked Questions
What is the projected market size of the Blood Glucose Monitoring Devices market by 2034?
The global Blood Glucose Monitoring Devices market is projected to reach approximately USD 38.64 Billion by 2034, growing at a steady CAGR of 9.4% from 2026 onwards.
Which technology is currently leading the market growth?
Continuous Glucose Monitoring (CGM) systems are the primary growth engine of the market, as they offer real-time data and are increasingly favored over traditional finger-prick self-monitoring systems.
Who are the major players in the global market?
The market is dominated by large medical technology firms including Abbott Laboratories, Dexcom, Medtronic, and F. Hoffmann-La Roche, which together hold a significant portion of the global market share.
Which region is expected to grow the fastest during the forecast period?
The Asia-Pacific region is anticipated to be the fastest-growing market due to the rising incidence of diabetes in China and India and improving healthcare access across the continent.
What are the main drivers for market expansion?
Key drivers include the rising global prevalence of diabetes, technological advancements in wearable sensors, and the integration of glucose monitoring with digital health platforms and AI.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted