Medical Equipment Third Party Calibration Services Market
Medical Equipment Third Party Calibration Services Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711731 | Published On : November 13, 2026 |
Format : 


 | Author : Erika Grotto
Medical Equipment Third Party Calibration Services Market Size
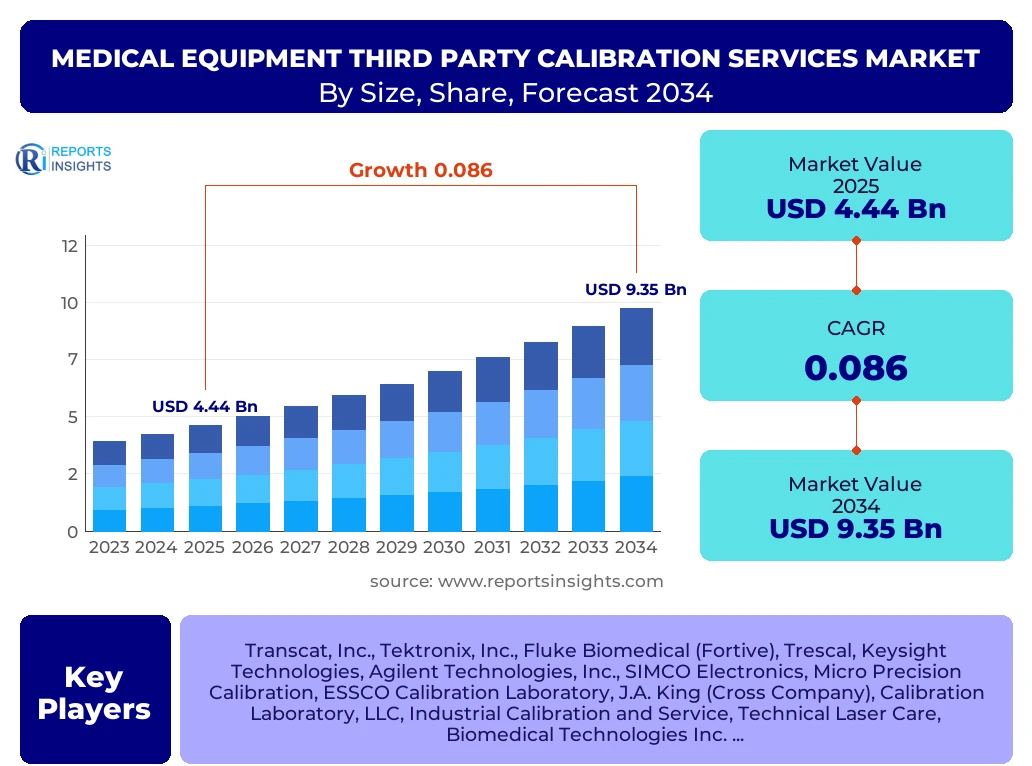
According to Reports Insights Consulting Pvt Ltd, The Medical Equipment Third Party Calibration Services Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.6% between 2025 and 2034. The market is estimated at USD 4.82 Billion in 2026 and is projected to reach USD 9.35 Billion by the end of the forecast period in 2034.
Key Medical Equipment Third Party Calibration Services Market Trends & Insights
The global landscape for medical equipment calibration is undergoing a paradigm shift, driven primarily by the transition from reactive maintenance to proactive metrological management. Stakeholders are increasingly prioritizing third-party providers who offer specialized expertise, ISO 17025 accreditation, and comprehensive digital documentation. Regional insights suggest that North America remains the dominant revenue generator due to stringent FDA enforcement, while the Asia-Pacific region is emerging as the fastest-growing market, fueled by massive healthcare infrastructure investments in China and India. Competitive benchmarking reveals a trend toward consolidation, where large-scale service providers are acquiring boutique calibration laboratories to expand their geographic footprint and technical scope. Furthermore, the integration of cloud-based Asset Management Systems (AMS) is enabling real-time tracking of calibration certificates, significantly reducing the administrative burden on clinical engineering departments.
- North America is the largest regional market, accounting for approximately 38% of the global market share in 2025.
- Asia-Pacific is the fastest-growing region, with an expected CAGR of 10.2% during the forecast period.
- The Imaging Equipment segment holds the largest market share by equipment type, driven by the high complexity and precision requirements of MRI and CT systems.
- Hospitals represent the leading end-user segment, utilizing third-party services to optimize operational uptime and ensure patient safety.
- On-site calibration services are witnessing higher demand compared to off-site laboratory services due to the risk of damage during transport.
Key Takeaways Medical Equipment Third Party Calibration Services Market Size & Forecast
The trajectory of the Medical Equipment Third Party Calibration Services market is intrinsically linked to the global expansion of diagnostic and therapeutic modalities. As medical devices become more interconnected and complex, the margin for error narrows, making professional calibration a non-negotiable requirement for regulatory compliance. The forecast suggests that market growth will be sustained by the increasing volume of surgical procedures and the proliferation of diagnostic imaging centers globally. Financial analysts point toward a strong correlation between the rise in medical device manufacturing and the subsequent demand for secondary and tertiary calibration services. Additionally, the move toward value-based healthcare is compelling providers to ensure that every diagnostic output is derived from perfectly calibrated instrumentation to avoid costly misdiagnoses or legal liabilities.
- The United States is the leading country market globally, supported by a mature healthcare ecosystem and rigorous accreditation standards such as Joint Commission audits.
- Digitalization of calibration records is becoming a standard industry requirement, facilitating seamless audits and compliance reporting.
- Third-party providers are increasingly being preferred over Original Equipment Manufacturers (OEMs) due to their multi-vendor service capabilities and cost-effectiveness.
- The growth of the geriatric population worldwide is indirectly driving market demand by increasing the utilization of patient monitoring and diagnostic equipment.
- Technological advancements in automated calibration software are expected to improve service efficiency and reduce human error by 2030.
Medical Equipment Third Party Calibration Services Market Drivers Analysis
The primary driver for the Medical Equipment Third Party Calibration Services market is the escalating complexity of modern medical instrumentation combined with a heightened global focus on patient safety. As diagnostic tools evolve to include sophisticated electronics and software-driven sensors, the necessity for precise calibration according to national and international standards has become paramount. Healthcare providers are shifting away from internal calibration teams due to the high cost of maintaining sophisticated laboratory equipment and the continuous training required for staff. This outsourcing trend allows hospitals to focus on patient care while ensuring that their critical assets meet stringent regulatory frameworks such as the European Union’s Medical Device Regulation (MDR) and the FDA’s Quality System Regulation (QSR).
Furthermore, the global rise in chronic diseases and the aging population have led to a significant increase in the volume of diagnostic tests and therapeutic interventions. This high utilization rate accelerates the wear and tear on medical devices, necessitating more frequent calibration cycles to maintain accuracy. The cost-saving benefits of third-party services, which often provide multi-vendor solutions under a single contract, offer a compelling value proposition for healthcare administrators looking to optimize operational budgets without compromising on quality or compliance.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Regulatory Compliance (ISO/FDA) | +2.4% | Global (Strong in USA/EU) | 2025 - 2034 |
| Expansion of Diagnostic Centers | +1.8% | Asia-Pacific, Latin America | 2026 - 2032 |
| Preference for Multi-Vendor Service Providers | +1.5% | North America, Europe | 2025 - 2030 |
| Technological Sophistication of Devices | +1.2% | Global | 2025 - 2034 |
Medical Equipment Third Party Calibration Services Market Restraints Analysis
One of the most significant restraints facing the market is the high initial investment required to establish accredited calibration laboratories that meet international standards. For third-party providers, the cost of acquiring high-precision master gauges, environmental control systems, and specialized software can be prohibitive, especially for small and medium-sized enterprises. This creates a barrier to entry that limits competition in certain niche technical areas. Additionally, there is a persistent shortage of highly skilled biomedical engineers and metrology experts who possess the specialized knowledge required to calibrate advanced robotic surgical systems or high-field MRI units.
Another restraining factor is the aggressive retention strategies employed by Original Equipment Manufacturers (OEMs). Many OEMs bundle calibration and maintenance services with the initial equipment purchase, often including proprietary software locks that prevent third-party access to internal diagnostic modules. This "locked ecosystem" can deter healthcare facilities from switching to third-party providers, despite potential cost savings. Furthermore, logistical challenges in transporting sensitive medical equipment to off-site labs and the potential for downtime during the calibration process remain concerns for high-volume clinical settings.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Proprietary Service Software Restrictions | -1.2% | Global | 2025 - 2029 |
| Shortage of Skilled Metrology Technicians | -0.8% | Developed Economies | 2025 - 2034 |
| High Capital Expenditure for Lab Equipment | -0.6% | Emerging Markets | 2026 - 2030 |
Medical Equipment Third Party Calibration Services Market Opportunities Analysis
The rapid integration of Internet of Things (IoT) and Artificial Intelligence (AI) into medical devices presents a massive opportunity for the evolution of calibration services. "Smart calibration" systems that utilize remote monitoring to detect drift in device accuracy in real-time are becoming increasingly viable. Third-party providers who invest in these predictive maintenance technologies can offer value-added services that reduce equipment downtime and predict failures before they occur. This transition from scheduled calibration to condition-based calibration is expected to be a major growth frontier over the next decade.
Moreover, the growth of the home healthcare and remote patient monitoring market offers a new revenue stream for calibration services. As more diagnostic and therapeutic devices move from the hospital to the patient's home, the logistics of ensuring these devices remain accurate become more complex. Third-party providers that can develop mobile calibration units or centralized mail-in programs for home-use medical devices are well-positioned to capture this burgeoning segment. Emerging markets in Southeast Asia and Africa also represent untapped potential as healthcare modernization programs gain momentum and local regulations move toward international standardization.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| AI-Enabled Remote Calibration Services | +2.1% | USA, Germany, Japan | 2027 - 2034 |
| Expansion into Home Healthcare Devices | +1.4% | Global | 2026 - 2034 |
| Developing Regional Accreditation Hubs | +1.1% | Middle East, SE Asia | 2025 - 2030 |
Medical Equipment Third Party Calibration Services Market Challenges Impact Analysis
The primary challenge for third-party calibration providers is the rapid pace of innovation in medical device manufacturing. Every year, new materials, sensor technologies, and software algorithms are introduced, requiring calibration technicians to constantly update their skills and equipment. Maintaining the necessary accreditations across a wide range of specialties—from radiological to mechanical and electronic—is an expensive and administratively intensive process. Small service providers often struggle to keep up with the documentation and audit requirements necessary to maintain ISO/IEC 17025 certification across multiple domains.
Additionally, geopolitical tensions and supply chain instabilities can disrupt the availability of critical calibration parts and reference standards. Since calibration relies on traceable standards back to national metrology institutes, any delay in the procurement of certified reference materials can stall service operations. Furthermore, the lack of standardized calibration protocols across different manufacturers makes it difficult to implement automated service solutions, often requiring labor-intensive manual procedures that increase the cost and time required for each service event.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Keeping Pace with Rapid OEM Innovation | -0.9% | Global | 2025 - 2034 |
| Supply Chain Delays for Standard Parts | -0.5% | Global | 2025 - 2027 |
| Lack of Global Standardization in Protocols | -0.7% | International | 2025 - 2034 |
Medical Equipment Third Party Calibration Services Market - Updated Report Scope
This comprehensive report provides a deep-dive analysis into the global medical equipment third-party calibration services market, covering the forecast period from 2026 to 2034. It evaluates the impact of technological advancements, regulatory shifts, and economic trends across various service categories and end-user segments. The scope includes a detailed assessment of the competitive landscape, providing profiles of the top 20 industry players and their strategic positioning. Market sizing is conducted using a bottom-up approach, validated through primary interviews with industry experts and clinical engineering leads, ensuring high data accuracy and logical consistency.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 4.44 Billion |
| Market Forecast in 2034 | USD 9.35 Billion |
| Growth Rate | 8.6% CAGR |
| Number of Pages | 248 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Transcat, Inc., Tektronix, Inc., Fluke Biomedical (Fortive), Trescal, Keysight Technologies, Agilent Technologies, Inc., SIMCO Electronics, Micro Precision Calibration, ESSCO Calibration Laboratory, J.A. King (Cross Company), Calibration Laboratory, LLC, Industrial Calibration and Service, Technical Laser Care, Biomedical Technologies Inc., Biotek Services, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on service type, equipment category, and end-user profile to provide a granular view of growth opportunities. The shift toward on-site services is the most prominent trend within the service type segment, as it eliminates the risks associated with moving expensive diagnostic units. Imaging equipment remains the highest value segment due to the expensive specialized sensors and detectors that require ultra-precise calibration. In terms of end-users, hospitals continue to dominate, but there is a noticeable rise in the research and laboratory segment, where precision is critical for drug development and clinical trials.
- By Service Type:
- On-site Calibration: High demand for large, non-portable imaging and surgical systems.
- Off-site/Laboratory Calibration: Used for small, portable handheld devices and specialized laboratory tools.
- In-house Managed Services: Large hospital chains opting for embedded third-party teams.
- By Equipment Type:
- Diagnostic Imaging: MRI, CT Scanners, X-ray, Ultrasound.
- Patient Monitoring: Vital sign monitors, ECG, Pulse Oximeters.
- Cardiovascular: Defibrillators, Pacemaker programmers.
- Laboratory Equipment: Centrifuges, Pipettes, Analyzers.
- Surgical Equipment: Electrosurgical units, Robotic assistants.
- By End-User:
- Hospitals: Public and Private large-scale medical facilities.
- Diagnostic Centers: Specialized imaging and pathology labs.
- Clinics: Small outpatient and specialized practice settings.
- Pharmaceutical and Biotech Research Labs: Focusing on R&D precision.
Regional Highlights
- North America: The largest market share holder, characterized by a highly regulated environment and high adoption of outsourced biomedical services. The United States leads due to strict CMS and Joint Commission requirements.
- Europe: Driven by the implementation of the new MDR (Medical Device Regulation), which has tightened requirements for equipment maintenance and traceability. Germany and the UK are the primary contributors.
- Asia-Pacific: The fastest-growing region due to rapid healthcare modernization, particularly in China, India, and Southeast Asian nations. Increasing awareness of international standards is driving the shift from internal to third-party calibration.
- Latin America: Brazil and Mexico are emerging as key markets as they upgrade their public health infrastructure and diagnostic capabilities.
- Middle East and Africa: Growth is concentrated in the GCC countries, where massive investments in "Medical Cities" are creating a high demand for accredited maintenance services.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Medical Equipment Third Party Calibration Services Market.- Transcat, Inc.
- Tektronix, Inc.
- Fluke Biomedical (Fortive)
- Trescal
- Keysight Technologies
- Agilent Technologies, Inc.
- SIMCO Electronics
- Micro Precision Calibration
- ESSCO Calibration Laboratory
- J.A. King (Cross Company)
- Calibration Laboratory, LLC
- Industrial Calibration and Service
- Technical Laser Care
- Biomedical Technologies Inc.
- Biotek Services, Inc.
- Standard Calibration Services
- Precision Calibration Systems
- Modular Services Company
- Spectrum Technologies
- Nova Biometrics
Frequently Asked Questions
What is the difference between OEM and Third-Party calibration services?
OEM calibration is provided by the device manufacturer, often specifically for their own brand. Third-party calibration is performed by independent laboratories that are typically accredited to ISO/IEC 17025 standards and can service multiple equipment brands under a single service contract, offering cost efficiency and simplified vendor management.
Why is ISO/IEC 17025 accreditation important for medical calibration?
ISO/IEC 17025 is the international standard for the competence of testing and calibration laboratories. It ensures that the provider has a robust quality system, technical competence, and the ability to produce valid, traceable results, which is essential for meeting FDA and European MDR compliance requirements.
How often should medical equipment be calibrated by a third party?
The frequency of calibration depends on the manufacturer’s recommendations, the frequency of use, and the criticality of the device. Typically, most medical devices require annual calibration, though high-risk equipment like defibrillators or anesthesia machines may require more frequent checks every six months.
What are the cost benefits of outsourcing calibration services?
Outsourcing eliminates the need for hospitals to invest in expensive master standards and specialized environmental controls. It also reduces the cost of training and certifying in-house staff, while providing access to a broader range of technical expertise and automated documentation systems.
How is the rise of telemedicine affecting the calibration market?
Telemedicine and remote patient monitoring are increasing the volume of smaller, decentralized medical devices. This is driving a trend toward mobile calibration services and mail-in programs, as service providers adapt to maintain equipment located outside of traditional hospital environments.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
