Biotechnology Instruments Market
Biotechnology Instruments Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710871 | Published On : September 12, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Biotechnology Instruments Market Size
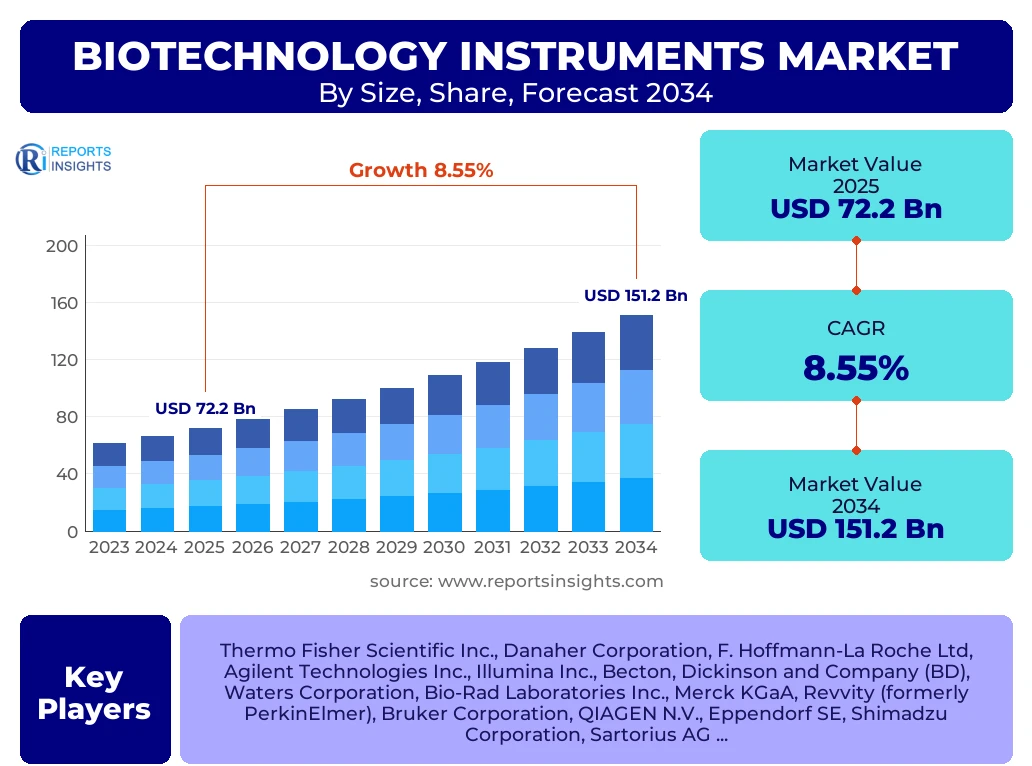
According to Reports Insights Consulting Pvt Ltd, The Biotechnology Instruments Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.55% between 2026 and 2034. The market is estimated at USD 78.4 Billion in 2026 and is projected to reach USD 151.2 Billion by the end of the forecast period in 2034.
Key Biotechnology Instruments Market Trends & Insights
The global biotechnology instruments market is undergoing a profound transformation driven by the integration of artificial intelligence, machine learning, and automation into laboratory workflows. Stakeholders are increasingly seeking high-throughput, precision-oriented tools to accelerate drug discovery and genomic research. The transition toward personalized medicine and the democratization of next-generation sequencing (NGS) are reshaping how research institutions and biopharmaceutical companies invest in capital equipment. Furthermore, the rise of spatial biology and single-cell analysis has created a surge in demand for sophisticated imaging and analytical platforms that offer deeper biological insights than traditional methods.
Regional dynamics indicate a strong shift toward decentralized testing and the expansion of biomanufacturing capabilities in emerging economies. Competitive benchmarking reveals that market leaders are focusing on multi-modal instrument platforms that combine multiple analytical functions into a single unit, thereby optimizing laboratory space and reducing operational costs. Sustainability has also emerged as a critical trend, with manufacturers developing energy-efficient instruments and consumables with reduced plastic waste to align with global environmental goals.
- Largest Region: North America remains the dominant market due to high R&D investment and a robust presence of major biopharmaceutical players.
- Fastest Growing Region: Asia-Pacific is expected to witness the highest CAGR, driven by government initiatives in precision medicine and expanding healthcare infrastructure in China and India.
- Largest Segment by Product: Analytical instruments, specifically Next-Generation Sequencers and Mass Spectrometers, hold the largest market share.
- Largest Segment by End-User: Pharmaceutical and Biotechnology companies lead the market, accounting for over 45% of the total share.
Key Takeaways Biotechnology Instruments Market Size & Forecast
The biotechnology instruments market is characterized by high capital intensity and a rapid rate of obsolescence due to continuous technological breakthroughs. Analysts observe that the market is pivoting from standalone hardware sales to integrated "ecosystem" models that include software-as-a-service (SaaS) for data analysis and long-term service contracts. The forecast period is expected to be defined by a significant uptick in the adoption of automated liquid handling systems and cell-based assay platforms as labor shortages in clinical laboratories persist globally.
- The global market value is set to nearly double by 2034, reflecting the critical role of biotech tools in pandemic preparedness and chronic disease management.
- The United States is the single largest country market, contributing significantly to global revenue through NIH funding and private equity investments.
- Germany and the United Kingdom lead the European market, focusing on advanced microscopy and proteomics research.
- China is rapidly narrowing the gap with Western markets through aggressive domestic manufacturing and supportive regulatory reforms for medical devices.
- Integration of cloud computing and IoT in lab instruments is no longer optional but a standard requirement for enterprise-level laboratories.
Biotechnology Instruments Market Drivers Analysis
The primary catalyst for growth in the biotechnology instruments market is the escalating global demand for personalized medicine and targeted therapies. As the medical community moves away from a one-size-fits-all approach, the need for precise diagnostic and sequencing tools has skyrocketed. Additionally, the rapid expansion of the biopharmaceutical pipeline, particularly in the realms of cell and gene therapy, necessitates advanced analytical instruments for quality control and process development. Government-funded genomic projects, such as large-scale population sequencing initiatives, provide a steady stream of revenue for instrument manufacturers.
Another significant driver is the increasing laboratory automation. To combat rising operational costs and the need for higher reproducibility, laboratories are transitioning toward fully automated systems that minimize human error. The synergy between biotechnology and digital technology—often termed Lab 4.0—is facilitating the adoption of smart instruments that can communicate with Laboratory Information Management Systems (LIMS) in real-time, thereby streamlining the entire research-to-commercialization lifecycle.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Personalized Medicine | +2.45% | Global (Strongest in US & EU) | 2025-2034 |
| Advancements in NGS Technology | +1.80% | Asia-Pacific & North America | 2025-2030 |
| Rise in Biomanufacturing Automation | +1.55% | Germany, Japan, South Korea | 2026-2034 |
| Increased R&D Funding for Proteomics | +1.20% | United Kingdom & China | 2025-2032 |
Biotechnology Instruments Market Restraints Analysis
Despite robust growth, the market faces significant headwinds from the high cost of advanced instrumentation. Sophisticated systems such as cryo-electron microscopes or high-end mass spectrometers require substantial initial investment, often exceeding several million dollars, which poses a barrier to entry for small-scale research laboratories and startups in developing nations. Furthermore, the maintenance and operational costs, including the price of specialized reagents and consumables, add a long-term financial burden that can limit market penetration.
Regulatory hurdles also serve as a restraint, particularly for instruments used in clinical diagnostics. The stringent approval processes by bodies like the FDA and EMA ensure safety and efficacy but also delay the time-to-market for new technologies. Additionally, the shortage of skilled professionals capable of operating complex biotechnology instruments and interpreting high-dimensional data remains a bottleneck for the widespread adoption of advanced analytical platforms.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Capital Expenditure Requirements | -1.20% | Emerging Markets (LATAM, MEA) | 2025-2034 |
| Stringent Regulatory Frameworks | -0.85% | European Union & United States | Ongoing |
| Shortage of Skilled Technicians | -0.60% | Global | 2025-2029 |
Biotechnology Instruments Market Opportunities Analysis
The emergence of point-of-care (POC) biotechnology testing represents a massive opportunity for instrument manufacturers. Developing compact, portable, and user-friendly versions of complex laboratory instruments for use in decentralized settings can tap into the growing home-healthcare and remote diagnostics markets. There is also a significant untapped potential in the integration of AI-driven predictive analytics within instruments, which can provide researchers with real-time experimental optimization and automated data interpretation.
Strategic expansions into emerging economies in Southeast Asia and Latin America offer lucrative prospects as these regions increase their focus on domestic biotechnology self-sufficiency. Furthermore, the development of eco-friendly and "green" laboratory instruments—those that use less energy and fewer hazardous materials—is gaining traction among corporate stakeholders committed to Environmental, Social, and Governance (ESG) goals, providing a competitive edge to early movers in the sustainable instrument space.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| AI-Integrated Analytical Platforms | +2.10% | US, Japan, Germany | 2026-2034 |
| Miniaturization & POC Devices | +1.75% | India, Brazil, Southeast Asia | 2027-2034 |
| Sustainable Lab Solutions (Green Biotech) | +0.95% | Nordic Countries, Canada | 2025-2034 |
Biotechnology Instruments Market Challenges Impact Analysis
Supply chain volatility remains a persistent challenge for the biotechnology instruments sector. The reliance on specialized components, such as high-grade sensors, optical lenses, and semiconductor chips, makes the industry vulnerable to geopolitical tensions and trade disruptions. Additionally, the rapid pace of technological change creates a risk for manufacturers whose products may become obsolete before they can achieve a return on investment, necessitating constant R&D expenditure to stay competitive.
Data security and privacy concerns are also coming to the forefront as instruments become more connected. Protecting sensitive genomic and patient data from cyber threats is a critical challenge for developers of cloud-enabled instruments. Finally, the commoditization of certain low-end laboratory instruments is exerting downward pressure on profit margins, forcing companies to differentiate through service-based business models or niche specializations.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global Supply Chain Instability | -1.10% | Global | 2025-2028 |
| Cybersecurity Risks in Connected Labs | -0.50% | North America & Europe | 2025-2034 |
| Intense Price Competition in Base Models | -0.75% | China & Taiwan Manufacturers | Ongoing |
Biotechnology Instruments Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the biotechnology instruments market across multiple dimensions, including product type, technology, application, and end-user. It provides a detailed evaluation of the hardware, software, and service components that constitute the modern laboratory ecosystem. The analysis covers historical data from 2020 to 2024, establishes a base year in 2025, and provides a strategic forecast through 2034, ensuring a long-term perspective on market evolution and technological shifts.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 72.2 Billion |
| Market Forecast in 2034 | USD 151.2 Billion |
| Growth Rate | 8.55% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Thermo Fisher Scientific Inc., Danaher Corporation, F. Hoffmann-La Roche Ltd, Agilent Technologies Inc., Illumina Inc., Becton, Dickinson and Company (BD), Waters Corporation, Bio-Rad Laboratories Inc., Merck KGaA, Revvity (formerly PerkinElmer), Bruker Corporation, QIAGEN N.V., Eppendorf SE, Shimadzu Corporation, Sartorius AG, Oxford Nanopore Technologies, 10x Genomics, Pacific Biosciences (PacBio). |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The biotechnology instruments market is segmented primarily by product type, which distinguishes between the sophisticated analytical tools used in discovery and the high-volume instruments used in production and diagnostics. Analytical instruments continue to dominate the landscape as they are fundamental to proteomics and metabolomics. The technology-based segmentation highlights the rapid growth of sequencing technologies, which are becoming more affordable and accessible, thereby expanding their use case from research to clinical diagnostics. End-user segmentation reveals a significant shift toward CROs as biopharma companies increasingly outsource their R&D to optimize costs.
- By Product Type: Analytical Instruments, Sequencing Instruments, Microscopy and Imaging, Liquid Handling and Robotics, PCR Systems, Flow Cytometers, Centrifuges, Electrophoresis Systems.
- By Technology: Polymerase Chain Reaction (PCR), Next-Generation Sequencing (NGS), DNA Microarray, Chromatography, Mass Spectrometry, Surface Plasmon Resonance.
- By Application: Drug Discovery, Clinical Diagnostics, Genomic Research, Proteomics, Agricultural Biotechnology, Environmental Testing, Forensic Science.
- By End-User: Pharmaceutical & Biotech Companies, Academic Research Centers, Contract Research Organizations (CROs), Hospitals & Diagnostic Centers, Forensic Laboratories.
Regional Highlights
- North America: Holds the largest market share (approx. 38%) due to a mature biotechnology sector, high concentration of pharmaceutical giants, and robust NIH funding in the United States.
- Europe: Germany and the UK are the primary contributors, with a focus on high-end imaging and diagnostic research instruments. The region is characterized by strict regulatory standards and a strong emphasis on precision medicine.
- Asia-Pacific: The fastest-growing region with a projected CAGR exceeding 10%. China, India, and South Korea are investing heavily in biomanufacturing hubs and genomic surveillance.
- Latin America: Brazil and Mexico are emerging as key markets for diagnostic instruments, driven by an increasing burden of chronic diseases and improving healthcare access.
- Middle East & Africa: Growth is supported by government initiatives to develop local biotechnology capabilities and a rising focus on genetic research in the Gulf states.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Biotechnology Instruments Market.- Thermo Fisher Scientific Inc.
- Danaher Corporation
- F. Hoffmann-La Roche Ltd
- Agilent Technologies Inc.
- Illumina Inc.
- Becton, Dickinson and Company (BD)
- Waters Corporation
- Bio-Rad Laboratories Inc.
- Merck KGaA
- Revvity (formerly PerkinElmer)
- Bruker Corporation
- QIAGEN N.V.
- Eppendorf SE
- Shimadzu Corporation
- Sartorius AG
- Oxford Nanopore Technologies
- 10x Genomics
- Pacific Biosciences (PacBio)
- Tecan Group Ltd.
- Mettler Toledo
Frequently Asked Questions
What is the current market size and forecast for Biotechnology Instruments?
The biotechnology instruments market is estimated at USD 78.4 Billion in 2026 and is expected to reach USD 151.2 Billion by 2034, growing at a CAGR of 8.55%.
Which product segment dominates the biotechnology instruments market?
Analytical instruments, including mass spectrometers and next-generation sequencers, currently hold the largest market share due to their critical role in drug discovery and genomic research.
Who are the leading players in the biotechnology instruments industry?
Top market players include Thermo Fisher Scientific, Danaher, Roche, Agilent Technologies, and Illumina, which collectively hold a significant portion of the global market share.
What are the key drivers for the biotechnology instruments market growth?
Major drivers include the rise of personalized medicine, advancements in NGS technology, increased government R&D funding, and the shift toward laboratory automation (Lab 4.0).
Which region is expected to grow the fastest during the forecast period?
The Asia-Pacific region is projected to be the fastest-growing market, driven by rapid healthcare infrastructure development and government-led biotechnology initiatives in China and India.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
