Biosimilar Monoclonal Antibodies Market
Biosimilar Monoclonal Antibodies Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711538 | Published On : November 05, 2026 |
Format : 


 | Author : Erika Grotto
Biosimilar Monoclonal Antibodies Market Size
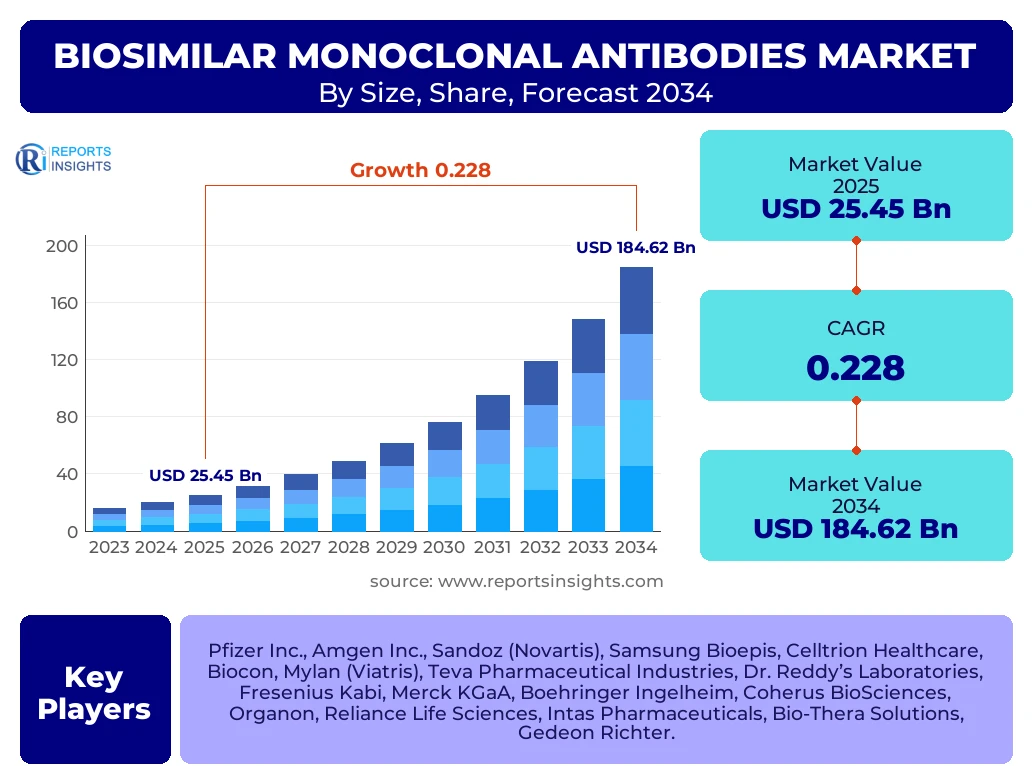
According to Reports Insights Consulting Pvt Ltd, The Biosimilar Monoclonal Antibodies Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 22.8% between 2025 and 2034. The market is estimated at USD 31.25 Billion in 2026 and is projected to reach USD 184.62 Billion by the end of the forecast period in 2034.
Key Biosimilar Monoclonal Antibodies Market Trends & Insights
The global Biosimilar Monoclonal Antibodies market is undergoing a transformative shift characterized by the expiration of patents for high-revenue reference biologics, commonly referred to as the patent cliff. This transition is not merely a price-driven event but a sophisticated evolution of biotechnology manufacturing and regulatory harmonization. Stakeholders are increasingly focusing on interchangeability designations, particularly in the United States, to streamline pharmacy-level substitution and enhance market penetration. Furthermore, the integration of advanced single-use technologies in manufacturing is reducing capital expenditure, allowing smaller players to enter the competitive landscape with greater agility. Strategic collaborations between Western pharmaceutical giants and Asian manufacturing powerhouses are also redefining supply chain dynamics, ensuring that high-quality biosimilars reach diverse geographic demographics more efficiently.
- Largest Region: Europe remains the largest regional market due to an early regulatory framework and high physician acceptance.
- Fastest Growing Region: Asia Pacific is the fastest-growing region, driven by expanding healthcare infrastructure and supportive government policies in China and India.
- Largest Segment: The oncology segment holds the largest market share, attributed to the high volume of monoclonal antibodies used in cancer treatment protocols.
- Emerging Trend: The rise of Bio-betters and subcutaneous formulations is creating new competitive tiers within the biosimilar space.
Key Takeaways Biosimilar Monoclonal Antibodies Market Size & Forecast
The trajectory of the Biosimilar Monoclonal Antibodies market reflects a maturing industry where cost-containment measures by healthcare payers are driving adoption. As healthcare systems grapple with the rising burden of chronic diseases, the shift toward biosimilars is no longer optional but a strategic imperative. Insights suggest that the second wave of biosimilars, focusing on complex molecules like Adalimumab and Pembrolizumab, will generate significantly higher value compared to the first wave. The market is also seeing a consolidation phase where leading players are acquiring smaller biotech firms to bolster their pipelines and gain access to proprietary expression platforms. Market forecasts indicate that the transition from intravenous to subcutaneous delivery methods will be a primary differentiator for market leaders seeking to maintain patient adherence and brand loyalty.
- Market Leadership: Adalimumab biosimilars are expected to remain the highest revenue generators through 2030.
- Regulatory Impact: The FDA Biosimilars Action Plan is significantly reducing approval timelines, fostering a more competitive environment.
- Leading Country: The United States is witnessing the most rapid growth in biosimilar utilization rates following recent legislative reforms.
- Investment Focus: R&D investments are increasingly directed toward therapeutic areas such as ophthalmology and immunology.
Biosimilar Monoclonal Antibodies Market Drivers Analysis
The expansion of the Biosimilar Monoclonal Antibodies market is primarily fueled by the urgent need for affordable biologics in both developed and developing economies. As patents for blockbuster drugs expire, the market is flooded with lower-cost alternatives that maintain the same efficacy and safety profiles, thereby increasing patient access to life-saving therapies. Additionally, government initiatives to reduce healthcare spending and the implementation of favorable reimbursement policies are providing a robust tailwind for market participants. The advancement in analytical characterization tools has also simplified the process of proving biosimilarity, reducing the overall time-to-market for new entrants.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Patent Expiration of Blockbuster Biologics | +8.5% | North America and Europe | 2025 - 2030 |
| Rising Prevalence of Chronic Diseases | +5.2% | Global | 2025 - 2034 |
| Government Cost-Containment Policies | +4.8% | EU-5 Countries | 2025 - 2034 |
| Advancements in Manufacturing Efficiency | +4.3% | Asia Pacific (China/South Korea) | 2026 - 2032 |
Biosimilar Monoclonal Antibodies Market Restraints Analysis
Despite the optimistic growth projections, the market faces significant hurdles related to the complexity of biologics manufacturing and the high costs associated with clinical trials. Unlike small-molecule generics, biosimilars require extensive comparative clinical studies to demonstrate no clinically meaningful differences from the reference product. Furthermore, the aggressive litigation strategies employed by originator companies, often referred to as patent thickets, can delay market entry for years. Physician skepticism regarding the long-term safety and efficacy of switching patients from a stable reference product to a biosimilar also remains a hurdle in certain therapeutic areas.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Complex Regulatory Approval Pathways | -3.2% | United States and Brazil | 2025 - 2028 |
| Aggressive Patent Litigation (Patent Thickets) | -2.8% | North America | 2025 - 2030 |
| High Initial Capital Investment | -2.1% | Global | 2025 - 2034 |
Biosimilar Monoclonal Antibodies Market Opportunities Analysis
The emerging landscape offers significant opportunities in the realm of orphan drugs and specialized therapeutic areas where biologic penetration has historically been low. The development of biosimilars for rare diseases presents a niche market with less competition and potential for premium pricing. Furthermore, the digital transformation of clinical trials, utilizing real-world evidence (RWE), is expected to streamline the post-market surveillance of biosimilars, building greater trust among healthcare providers. Emerging economies in Latin America and Southeast Asia represent untapped markets where rising middle-class populations are demanding better healthcare services, providing a fertile ground for market expansion.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Interchangeability Designation Approvals | +6.4% | United States | 2026 - 2034 |
| Market Expansion in Emerging Economies | +5.1% | India, Brazil, Indonesia | 2027 - 2034 |
| Integration of Real-World Evidence (RWE) | +3.9% | Europe and Japan | 2025 - 2030 |
Biosimilar Monoclonal Antibodies Market Challenges Impact Analysis
Key challenges involve navigating the diverse regulatory requirements across different jurisdictions, which necessitates a localized strategy for global players. The intense price competition, often leading to rapid price erosion, can squeeze profit margins, making it difficult for companies to recoup their R&D investments. Additionally, the rapid pace of innovation by originator companies, who are launching next-generation biologics with superior delivery mechanisms or efficacy, threatens to make existing biosimilar pipelines obsolete before they even reach the market. Maintaining a consistent and sterile supply chain remains a logistical challenge for global distribution.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Intense Price Competition and Erosion | -4.5% | European Union | 2025 - 2034 |
| Supply Chain and Cold-Chain Logistics | -2.4% | Africa and Latin America | 2025 - 2034 |
| Technological Obsolescence by Originators | -3.1% | Global | 2028 - 2034 |
Biosimilar Monoclonal Antibodies Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the global biosimilar monoclonal antibodies landscape, covering molecular types, therapeutic indications, and distribution channels. It provides a detailed evaluation of the competitive environment, regulatory shifts, and technological advancements that are shaping the market. The report includes granular data on market sizing and forecasting, supported by primary and secondary research from industry experts, healthcare providers, and regulatory bodies.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 25.45 Billion |
| Market Forecast in 2034 | USD 184.62 Billion |
| Growth Rate | 22.8% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Pfizer Inc., Amgen Inc., Sandoz (Novartis), Samsung Bioepis, Celltrion Healthcare, Biocon, Mylan (Viatris), Teva Pharmaceutical Industries, Dr. Reddy’s Laboratories, Fresenius Kabi, Merck KGaA, Boehringer Ingelheim, Coherus BioSciences, Organon, Reliance Life Sciences, Intas Pharmaceuticals, Bio-Thera Solutions, Gedeon Richter. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The biosimilar monoclonal antibodies market is segmented based on product type, application, and distribution channel. The product-based segmentation reveals that Adalimumab and Trastuzumab are the dominant contributors, given their wide range of indications and high historical cost of reference products. From an application perspective, oncology leads the market due to the high clinical priority of cancer treatments and the availability of multiple biosimilar versions for molecules like Bevacizumab. The distribution channel analysis indicates that hospital pharmacies remain the primary point of dispensing, although retail and online pharmacies are gaining traction due to the rise of self-administered subcutaneous therapies for autoimmune conditions.
- By Product Type:
- Infliximab Biosimilars
- Rituximab Biosimilars
- Trastuzumab Biosimilars
- Adalimumab Biosimilars
- Bevacizumab Biosimilars
- Ranibizumab Biosimilars
- Others
- By Application:
- Oncology
- Rheumatology
- Gastroenterology
- Dermatology
- Nephrology
- Others
- By Distribution Channel:
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
Regional Highlights
Europe currently represents the most mature market for biosimilar monoclonal antibodies, having established the first regulatory framework (EMA) in 2006. This maturity is reflected in high penetration rates across most therapeutic classes and a well-established tendering process that favors cost-effective options. In contrast, the North American market, led by the United States, is experiencing a surge in growth as the FDA simplifies the biosimilar approval pathway and healthcare payers incentivize the use of lower-cost alternatives over originators.
- North America: The region is characterized by high healthcare spending and a rapid increase in biosimilar approvals. The U.S. is the primary driver of value growth.
- Europe: Germany, France, and the UK are the leading markets, with sophisticated procurement strategies that ensure sustainable competition.
- Asia Pacific: This is the fastest-growing region, with South Korea, China, and India emerging as both major consumers and global manufacturing hubs.
- Latin America: Growth is driven by healthcare reforms in Brazil and Mexico aimed at increasing the availability of biologic therapies in public health systems.
- Middle East & Africa: Market growth is steady, supported by increasing investment in domestic pharmaceutical manufacturing and clinical research.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Biosimilar Monoclonal Antibodies Market.- Pfizer Inc.
- Amgen Inc.
- Sandoz (Novartis AG)
- Samsung Bioepis
- Celltrion Healthcare Co., Ltd.
- Biocon Ltd.
- Viatris Inc. (Mylan)
- Teva Pharmaceutical Industries Ltd.
- Dr. Reddy’s Laboratories
- Fresenius Kabi
- Merck KGaA
- Boehringer Ingelheim
- Coherus BioSciences
- Organon
- Reliance Life Sciences
- Intas Pharmaceuticals
- Bio-Thera Solutions
- Gedeon Richter
- Shanghai Henlius Biotech
- Zydus Cadila
Frequently Asked Questions
Commonly asked questions regarding the Biosimilar Monoclonal Antibodies market focus on regulatory safety, cost-benefit analysis, and future therapeutic trends.
What is the difference between a biosimilar and a generic drug?
Generics are identical copies of small-molecule drugs, while biosimilars are highly similar versions of complex large-molecule biologics. Biosimilars are not identical due to the natural variability of living cells but are proven to have no clinically meaningful differences in safety or efficacy.
What does "interchangeability" mean for biosimilar monoclonal antibodies?
Interchangeability is a regulatory designation in the U.S. that allows a biosimilar to be substituted for the reference product at the pharmacy level without the intervention of the prescribing healthcare provider, similar to how generic drugs are substituted.
Why is the oncology segment the largest in this market?
Oncology treatments often rely on high-cost monoclonal antibodies like Trastuzumab and Bevacizumab. The expiration of patents for these drugs, combined with the high volume of cancer cases globally, makes oncology the highest revenue-generating segment for biosimilars.
How do biosimilars impact healthcare costs?
Biosimilars introduce competition into the market, which typically leads to price reductions of 20% to 50% compared to the reference biologic. This results in billions of dollars in savings for healthcare systems and improved access for patients.
Which region offers the most growth potential for new entrants?
The Asia Pacific region offers the highest growth potential due to its massive patient population, increasing healthcare expenditure, and the presence of several leading biosimilar manufacturers in countries like South Korea and China.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
