Urinary Catheters Market
Urinary Catheters Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711003 | Published On : September 27, 2026 |
Format : 


 | Author : Erika Grotto
Urinary Catheters Market Size
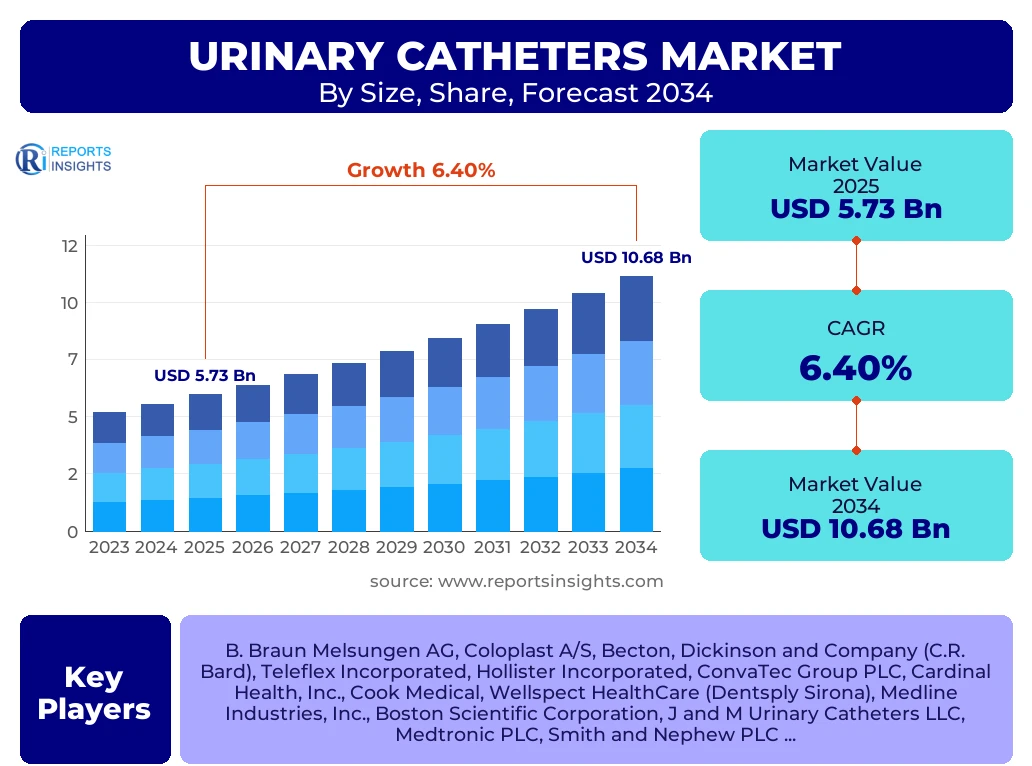
According to Reports Insights Consulting Pvt Ltd, The Urinary Catheters Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.4% between 2026 and 2034. The market is estimated at USD 6.1 Billion in 2026 and is projected to reach USD 10.68 Billion by the end of the forecast period in 2034.
Key Urinary Catheters Market Trends & Insights
The global urinary catheters market is currently undergoing a significant transformation driven by technological advancements in material science and an increasing clinical preference for intermittent catheterization over indwelling alternatives. A primary focus within the industry is the reduction of Catheter-Associated Urinary Tract Infections (CAUTIs), which remain one of the most prevalent hospital-acquired infections globally. Market participants are increasingly investing in antimicrobial and hydrophilic coatings to improve patient comfort and safety. Furthermore, the shift toward home-based care models is accelerating the demand for user-friendly, portable, and discreet catheter designs tailored for self-administration. Regional analysis indicates that while North America maintains the highest market share due to advanced healthcare infrastructure, the Asia-Pacific region is poised for the most rapid growth, fueled by rising geriatric populations and improving access to urological treatments in emerging economies.
- Largest Region: North America remains the dominant regional market, accounting for over 35% of the global value share, driven by high healthcare expenditure and a robust regulatory framework for medical devices.
- Fastest Growing Region: Asia-Pacific is identified as the fastest-growing market with a projected CAGR exceeding 7.5%, attributed to increasing medical tourism and expanding healthcare coverage in China and India.
- Leading Product Segment: Intermittent catheters represent the largest and fastest-growing segment by product type, favored for their lower risk of infection and clinical versatility.
- Top Application: Urinary incontinence treatment serves as the primary application driver, followed by surgical procedures and neurological disorders.
Key Takeaways Urinary Catheters Market Size & Forecast
The market trajectory for urinary catheters is characterized by consistent growth across both developed and developing regions. Stakeholders are focusing on "single-use" strategies to mitigate cross-contamination risks, a trend that is significantly boosting the volume of intermittent catheters sold annually. Market forecasts suggest that the integration of digital health monitoring and smart catheter technologies will provide new avenues for growth toward the latter half of the decade. The industry is also seeing a consolidation of key players who are acquiring smaller, innovative startups specializing in biocompatible materials and specialized pediatric urology products. Regulatory shifts, particularly the implementation of the EU Medical Device Regulation (MDR), are necessitating higher clinical evidence standards, influencing product development cycles for all manufacturers.
- Strategic Market Expansion: Global revenue is expected to surpass the USD 10 billion mark by 2034, highlighting the essential nature of urological care.
- Dominant Country: The United States leads the global market in terms of both consumption volume and the adoption of high-cost, advanced coated catheters.
- Clinical Shift: There is a definitive clinical shift toward hydrophilic-coated catheters which reduce urethral trauma and enhance long-term patient compliance.
- Demographic Influence: The global surge in the population aged 65 and over is the single most significant demographic factor sustaining long-term market demand.
Urinary Catheters Market Drivers Analysis
The primary catalyst for the urinary catheters market is the global rise in the geriatric population, which is inherently more susceptible to conditions such as urinary retention, prostate cancer, and fecal incontinence. Clinical studies have shown that urological disorders increase in prevalence with age, necessitating the use of both temporary and long-term catheterization solutions. Furthermore, the increasing incidence of spinal cord injuries and neurological conditions like multiple sclerosis and Parkinson’s disease—which often lead to neurogenic bladder dysfunction—is creating a stable and growing patient base requiring intermittent catheterization.
Technological innovation serves as a secondary but vital driver. The development of specialized coatings, such as silver-ion and antibiotic-impregnated surfaces, has directly addressed the medical community's concerns regarding healthcare-associated infections. This innovation not only improves patient outcomes but also reduces the overall cost of care by shortening hospital stays. Additionally, favorable reimbursement policies in developed markets like Germany, France, and the UK for home-care urological supplies are encouraging patients to opt for high-quality, single-use products over traditional reusable options.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Aging Global Population and Prevalence of BPH | +2.8% | Global (High impact in Japan, EU, USA) | 2025-2034 |
| Advancements in Antimicrobial and Hydrophilic Coatings | +1.5% | North America and Europe | 2025-2030 |
| Rise in Surgical Procedures Requiring Post-Op Drainage | +1.2% | Emerging Economies (APAC, LATAM) | 2026-2034 |
Urinary Catheters Market Restraints Analysis
A significant restraint facing the market is the persistent risk of Catheter-Associated Urinary Tract Infections (CAUTIs), which leads to increased morbidity and healthcare costs. Despite improvements in materials, the presence of a foreign body in the urinary tract remains a primary site for biofilm formation. This risk often prompts clinicians to limit the duration of catheterization or seek alternative non-invasive drainage methods where possible. Regulatory scrutiny regarding the chemicals used in catheter manufacturing, such as DEHP and other phthalates, also poses a challenge for manufacturers who must reformulate products to meet strict environmental and health safety standards.
Economic constraints in low-income regions further hinder market penetration. The high cost of advanced, single-use hydrophilic catheters compared to traditional PVC or latex indwelling catheters makes them less accessible in price-sensitive markets. This leads to the continued use of reusable catheters in some developing nations, which carries a higher risk of infection and limits the growth of the premium catheter segment. Additionally, the shortage of specialized urological nursing staff in certain regions can lead to improper catheter management and subsequent complications, negatively impacting market perception.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Risk of CAUTIs and Biofilm Formation | -1.4% | Global (Hospital settings) | 2025-2034 |
| Strict Regulatory Requirements (EU MDR, FDA) | -0.8% | Europe and North America | 2025-2028 |
| Preference for Non-Invasive Urinary Management | -0.6% | Developed Markets | 2027-2034 |
Urinary Catheters Market Opportunities Analysis
The expansion of telehealth and remote patient monitoring presents a unique opportunity for the urinary catheters market. Companies can integrate "smart" features into catheter systems that alert patients or caregivers to potential blockages or early signs of infection via mobile applications. This transition toward digital urology is expected to gain traction in the coming decade, particularly in the home-care segment where self-management is critical. Furthermore, the development of eco-friendly and biodegradable catheters is an emerging niche, as healthcare systems worldwide aim to reduce medical plastic waste.
There is also significant untapped potential in emerging markets such as Brazil, India, and Southeast Asia. As healthcare infrastructure in these regions matures and insurance coverage expands to include urological supplies, the volume of catheter sales is expected to rise sharply. Strategic partnerships between global manufacturers and local distributors can facilitate the introduction of specialized products, such as pediatric catheters and gender-specific designs, which are currently under-represented in these markets. R&D investments into "no-touch" catheter systems also offer a pathway to capturing the self-catheterization market by simplifying the process for patients with limited dexterity.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of Smart Sensing Technologies | +1.9% | USA, Germany, South Korea | 2028-2034 |
| Expansion into Home Healthcare and Self-Care | +1.3% | Global | 2025-2034 |
| Growth in Medical Tourism for Urological Surgeries | +0.9% | Thailand, India, Mexico | 2026-2032 |
Urinary Catheters Market Challenges Impact Analysis
One of the foremost challenges is the volatility in the global supply chain for medical-grade raw materials, including silicone and high-quality plastics. Disruptions in the supply chain can lead to manufacturing delays and increased costs, which are difficult to pass on to consumers in highly regulated, price-capped healthcare environments. Additionally, the intense competitive landscape leads to price erosion, particularly in the generic catheter segment, forcing companies to constantly innovate to maintain profit margins. Intellectual property litigation also remains a challenge, as companies defend their proprietary coatings and design mechanisms.
Ensuring patient compliance and proper education represents a persistent hurdle. Improper insertion techniques, especially in the home setting, lead to urethral trauma and infections, which may cause patients to discontinue use or switch to alternative therapies. Manufacturers must invest heavily in educational programs and user training to ensure their products are used correctly. Furthermore, the environmental impact of single-use plastics is drawing increased attention from environmental regulators, potentially leading to future taxes or restrictions on disposable medical products that lack a clear recycling or disposal pathway.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Raw Material Price Volatility and Supply Constraints | -0.7% | Global | 2025-2027 |
| Patient Non-Compliance and Mismanagement | -0.5% | Home Care Segment | 2025-2034 |
| Sustainability and Plastic Waste Regulations | -0.4% | Europe and North America | 2029-2034 |
Urinary Catheters Market - Updated Report Scope
This market research report provides a comprehensive analysis of the global urinary catheters industry, covering historical performance from 2020 to 2024 and providing a rigorous forecast through 2034. The scope encompasses detailed segmentation by product type, coating material, application, and end-user, while also providing granular regional insights. The report evaluates the competitive landscape through company profiling, market share analysis, and a review of strategic initiatives such as mergers, acquisitions, and product launches. Technical assessments of material science advancements and regulatory updates are also included to provide a 360-degree view of the market ecosystem.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 5.73 Billion |
| Market Forecast in 2034 | USD 10.68 Billion |
| Growth Rate | 6.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | B. Braun Melsungen AG, Coloplast A/S, Becton, Dickinson and Company (C.R. Bard), Teleflex Incorporated, Hollister Incorporated, ConvaTec Group PLC, Cardinal Health, Inc., Cook Medical, Wellspect HealthCare (Dentsply Sirona), Medline Industries, Inc., Boston Scientific Corporation, J and M Urinary Catheters LLC, Medtronic PLC, Smith and Nephew PLC, Terumo Corporation, Amsino International, Inc., Manfred Sauer GmbH, Hunter Urology. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The urinary catheters market is highly segmented based on product functionality and clinical application, reflecting the diverse needs of patients across different healthcare settings. The intermittent catheter segment currently holds the largest market share, as it is widely considered the "gold standard" for managing urinary retention and neurogenic bladder while minimizing the long-term risks associated with indwelling devices. Foley catheters remain indispensable for critical care and perioperative settings, though their growth is slightly moderated by concerns over infection. External catheters, primarily condom catheters for males, are gaining popularity in the home-care segment due to their non-invasive nature and ease of use.
- Product Type: Intermittent Catheters (Hydrophilic, Non-hydrophilic), Foley/Indwelling (2-way, 3-way), External/Condom Catheters.
- Coating Technology: Hydrophilic Coating, Silver-Ion/Antimicrobial Coating, Silicone Elastomer, PTFE (Teflon) Coating.
- Application: Urinary Incontinence, General Surgery, Urological Disorders, Neurology, Oncology.
- Gender-Specific Design: Male (Standard length), Female (Short/Compact length), Pediatric (Smaller French sizes).
- End-User: Hospitals (Acute care), Rehabilitation Centers, Home Healthcare Providers, Nursing Homes.
Regional Highlights
- North America: The largest market share holder, driven by a high prevalence of urological disorders and an established reimbursement system for advanced catheter technologies. The United States is the primary contributor to regional growth.
- Europe: A mature market with a strong emphasis on clinical guidelines that favor intermittent catheterization. Countries like Germany and the UK are leaders in the adoption of hydrophilic-coated products.
- Asia-Pacific: The fastest-growing region, characterized by rapid healthcare infrastructure development and a massive geriatric population base in China, Japan, and India. Rising disposable income is increasing the demand for premium urological supplies.
- Latin America: Expected to show steady growth as countries like Brazil and Mexico improve access to specialized urological procedures in public and private hospitals.
- Middle East & Africa: A growing market influenced by increasing investments in healthcare facilities and a rising incidence of diabetes-related bladder complications.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Urinary Catheters Market.- B. Braun Melsungen AG
- Coloplast A/S
- Becton, Dickinson and Company (BD/C.R. Bard)
- Teleflex Incorporated
- Hollister Incorporated
- ConvaTec Group PLC
- Cardinal Health, Inc.
- Cook Medical
- Wellspect HealthCare (Dentsply Sirona)
- Medline Industries, Inc.
- Boston Scientific Corporation
- J and M Urinary Catheters LLC
- Medtronic PLC
- Smith and Nephew PLC
- Terumo Corporation
- Amsino International, Inc.
- Manfred Sauer GmbH
- Hunter Urology
- Poiesis Medical
- Urocare Products, Inc.
Frequently Asked Questions
What is the current market size of the global urinary catheters industry?
The urinary catheters market is estimated to be valued at approximately USD 6.1 Billion in 2026, with a projected growth path toward USD 10.68 Billion by 2034.
Which product segment is leading the urinary catheters market?
The Intermittent Catheter segment currently leads the market due to its effectiveness in reducing the risk of catheter-associated urinary tract infections (CAUTIs) compared to indwelling catheters.
Which region is expected to grow the fastest between 2025 and 2034?
The Asia-Pacific region is forecasted to be the fastest-growing market, driven by expanding healthcare infrastructure and a rapidly aging population in major economies like China and India.
How do antimicrobial coatings impact the market?
Antimicrobial coatings, such as those using silver ions or antibiotics, are key growth drivers because they significantly reduce the incidence of infections, which is a major concern for hospitals and long-term care facilities.
What are the main drivers for the urinary catheters market growth?
Primary drivers include the global increase in the geriatric population, the rising prevalence of urological diseases, and the shift toward home-based healthcare and self-catheterization.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted