Biodegradable Lids Market
Biodegradable Lids Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711702 | Published On : November 12, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Biodegradable Lids Market Size
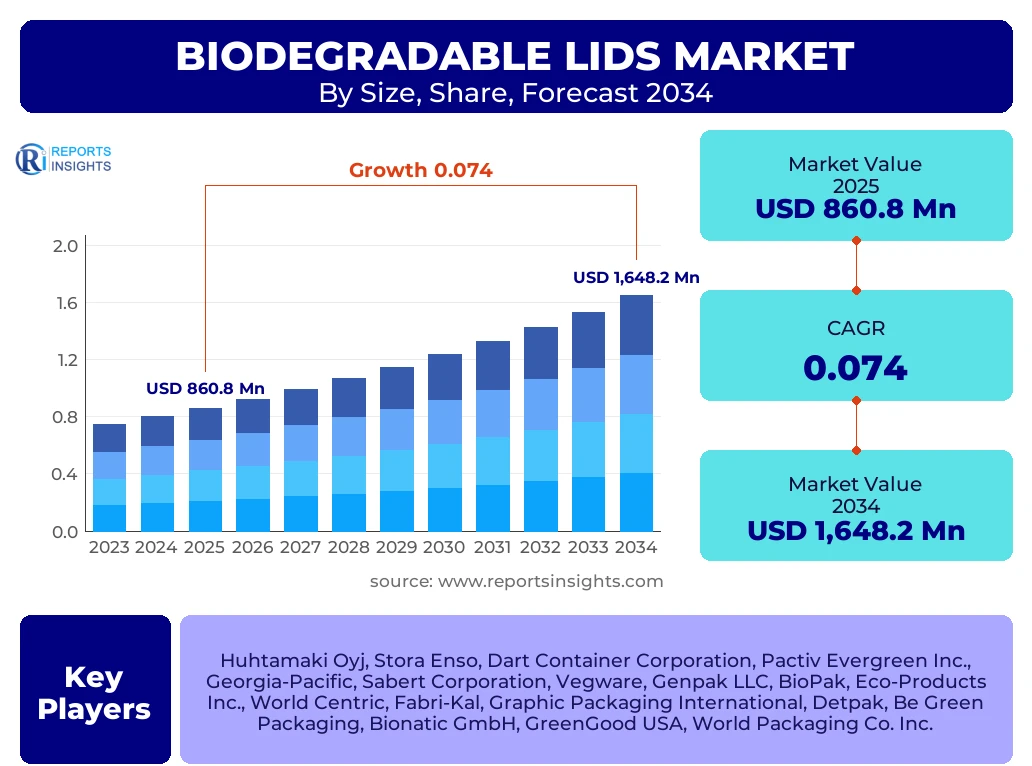
According to Reports Insights Consulting Pvt Ltd, The Biodegradable Lids Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.4% between 2025 and 2034. The market is estimated at USD 924.5 Million in 2026 and is projected to reach USD 1,648.2 Million by the end of the forecast period in 2034.
Key Biodegradable Lids Market Trends & Insights
The global shift toward a circular economy has fundamentally altered the trajectory of the biodegradable lids market. Industry participants are increasingly pivoting from traditional Polylactic Acid (PLA) solutions toward molded fiber and bagasse-based alternatives, which offer superior home-compostability profiles. Current market intelligence suggests that consumer perception of sustainability is no longer satisfied by industrial compostability alone; there is a rising demand for products that decompose in backyard settings without requiring specialized facilities. Furthermore, the integration of PFAS-free moisture barriers is becoming a standard requirement as health and safety regulations tighten across North America and Europe. Competitive benchmarking reveals that market leaders are investing heavily in material science to enhance the thermal resistance of biodegradable lids, specifically addressing the performance gap traditionally held by petroleum-based plastics in hot beverage applications.
- Fastest Growing Region: Asia Pacific (APAC) is anticipated to witness the highest CAGR, driven by rapid urbanization and aggressive plastic ban implementations in China and India.
- Largest Market Share: North America remains the largest region by value, supported by a mature quick-service restaurant (QSR) infrastructure and high consumer willingness to pay a premium for eco-friendly packaging.
- Leading Material Segment: Paper and Molded Fiber segments currently hold the largest share due to their cost-effectiveness and perceived natural origin compared to bio-plastics.
- Primary End-User: The Foodservice and Specialty Coffee Shop sector represents the most significant revenue contributor to the global market.
Key Takeaways Biodegradable Lids Market Size & Forecast
The forecast period from 2026 to 2034 is expected to be defined by a massive transition in procurement strategies among global food chains. As corporations commit to Environmental, Social, and Governance (ESG) goals, the replacement of traditional polystyrene (PS) and polypropylene (PP) lids with biodegradable counterparts has moved from a niche marketing strategy to a core operational requirement. Market analysis indicates that while initial costs remain higher than conventional plastics, economies of scale and improvements in manufacturing efficiency are narrowing the price gap. The market is also seeing a surge in regional manufacturing hubs to reduce the carbon footprint associated with long-distance shipping, which is particularly relevant for low-margin, high-volume products like beverage lids.
- United States Dominance: The US market continues to lead in innovation, particularly in the development of seaweed-based and mushroom-based biodegradable polymers.
- EU Regulatory Pressure: The European Union Single-Use Plastics Directive remains the strongest catalyst for market volume growth within the Eurozone.
- Material Evolution: Bagasse and Bamboo-based lids are gaining rapid traction in the premium segment due to their tactile feel and aesthetic appeal.
- Logistical Localization: Strategic focus is shifting toward "near-shoring" production to mitigate supply chain disruptions and align with local sustainability mandates.
Biodegradable Lids Market Drivers Analysis
The primary driver for the biodegradable lids market is the global legislative crackdown on single-use plastics. Governments worldwide are implementing bans and levies that make traditional plastic lids economically unviable or legally prohibited. This regulatory tailwind is complemented by a profound shift in consumer psychology, where Gen Z and Millennial cohorts actively boycott brands that utilize non-recyclable or non-compostable packaging. Additionally, the rapid expansion of the coffee culture in emerging economies is creating a massive volume demand for disposable lids that do not contribute to long-term landfill waste.
Corporate sustainability mandates have also evolved from voluntary targets to mandatory reporting requirements. Major beverage retailers are now including packaging sustainability in their annual reports, which forces a top-down implementation of biodegradable alternatives across their entire supply chain. This systemic change ensures a stable and growing demand regardless of short-term economic fluctuations.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Government Regulations and Plastic Bans | +2.8% | European Union, China, India | 2025 - 2034 |
| Consumer Preference for Sustainable QSR Packaging | +1.5% | Global | 2025 - 2030 |
| Expansion of Specialty Coffee Chains | +1.2% | USA, South Korea, Japan | 2026 - 2034 |
Biodegradable Lids Market Restraints Analysis
Despite the positive growth trajectory, the market faces significant headwinds related to raw material price volatility. The feedstocks for biodegradable polymers, such as corn starch or sugarcane, are subject to agricultural cycles and climate-related disruptions, which can lead to unpredictable pricing for manufacturers. Furthermore, the functional limitations of certain biodegradable materials—such as their inability to maintain structural integrity under extreme heat or for prolonged periods—remain a concern for hot beverage retailers who prioritize lid security and spill prevention.
Another critical restraint is the lack of standardized composting infrastructure globally. In many regions, "compostable" lids end up in landfills where they fail to decompose properly due to anaerobic conditions, leading to "greenwashing" accusations against brands. This infrastructure gap can discourage long-term investment in specific types of biodegradable materials that require industrial processing.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Raw Materials | -1.1% | Global | 2025 - 2028 |
| Inadequate Industrial Composting Infrastructure | -0.8% | Developing Nations (SEA, LATAM) | 2025 - 2034 |
Biodegradable Lids Market Opportunities Analysis
There is a substantial opportunity in the development of "Next-Gen" materials such as PHA (polyhydroxyalkanoates) and seaweed-derived polymers. These materials are marine-degradable and do not require specific industrial conditions to break down, positioning them as the ultimate solution for plastic pollution. Companies that can successfully commercialize these materials at scale will likely capture significant market share in the coming decade. Additionally, the customization and branding of biodegradable lids through embossed logos and eco-friendly inks provide an avenue for premium pricing.
Furthermore, the untapped potential in the healthcare and institutional catering sectors presents a massive opportunity. Hospitals, schools, and government offices are increasingly mandated to use sustainable serving ware, creating high-volume, long-term contract opportunities for biodegradable lid manufacturers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of PHA and Marine-Degradable Materials | +1.9% | North America, Northern Europe | 2027 - 2034 |
| Adoption in Healthcare and Institutional Segments | +1.1% | Global | 2026 - 2034 |
Biodegradable Lids Market Challenges Impact Analysis
One of the most pressing challenges is the technical difficulty of achieving a "snap-fit" seal with fiber-based materials that matches the precision of injection-molded plastic. Achieving a leak-proof seal is paramount for the safety of hot coffee drinkers, and any failure in this area can lead to significant liability issues for food vendors. Manufacturers are currently struggling to balance the thickness and weight of the lid with its biodegradable properties and cost.
Additionally, the global supply chain remains vulnerable to geopolitical tensions and trade barriers. Since many of the raw materials and manufacturing hubs are concentrated in specific geographic regions, shifts in trade policy or shipping costs can significantly impact the final price of the product in distant markets like Europe or North America.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Maintaining Seal Precision and Leak Resistance | -0.7% | Global | 2025 - 2029 |
| Trade Barriers and Supply Chain Volatility | -0.5% | Asia to North America/Europe | 2025 - 2030 |
Biodegradable Lids Market - Updated Report Scope
The scope of this report encompasses a granular analysis of the global biodegradable lids industry, focusing on material innovation, regulatory frameworks, and end-user adoption patterns. It provides a comprehensive outlook on how different substrates, ranging from traditional CPLA to advanced aqueous-coated fibers, are performing across various temperature and application settings. The study includes detailed competitive landscapes and financial forecasts through 2034, categorized by region, material, and product type.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 860.8 Million |
| Market Forecast in 2034 | USD 1,648.2 Million |
| Growth Rate | 7.4% CAGR |
| Number of Pages | 254 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Huhtamaki Oyj, Stora Enso, Dart Container Corporation, Pactiv Evergreen Inc., Georgia-Pacific, Sabert Corporation, Vegware, Genpak LLC, BioPak, Eco-Products Inc., World Centric, Fabri-Kal, Graphic Packaging International, Detpak, Be Green Packaging, Bionatic GmbH, GreenGood USA, World Packaging Co. Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the biodegradable lids market reveals a complex interplay between material performance and application requirements. Currently, the Paper and Molded Fiber segment is the dominant force, as it aligns perfectly with the aesthetic and tactile expectations of the sustainable packaging movement. However, the Polylactic Acid (PLA) segment remains vital for cold beverage applications where transparency is a key marketing feature. Within applications, the Hot Beverage segment is undergoing the most significant transformation, as manufacturers race to develop lids that can withstand temperatures above 90 degrees Celsius without softening or losing their seal integrity.
- By Material:
- Paper/Molded Fiber (Largest segment by volume and consumer preference)
- Bagasse (Fastest growing for food packaging due to oil resistance)
- Polylactic Acid (PLA) (High usage in cold beverages and clear lid applications)
- Wood and Bamboo (Premium niche segment for high-end cafes)
- By Product Type:
- Sip Lids (Standard for coffee and tea service)
- Dome Lids (Dominant in specialty drinks like frappes and smoothies)
- Flat Lids (Widely used for cold sodas and food containers)
- By Application:
- Hot Beverages (Primary driver of R&D for thermal stability)
- Cold Beverages (Focus on clarity and moisture resistance)
- Food Packaging (Increasing demand for take-out and delivery services)
Regional Highlights
- North America: Holds the highest market value share. The presence of major global coffee chains and strict municipal-level plastic bans in states like California and New York drive steady demand.
- Europe: The most regulated market. The EU Single-Use Plastics (SUP) Directive has forced a near-total transition in several countries, making Europe a leader in the adoption of fiber-based alternatives.
- Asia Pacific: The fastest-growing region. China’s "zero-plastic" policy and India’s ban on specific single-use items have created an immediate and massive market for domestic biodegradable manufacturers.
- Latin America: Emerging market with high growth potential in Brazil and Chile, where environmental awareness is rising among the middle class.
- Middle East & Africa: Growth is centered around tourism hubs like Dubai and Riyadh, where international hotel and food chains are implementing global sustainability standards.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Biodegradable Lids Market.- Huhtamaki Oyj
- Stora Enso
- Dart Container Corporation
- Pactiv Evergreen Inc.
- Georgia-Pacific
- Sabert Corporation
- Vegware
- Genpak LLC
- BioPak
- Eco-Products Inc.
- World Centric
- Fabri-Kal
- Graphic Packaging International
- Detpak
- Be Green Packaging
- Bionatic GmbH
- GreenGood USA
- World Packaging Co. Inc.
Frequently Asked Questions
What is the difference between compostable and biodegradable lids?
While all compostable lids are biodegradable, not all biodegradable lids are compostable. Biodegradable refers to materials that break down by biological processes, whereas compostable specifically means they break down into non-toxic components under specific composting conditions within a defined timeframe. Most high-quality biodegradable lids today are designed to be industrially compostable.
Can biodegradable lids handle boiling hot beverages?
Modern biodegradable lids, specifically those made from CPLA (Crystallized PLA) or high-density molded fiber with aqueous coatings, are engineered to withstand temperatures up to 200°F (93°C). However, standard PLA lids are usually restricted to cold beverages as they can deform at temperatures above 110°F.
Are these lids truly PFAS-free?
Leading manufacturers are rapidly phasing out PFAS (forever chemicals) used for grease and water resistance. Current industry standards are shifting toward aqueous-based coatings or natural wax barriers to ensure the lids meet new health and safety regulations in the US and Europe.
How much more expensive are biodegradable lids compared to plastic?
Generally, biodegradable lids cost between 15% to 40% more than conventional plastic lids. However, this price gap is narrowing as manufacturing technology improves and the cost of plastic increases due to environmental taxes and carbon pricing.
Which material is best for environmental sustainability?
Molded fiber and bagasse (sugarcane pulp) are currently considered the most sustainable options because they are home-compostable and often utilize agricultural waste products, whereas PLA requires industrial facilities and high-input crops like corn.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
