Automotive Thermoformed Plastics Parts Packaging Market
Automotive Thermoformed Plastics Parts Packaging Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710992 | Published On : September 25, 2026 |
Format : 


 | Author : Ashraf Shehata
Automotive Thermoformed Plastics Parts Packaging Market Size
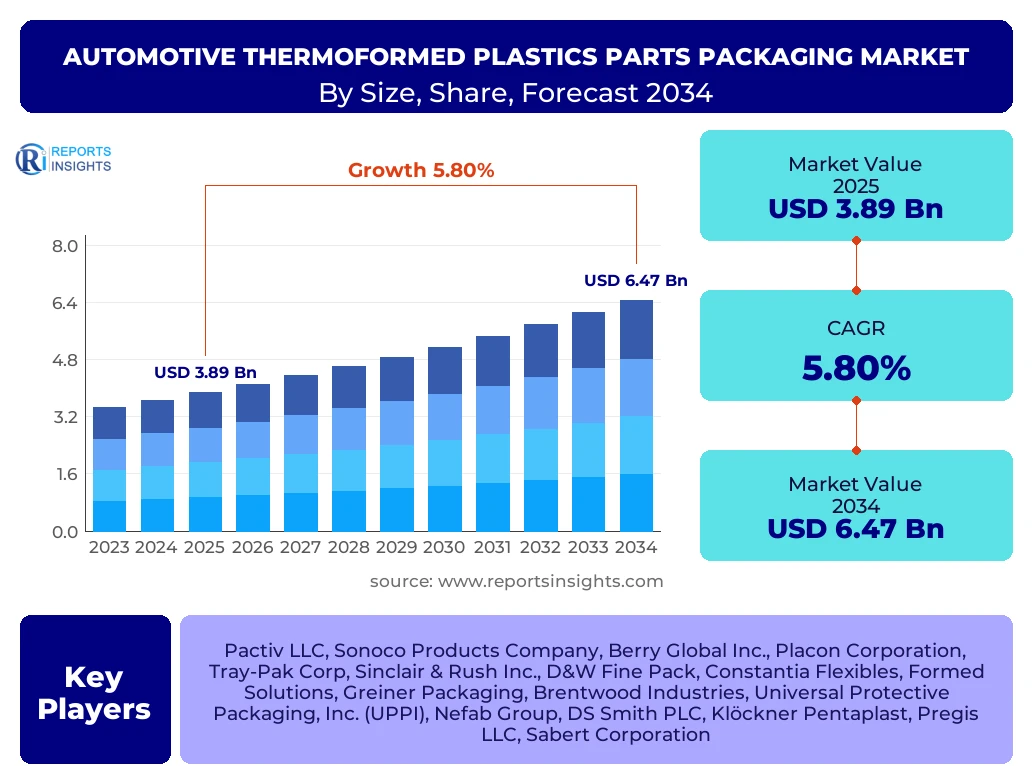
According to Reports Insights Consulting Pvt Ltd, The Automotive Thermoformed Plastics Parts Packaging Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.8% between 2026 and 2034. The market is estimated at USD 4.12 Billion in 2026 and is projected to reach USD 6.47 Billion by the end of the forecast period in 2034.
Key Automotive Thermoformed Plastics Parts Packaging Market Trends & Insights
The global demand for automotive thermoformed plastics parts packaging is being fundamentally reshaped by the rapid transition toward electric vehicles (EVs) and the automotive industry's pursuit of circular economy goals. Market participants and enterprise stakeholders are increasingly focusing on regional supply chain optimization, specifically seeking high-durability, lightweight dunnage solutions that reduce logistics costs while ensuring the safety of sensitive electronic components. User queries often center on the balance between material performance and sustainability, reflecting a shift toward post-consumer recycled (PCR) content in thermoforming processes. Furthermore, the integration of smart packaging technologies, such as RFID and QR tracking embedded directly into thermoformed trays, is emerging as a critical trend for inventory management in automated manufacturing environments.
- Asia-Pacific remains the largest and fastest-growing region, driven by massive vehicle production volumes in China and India and a burgeoning EV component manufacturing ecosystem.
- Polypropylene (PP) stands as the largest material segment due to its excellent chemical resistance, high impact strength, and favorable cost-to-performance ratio in heavy-duty packaging applications.
- Customized Trays and Dunnage represent the largest packaging type segment, as OEMs require precision-engineered solutions to protect delicate engine parts and electronic sensors during transit.
- Sustainability-driven Innovation is the primary trend, with manufacturers adopting closed-loop recycling programs to reclaim and reuse thermoformed packaging within the automotive supply chain.
Key Takeaways Automotive Thermoformed Plastics Parts Packaging Market Size & Forecast
Analysis of market intelligence and common industry inquiries reveals a significant emphasis on the scalability of thermoforming processes compared to injection molding for large-format automotive protective packaging. Stakeholders are particularly interested in the forecast period's stability, given the volatility of polymer prices and the shifting landscape of global trade regulations. The market is characterized by a high degree of technical specialization, where the ability to produce multi-layered, anti-static, and flame-retardant thermoformed parts provides a significant competitive advantage. The forecast suggests that as the complexity of automotive sub-assemblies increases, the reliance on specialized thermoformed packaging will outpace generic packaging alternatives.
- China and the United States are the leading country markets, together accounting for a substantial share of global demand due to their advanced automotive manufacturing infrastructures.
- The Electric Vehicle (EV) Sector is the primary catalyst for market expansion, requiring specialized packaging for battery cells, modules, and power electronics that necessitate high dielectric strength.
- Operational Efficiency is a key takeaway, as thermoformed packaging allows for nestable designs that significantly reduce return-logistics costs and storage space requirements for OEMs.
- Technological Convergence between thermoforming and automation is enabling faster production cycles and higher precision, meeting the rigorous standards of Tier-1 automotive suppliers.
Automotive Thermoformed Plastics Parts Packaging Market Drivers Analysis
The growth of the Automotive Thermoformed Plastics Parts Packaging Market is propelled by several macro-economic and industry-specific factors. The primary driver is the global shift toward lightweighting in vehicle design, which extends to the packaging and logistics sector to minimize carbon footprints. As automotive components become more sophisticated, the demand for protective, shock-absorbent, and chemically resistant packaging solutions that only thermoforming can cost-effectively provide is surging. Additionally, the rapid expansion of global automotive trade necessitates durable packaging that can withstand long-duration sea and land transit.
Furthermore, the rising adoption of just-in-time (JIT) manufacturing processes requires packaging that is highly organized and compatible with robotic assembly lines. The cost-efficiency of thermoforming, particularly for low to medium-volume production runs and large parts, makes it the preferred choice over traditional injection molding for specialized automotive dunnage and shipping trays.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Acceleration of Electric Vehicle (EV) Production | +1.5% | Global (Strongest in China, Germany, USA) | 2025 - 2034 |
| Demand for Lightweight and Durable Logistics Solutions | +1.2% | North America and Europe | 2025 - 2030 |
| Growth in Aftermarket Component Distribution | +0.9% | Asia-Pacific and Latin America | 2026 - 2034 |
| Adoption of Recyclable Polymer Materials | +0.7% | European Union | 2025 - 2034 |
Automotive Thermoformed Plastics Parts Packaging Market Restraints Analysis
Despite the positive growth trajectory, the market faces significant restraints primarily related to the volatility of raw material prices. Since thermoformed packaging relies heavily on petroleum-based polymers like PP, PET, and ABS, fluctuations in global oil prices directly impact manufacturing costs and profit margins. Environmental regulations targeting plastic waste and the push for plastic-free packaging alternatives in some regions also pose a long-term threat to traditional thermoforming practices.
Additionally, the technical limitations of thermoforming, such as the difficulty in achieving uniform wall thickness for extremely complex geometries, can sometimes lead manufacturers to seek alternative molding processes. The high energy consumption associated with large-scale thermoforming operations also remains a concern for companies striving to meet stringent ESG (Environmental, Social, and Governance) targets.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility in Polymer Raw Material Pricing | -0.8% | Global | 2025 - 2028 |
| Stringent Plastic Waste Management Regulations | -0.6% | Europe and North America | 2027 - 2034 |
| Competition from Alternative Materials (Molded Fiber) | -0.4% | Developed Economies | 2028 - 2034 |
Automotive Thermoformed Plastics Parts Packaging Market Opportunities Analysis
The market is ripe with opportunities, particularly in the development of bio-based and biodegradable thermoformed plastics. As automotive manufacturers look to green their entire supply chain, packaging companies that can provide high-performance, plant-based alternatives will capture significant market share. Another major opportunity lies in the integration of Internet of Things (IoT) sensors within thermoformed packaging, allowing for real-time monitoring of sensitive parts' temperature, humidity, and vibration during transit.
The expansion of the automotive sector in emerging economies such as Southeast Asia, Brazil, and Mexico provides a fertile ground for market entry. Furthermore, the trend toward customization and small-batch vehicle production (especially in the luxury and performance segments) allows for the use of thermoforming's lower tooling costs to create highly specialized, low-volume packaging solutions that were previously cost-prohibitive.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Bio-Based Thermoformed Plastics | +1.1% | Global (Europe Lead) | 2026 - 2034 |
| Smart Packaging Integration (IoT/RFID) | +0.8% | North America and Japan | 2025 - 2030 |
| Expansion into Emerging Markets (ASEAN/LATAM) | +1.3% | Vietnam, Thailand, Brazil | 2027 - 2034 |
Automotive Thermoformed Plastics Parts Packaging Market Challenges Impact Analysis
A significant challenge in the Automotive Thermoformed Plastics Parts Packaging Market is the high cost of specialized tooling and molds for large-scale automotive components. While thermoforming is cheaper than injection molding for many applications, the precision required for modern automotive parts necessitates high-grade aluminum molds that require significant upfront investment. This can be a barrier for smaller packaging firms looking to enter the high-end automotive segment.
Moreover, the industry faces a challenge in achieving a truly circular economy. While many thermoformed plastics are technically recyclable, the infrastructure for collecting, cleaning, and processing used automotive dunnage is often fragmented. Ensuring that recycled materials maintain the necessary structural integrity for protecting heavy engine components during multiple reuse cycles is a persistent technical hurdle that requires ongoing research and development.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Technical Limitations in Wall Thickness Uniformity | -0.5% | Global High-Precision Components | 2025 - 2034 |
| Fragmented Recycling Infrastructure for Industrial Plastics | -0.7% | Global | 2025 - 2030 |
| High Energy Consumption in Manufacturing | -0.4% | Global | 2025 - 2034 |
Automotive Thermoformed Plastics Parts Packaging Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the global automotive thermoformed plastics parts packaging market, covering various material types, packaging formats, and vehicle types. It provides a detailed breakdown of the value chain, from raw material suppliers to end-users in the OEM and aftermarket segments. The report also examines the impact of regulatory frameworks and technological advancements on market dynamics, offering strategic insights for stakeholders to navigate the evolving competitive landscape through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 3.89 Billion |
| Market Forecast in 2034 | USD 6.47 Billion |
| Growth Rate | 5.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Pactiv LLC, Sonoco Products Company, Berry Global Inc., Placon Corporation, Tray-Pak Corp, Sinclair & Rush Inc., D&W Fine Pack, Constantia Flexibles, Formed Solutions, Greiner Packaging, Brentwood Industries, Universal Protective Packaging, Inc. (UPPI), Nefab Group, DS Smith PLC, Klöckner Pentaplast, Pregis LLC, Sabert Corporation |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Automotive Thermoformed Plastics Parts Packaging Market is segmented by material, packaging type, and application to provide a granular view of the industry. Material-wise, Polypropylene (PP) leads the market due to its versatility and resistance to oils and chemicals, which are common in automotive environments. Packaging types such as customized dunnage trays are gaining traction as they are essential for protecting high-value components like transmissions and electronic control units during inter-plant transport. The market is also segmented by end-use, where the OEM segment dominates due to the massive scale of initial vehicle assembly operations, while the aftermarket segment is seeing growth driven by e-commerce and the global distribution of replacement parts.
- By Material: Polypropylene (PP), Polyethylene Terephthalate (PET), High-Density Polyethylene (HDPE), Acrylonitrile Butadiene Styrene (ABS), Polystyrene (PS), Others.
- By Packaging Type: Customized Trays, Clamshells, Totes & Bins, Blister Packs, Shipping Dunnage, Others.
- By Application: Engine & Drivetrain Components, Interior Panels & Trims, Exterior Lighting & Body Parts, Electrical & Electronics, Battery & Power Systems.
- By End-Use: Original Equipment Manufacturers (OEMs), Tier-1 & Tier-2 Suppliers, Aftermarket Retailers.
Regional Highlights
- Asia-Pacific (APAC): Dominates the global market with over 40% share, fueled by the massive automotive hubs in China, Japan, and India. China's lead in EV manufacturing is a primary growth engine for specialized thermoformed packaging.
- North America: A major hub for innovation in heavy-duty thermoformed dunnage. The presence of major automakers like Ford, GM, and Tesla ensures a steady demand for advanced protective packaging solutions.
- Europe: Leading the charge in sustainable and circular packaging initiatives. Germany, France, and Italy are key contributors, focusing on high-quality thermoformed components that meet strict EU environmental standards.
- Latin America: Showing steady growth, particularly in Mexico, which serves as a vital manufacturing base for North American automotive supply chains.
- Middle East and Africa: An emerging market with increasing investments in localized vehicle assembly and a growing demand for cost-effective packaging solutions.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Automotive Thermoformed Plastics Parts Packaging Market. These companies are at the forefront of innovation, focusing on material science, sustainability, and automated manufacturing processes.
- Pactiv LLC
- Sonoco Products Company
- Berry Global Inc.
- Placon Corporation
- Tray-Pak Corp
- Sinclair & Rush Inc.
- D&W Fine Pack
- Constantia Flexibles
- Formed Solutions
- Greiner Packaging
- Brentwood Industries
- Universal Protective Packaging, Inc. (UPPI)
- Nefab Group
- DS Smith PLC
- Klöckner Pentaplast
- Pregis LLC
- Sabert Corporation
- T.O. Plastics
- Plastiform
- VisiPak
Frequently Asked Questions
What is the current market size of the Automotive Thermoformed Plastics Parts Packaging Market?
The market is estimated at USD 4.12 Billion in 2026 and is projected to reach USD 6.47 Billion by 2034, growing at a CAGR of 5.8%.
Which material is most commonly used in automotive thermoformed packaging?
Polypropylene (PP) is the leading material due to its high impact resistance, chemical stability, and cost-effectiveness for both single-use and returnable automotive packaging.
How is the rise of electric vehicles impacting this market?
The shift to EVs is a major growth driver, as it requires specialized, often anti-static and flame-retardant thermoformed trays to protect sensitive battery cells and electronic components during manufacturing and transport.
Which region holds the largest market share?
The Asia-Pacific region holds the largest market share, driven by high vehicle production rates in China, India, and Japan, as well as the rapid expansion of the regional EV supply chain.
What are the key trends in sustainability for this industry?
Key sustainability trends include the use of recycled polymers (PCR), the development of biodegradable thermoformed materials, and the implementation of returnable and reusable dunnage systems to reduce environmental impact.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted