Automotive Telematics Market
Automotive Telematics Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711487 | Published On : November 03, 2026 |
Format : 


 | Author : Ashraf Shehata
Automotive Telematics Market Size
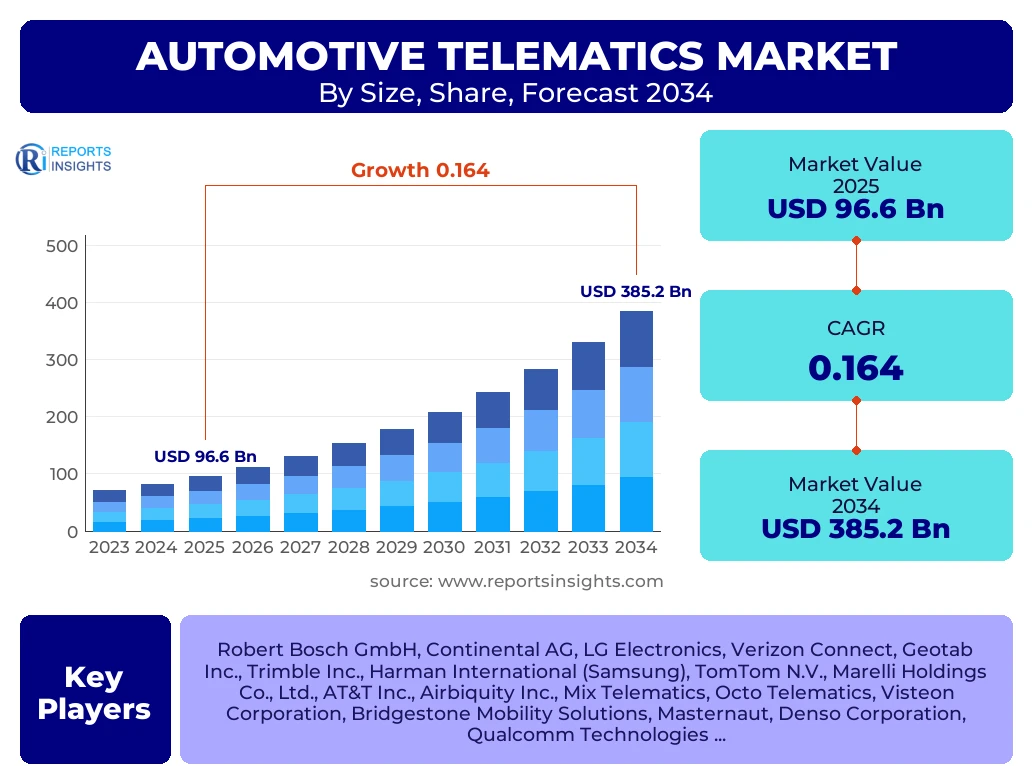
According to Reports Insights Consulting Pvt Ltd, The Automotive Telematics Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 16.4% between 2025 and 2034. The market is estimated at USD 112.5 Billion in 2026 and is projected to reach USD 385.2 Billion by the end of the forecast period in 2034.
Key Automotive Telematics Market Trends & Insights
The global automotive telematics landscape is currently undergoing a radical transformation, fueled by the convergence of high-speed 5G connectivity, advanced sensor technologies, and the rise of software-defined vehicles. Stakeholders are increasingly prioritizing real-time data acquisition to enhance vehicle safety, optimize fleet operations, and provide immersive in-car experiences. The integration of Artificial Intelligence (AI) and Machine Learning (ML) at the edge is enabling predictive maintenance and sophisticated driver behavior analytics, which are becoming standard features in both passenger and commercial segments. Furthermore, the shift toward electric vehicles (EVs) has introduced new requirements for battery management telematics, further broadening the market's technological scope and application range.
- Largest Region: North America remains the largest market due to high penetration of connected car technology and stringent safety regulations.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR, driven by massive automotive production in China and India and increasing digital infrastructure investments.
- Leading Segment by Value: The Fleet Management application segment holds the largest market share as logistics companies seek to maximize fuel efficiency and route optimization.
- Dominant Sales Channel: The OEM (Original Equipment Manufacturer) segment is leading the market, with most new vehicle models now featuring factory-installed telematics units.
Key Takeaways Automotive Telematics Market Size & Forecast
The market trajectory for automotive telematics indicates a robust transition from simple GPS tracking to complex, data-driven ecosystems that support autonomous driving and smart city integration. Forecasts suggest that the proliferation of 5G networks will be the primary catalyst for market expansion, reducing latency for vehicle-to-everything (V2X) communications. Additionally, the growing consumer demand for advanced infotainment and high-level safety features, such as automatic crash notification and emergency calling systems, is compelling manufacturers to embed telematics hardware across all vehicle price points. The market is also seeing a significant rise in usage-based insurance (UBI) models, which rely heavily on accurate telematics data to assess risk and reward safe driving behavior.
- The global market value is expected to more than triple by 2034, reflecting the essential nature of connectivity in modern transport.
- Strategic partnerships between automotive OEMs and telecommunications providers are becoming the standard business model for service delivery.
- Europe is a key pioneer in safety-mandated telematics, particularly following the implementation of the eCall initiative.
- Technological advancements in cybersecurity are critical, as the industry works to protect vehicle data from sophisticated cyber threats.
- Cloud-based telematics platforms are gaining traction over on-premise solutions due to their scalability and lower capital expenditure requirements.
Automotive Telematics Market Drivers Analysis
The primary driver for the automotive telematics market is the global shift toward enhanced road safety and the implementation of government mandates. Regulatory bodies worldwide are increasingly requiring features like electronic logging devices (ELDs) for commercial vehicles and automated emergency response systems for passenger cars. This regulatory push ensures a consistent demand for telematics hardware and integrated software solutions across diverse geographical markets. Furthermore, the commercial logistics sector's need for operational transparency and cost reduction is pushing the adoption of sophisticated fleet management systems that monitor fuel consumption, idle time, and engine health.
Another significant driver is the rapid evolution of 5G and V2X technologies. As telecommunications infrastructure matures, the ability for vehicles to communicate with each other and with roadside infrastructure becomes feasible, leading to reduced traffic congestion and improved safety. This connectivity is the backbone of the future autonomous driving ecosystem. Moreover, consumer preferences are shifting toward "connected lifestyles," where the vehicle is seen as an extension of the home or office, necessitating high-speed internet, real-time navigation, and seamless integration with personal mobile devices.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of 5G Infrastructure | +4.2% | Global (Majorly USA, China, South Korea) | 2025 - 2034 |
| Government Safety Mandates (eCall, ELD) | +3.8% | European Union, North America | 2025 - 2030 |
| Rising Demand for Fleet Optimization | +3.5% | Asia-Pacific, Latin America | 2025 - 2034 |
| Integration of AI for Predictive Maintenance | +2.9% | Germany, Japan, USA | 2026 - 2034 |
Automotive Telematics Market Restraints Analysis
Despite the optimistic growth projections, the automotive telematics market faces significant restraints, most notably concerns regarding data privacy and cybersecurity. As vehicles become more connected, they also become more vulnerable to hacking, which can lead to the unauthorized access of personal location data or, more dangerously, the hijacking of vehicle control systems. Consumers and advocacy groups are increasingly vocal about how data is collected, stored, and shared, leading to potential regulatory hurdles that could slow down the implementation of certain data-intensive services.
Cost remains a significant barrier for the aftermarket segment and for mass-market adoption in developing economies. The high initial investment required for sophisticated telematics hardware, combined with recurring subscription fees for connectivity services, can deter budget-conscious consumers and small-scale fleet operators. Additionally, the lack of standardized protocols across different manufacturers often leads to interoperability issues, complicating the service landscape for third-party providers and limiting the potential for a truly universal V2X ecosystem.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity Threats and Data Privacy Concerns | -2.1% | USA, European Union | Ongoing |
| High Initial Cost of Hardware & Integration | -1.5% | India, Brazil, Southeast Asia | 2025 - 2029 |
| Lack of Universal Communication Standards | -1.2% | Global | 2025 - 2030 |
Automotive Telematics Market Opportunities Analysis
The burgeoning market for Electric Vehicles (EVs) represents one of the most lucrative opportunities for the telematics industry. EVs require specialized telematics solutions to monitor battery state-of-health (SoH), optimize charging cycles, and provide real-time information on the nearest charging stations. As governments worldwide provide subsidies for EV adoption, telematics providers who can offer integrated energy management and range-prediction tools will gain a significant competitive advantage. This niche is expected to grow exponentially as the global fleet transitions away from internal combustion engines.
Furthermore, the rise of the "data-as-a-service" (DaaS) model within the automotive sector presents a significant opportunity. Telematics providers can monetize the vast amounts of data collected from vehicles by selling anonymized insights to urban planners, insurance companies, and advertisers. Usage-Based Insurance (UBI) is a prime example of this, where driver behavior data is used to tailor insurance premiums. As the demand for personalized services grows, the ability to leverage telematics data for targeted marketing and enhanced user experiences will drive new revenue streams beyond traditional hardware sales.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Electric Vehicle Battery & Range Management | +5.1% | China, Germany, Norway | 2025 - 2034 |
| Usage-Based Insurance (UBI) Expansion | +3.9% | UK, Italy, USA | 2026 - 2034 |
| Smart City and Traffic Management Integration | +2.7% | Singapore, UAE, Japan | 2027 - 2034 |
Automotive Telematics Market Challenges Impact Analysis
A major challenge facing the automotive telematics market is the complexity of global regulatory compliance. Different regions have varying laws regarding data sovereignty, emergency response protocols, and wireless spectrum usage. For global OEMs, this means that telematics solutions must be heavily customized for each market, increasing R&D costs and complicating supply chain management. Navigating the legal landscape of data ownership—whether it belongs to the vehicle owner, the OEM, or the service provider—remains a contentious and unresolved issue in many jurisdictions.
The industry also faces technical challenges related to hardware longevity and backward compatibility. Automotive lifecycles are significantly longer than consumer electronics lifecycles. A telematics unit installed today must remain functional and secure for ten to fifteen years, even as the underlying communication networks (like 3G or 4G) are phased out. This "future-proofing" requires significant engineering foresight and can lead to hardware becoming obsolete long before the vehicle reaches the end of its useful life, necessitating expensive retrofits or software updates.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fragmented Regulatory and Data Privacy Laws | -1.8% | Global (Cross-border operations) | 2025 - 2034 |
| Long Vehicle Lifecycles vs. Rapid Tech Obsolescence | -1.4% | Global | Ongoing |
| Spectrum Allocation and Connectivity Dead Zones | -0.9% | Rural North America, Africa, Australia | 2025 - 2030 |
Automotive Telematics Market - Updated Report Scope
The scope of this report encompasses a thorough examination of the automotive telematics ecosystem, covering hardware, software, and service components across various vehicle types and sales channels. It provides a granular analysis of application areas such as safety and security, infotainment, fleet management, and remote diagnostics. The report highlights the strategic movements of key market participants, the impact of emerging technologies like 5G and AI, and the shifting regulatory landscape across major global regions to provide a comprehensive forecast of market dynamics through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 96.6 Billion |
| Market Forecast in 2034 | USD 385.2 Billion |
| Growth Rate | 16.4% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Robert Bosch GmbH, Continental AG, LG Electronics, Verizon Connect, Geotab Inc., Trimble Inc., Harman International (Samsung), TomTom N.V., Marelli Holdings Co., Ltd., AT&T Inc., Airbiquity Inc., Mix Telematics, Octo Telematics, Visteon Corporation, Bridgestone Mobility Solutions, Masternaut, Denso Corporation, Qualcomm Technologies, Sierra Wireless |
| Regions Covered | North America (US, Canada, Mexico), Europe (Germany, UK, France, Italy, Spain, Rest of Europe), Asia Pacific (China, Japan, India, South Korea, Australia, Rest of APAC), Latin America (Brazil, Argentina, Rest of LATAM), Middle East, and Africa (GCC, South Africa, Rest of MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The automotive telematics market is segmented to reflect the diverse technological implementations and end-user requirements. The Connectivity Type segmentation highlights the shift from tethered (smartphone-dependent) systems to fully embedded modules that ensure constant connectivity. In terms of Application, fleet management remains the volume leader, while safety and security applications are seeing rapid growth due to regulatory mandates. The Vehicle Type segment is dominated by passenger cars in terms of unit volume, but commercial vehicles represent a higher value per unit due to the complexity of fleet logistics software.
- By Connectivity Solution:
- Embedded Telematics
- Tethered Telematics
- Integrated Telematics
- By Sales Channel:
- OEM (Factory Fitted)
- Aftermarket (Retrofitted)
- By Vehicle Type:
- Passenger Vehicles
- Light Commercial Vehicles (LCVs)
- Heavy Commercial Vehicles (HCVs)
- By Application:
- Fleet/Asset Management
- Automatic Crash Notification (ACN)
- Emergency Call (eCall)
- Navigation and Location-Based Services
- Infotainment and Connectivity
- Insurance Telematics (UBI)
- Remote Diagnostics and Predictive Maintenance
Regional Highlights
- North America: The largest market globally, characterized by high consumer awareness, advanced 5G rollout, and a strong presence of key tech giants like Verizon and AT&T. The US leads in the adoption of fleet management and insurance telematics.
- Europe: A dominant player in safety-centric telematics. The eCall mandate has made telematics a standard feature in almost all new vehicles. Germany and the UK are hubs for innovation in V2X and autonomous driving research.
- Asia-Pacific: The fastest-growing region, driven by the massive automotive industries in China and Japan. Rapid urbanization and government initiatives for smart cities in India and Southeast Asia are accelerating the deployment of telematics infrastructure.
- Latin America: Showing steady growth, particularly in Brazil and Mexico, where telematics is primarily used for vehicle tracking and stolen vehicle recovery (SVR) due to security concerns.
- Middle East & Africa: Growth is concentrated in the GCC countries, where investments in smart infrastructure and logistics are driving the demand for high-end fleet management solutions.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Automotive Telematics Market.
- Robert Bosch GmbH
- Continental AG
- LG Electronics
- Verizon Connect
- Geotab Inc.
- Trimble Inc.
- Harman International (Samsung Electronics)
- TomTom N.V.
- Marelli Holdings Co., Ltd.
- AT&T Inc.
- Airbiquity Inc.
- Mix Telematics
- Octo Telematics
- Visteon Corporation
- Bridgestone Mobility Solutions (Webfleet)
- Masternaut (Michelin Group)
- Denso Corporation
- Qualcomm Technologies, Inc.
- Sierra Wireless
- Aptiv PLC
Frequently Asked Questions
What is the current and projected size of the Automotive Telematics Market?
The market is estimated at USD 112.5 Billion in 2026 and is projected to reach approximately USD 385.2 Billion by 2034, growing at a CAGR of 16.4%.
Which region is expected to grow the fastest in the Automotive Telematics sector?
The Asia-Pacific region is expected to be the fastest-growing market due to increasing vehicle production, rapid digital transformation, and government support for connected vehicle technologies in China and India.
How is 5G technology impacting the Automotive Telematics market?
5G provides the high-speed, low-latency connectivity required for real-time V2X communication, advanced autonomous driving functions, and high-definition infotainment services, acting as a major growth catalyst.
What are the main applications of telematics in commercial vehicles?
Key applications include fleet management (tracking and fuel optimization), remote diagnostics, electronic logging for regulatory compliance (ELD), and driver behavior monitoring to improve safety and reduce insurance costs.
What are the biggest challenges facing the telematics industry today?
The most significant challenges include cybersecurity vulnerabilities, the high cost of implementing advanced hardware, and the complex, fragmented regulatory environment regarding data privacy across different countries.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
