Automotive Shielding Market
Automotive Shielding Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711613 | Published On : November 08, 2026 |
Format : 


 | Author : Ashraf Shehata
Automotive Shielding Market Size
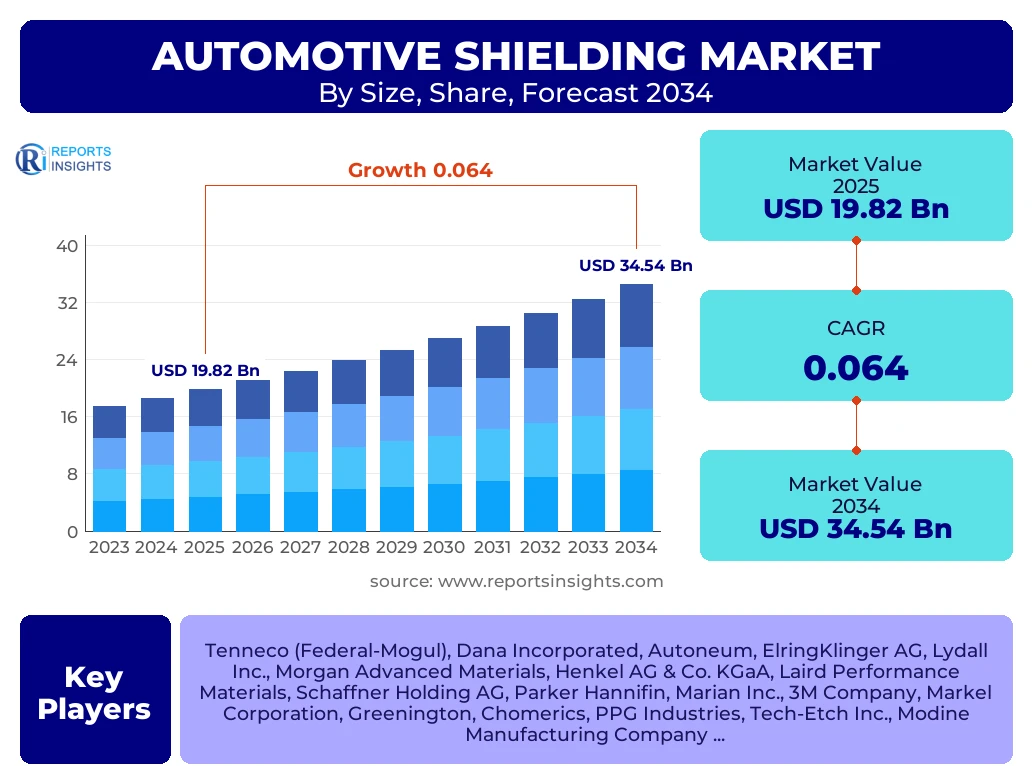
According to Reports Insights Consulting Pvt Ltd, The Automotive Shielding Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.4% between 2025 and 2034. The market is estimated at USD 21.09 Billion in 2026 and is projected to reach USD 34.54 Billion by the end of the forecast period in 2034.
Key Automotive Shielding Market Trends & Insights
The global automotive landscape is undergoing a radical transformation, moving from traditional internal combustion engines to sophisticated electrified and autonomous systems. This shift has fundamentally altered the requirements for automotive shielding, transitioning from a primary focus on thermal management to a sophisticated dual-requirement for both thermal and electromagnetic interference (EMI) protection. As vehicles become increasingly reliant on high-frequency electronic control units (ECUs), radar, LiDAR, and high-voltage battery systems, the demand for advanced shielding materials that offer lightweight properties and superior conductivity is surging. Market participants are increasingly investing in conductive plastics and multi-layer metallic foils to meet stringent electromagnetic compatibility (EMC) standards while adhering to global fuel efficiency and weight reduction mandates.
- Asia-Pacific stands as the largest and most rapidly expanding region, driven by massive vehicle production volumes in China and India and the aggressive domestic adoption of electric vehicles.
- The Electromagnetic Interference (EMI) Shielding segment is the fastest-growing category, outpacing traditional heat shields due to the proliferation of high-speed data transmission and ADAS sensors in modern vehicle architectures.
- Passenger Cars remain the largest segment by vehicle type, although the commercial vehicle segment is seeing significant growth due to the electrification of long-haul logistics.
- Aluminum continues to be the dominant material choice for heat shielding due to its excellent thermal conductivity and favorable cost-to-weight ratio, while copper and nickel-plated materials lead in high-end EMI applications.
Key Takeaways Automotive Shielding Market Size & Forecast
The trajectory of the automotive shielding market is inextricably linked to the "ACES" (Autonomous, Connected, Electric, and Shared) megatrend. Stakeholders are shifting focus toward integrated shielding solutions that can manage the heat generated by high-density battery packs while simultaneously protecting sensitive telematics systems from signal degradation. The forecast indicates that as the density of electronic components per vehicle increases, the value of the shielding content per vehicle is expected to rise by nearly 40% over the next decade. This growth is further supported by governmental regulations regarding vehicle safety and emission controls, which necessitate more complex exhaust systems in hybrid vehicles and robust thermal barriers in battery electric vehicles (BEVs).
- The Electric Vehicle (EV) segment is the primary catalyst for market expansion, requiring specialized shielding for high-voltage cables, battery enclosures, and power inverters.
- China is the leading country globally, accounting for a significant share of the total market value due to its massive manufacturing ecosystem and government-backed EV initiatives.
- Development of 5G-enabled vehicle-to-everything (V2X) communication is creating a new demand frontier for high-frequency EMI shielding solutions that operate in the millimeter-wave spectrum.
- The industry is witnessing a consolidation trend, with Tier 1 suppliers acquiring specialized material science firms to develop proprietary, high-performance composite shields.
Automotive Shielding Market Drivers Analysis
The growth of the automotive shielding market is fueled by the critical need for operational reliability in modern vehicles. As electronic architectures become more congested, the risk of signal cross-talk and thermal runaway increases, making robust shielding a non-negotiable safety requirement. Furthermore, the global push for carbon neutrality is forcing OEMs to optimize thermal management in engines and batteries to maximize efficiency, thereby driving the adoption of advanced heat shields. The integration of high-performance computing platforms for autonomous driving also necessitates specialized EMI protection to ensure the integrity of life-critical sensor data.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rapid Electrification of Powertrains | +2.8% | Global / Europe & China | 2025–2034 |
| Proliferation of ADAS and Autonomous Sensors | +1.5% | North America / Japan | 2026–2032 |
| Strict Government Emission Regulations | +1.2% | European Union / USA | 2025–2030 |
| Demand for Lightweight Material Components | +0.9% | Global | 2025–2034 |
Automotive Shielding Market Restraints Analysis
Despite strong demand, the market faces significant headwinds from the volatility of raw material prices, particularly aluminum, copper, and specialized resins. Additionally, the increasing complexity of vehicle designs presents manufacturing challenges, as shields must be custom-contoured to fit into tighter engine bays or integrated within battery modules. High R&D costs for developing next-generation composite materials can also serve as a barrier for smaller players in the market, potentially slowing the pace of innovation in low-margin vehicle segments.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fluctuation in Raw Material Prices (Al, Cu) | -1.1% | Global | 2025–2034 |
| Design Complexity and Space Constraints | -0.7% | Germany / Japan | 2025–2029 |
| High Cost of Advanced Composite Shields | -0.5% | Developing Economies | 2026–2031 |
Automotive Shielding Market Opportunities Analysis
The transition toward the software-defined vehicle (SDV) provides a lucrative opportunity for the development of smart shielding solutions. These include integrated shields that also act as thermal sensors or EMI-absorbing materials that can be 3D printed directly onto electronic housings. Moreover, the growth of the aftermarket segment for vehicle customization and the retrofitting of older fleets with telematics systems offer untapped revenue streams for shielding manufacturers. The emergence of solid-state batteries also presents a future opportunity for specialized thermal containment systems that are thinner and more efficient than current technologies.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of 5G and V2X Communication | +1.8% | South Korea / USA | 2027–2034 |
| Advancements in Nanotechnology for Shielding | +1.3% | Germany / Japan | 2026–2034 |
| Expansion of the EV Charging Infrastructure | +0.8% | Global | 2025–2034 |
Automotive Shielding Market Challenges Impact Analysis
Manufacturers are challenged by the need to balance high shielding effectiveness with weight reduction goals. As OEMs strive to increase the range of EVs, every gram of weight matters, forcing shielding suppliers to move away from heavy metallic sheets toward expensive ultra-thin foils or conductive polymers. Additionally, the rapid pace of electronic innovation means that shielding requirements are constantly evolving, requiring shorter product development cycles and highly flexible manufacturing processes to avoid obsolescence.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Balancing Shielding Efficiency with Weight | -0.9% | Global | 2025–2034 |
| Short Product Lifecycles of Electronics | -0.6% | USA / China | 2025–2030 |
| Stringent Global EMC Testing Standards | -0.4% | Europe / North America | 2026–2034 |
Automotive Shielding Market - Updated Report Scope
This report provides a granular analysis of the global automotive shielding market, covering both thermal and electromagnetic protection across various vehicle platforms. It encompasses a deep dive into material science advancements, regulatory influences, and the impact of the global semiconductor supply chain on electronic shielding demand. The scope includes historical data from 2020 to 2024, providing a solid baseline for the forecast period extending to 2034, with a specific focus on the intersection of electrification and autonomous technologies.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 19.82 Billion |
| Market Forecast in 2034 | USD 34.54 Billion |
| Growth Rate | 6.4% CAGR |
| Number of Pages | 274 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Tenneco (Federal-Mogul), Dana Incorporated, Autoneum, ElringKlinger AG, Lydall Inc., Morgan Advanced Materials, Henkel AG & Co. KGaA, Laird Performance Materials, Schaffner Holding AG, Parker Hannifin, Marian Inc., 3M Company, Markel Corporation, Greenington, Chomerics, PPG Industries, Tech-Etch Inc., Modine Manufacturing Company, Kitagawa Industries, systems & components Corp. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The automotive shielding market is segmented primarily by the type of protection required, the material used, and the propulsion system of the vehicle. Heat shielding remains a critical segment, particularly in ICE and hybrid vehicles, where high temperatures from exhaust systems and turbochargers must be managed to protect sensitive components and passenger comfort. However, EMI shielding is experiencing explosive growth due to the integration of high-performance computing for autonomous driving and the high-frequency switching noise inherent in EV power electronics. Material-wise, the industry is moving from simple stamped metal components to complex multi-layer insulators and conductive textiles that offer superior performance in smaller footprints.
- Heat Shielding: Divided into Exhaust System Shields, Turbocharger Shields, Engine Compartment Shields, and Underbody Shields.
- EMI Shielding: Covering Radar/LiDAR units, Infotainment systems, Power Inverters, Battery Management Systems (BMS), and Wire Harnesses.
- By Material: Metallic (including Aluminum, Stainless Steel, and Copper) and Non-Metallic (including Conductive Polymers, Fabrics, and specialized Foams).
- By Propulsion Type: Internal Combustion Engine (ICE), Battery Electric Vehicle (BEV), Plug-in Hybrid Electric Vehicle (PHEV), and Hybrid Electric Vehicle (HEV).
- By Vehicle Type: Passenger Cars (Sedans, SUVs, Hatchbacks) and Commercial Vehicles (LCV, HCV).
Regional Highlights
- Asia-Pacific (APAC) is the dominant market, led by China, which is the world's largest producer of both passenger vehicles and electric batteries. The region is characterized by high investment in local manufacturing and a rapid shift toward high-tech automotive components.
- North America is a key hub for innovation, particularly in the development of autonomous driving technologies. The presence of leading tech-centric OEMs in the US drives the demand for high-end EMI shielding solutions for AI-driven vehicle systems.
- Europe maintains a strong focus on high-efficiency heat shielding and lightweighting, driven by the most stringent carbon emission targets globally (Euro 7 standards). Germany and France are at the forefront of integrating shielding into premium and luxury EV segments.
- Latin America and the Middle East & Africa represent emerging markets with steady growth, primarily focused on traditional heat shielding as vehicle manufacturing bases expand in countries like Mexico, Brazil, and Morocco.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Automotive Shielding Market.- Tenneco Inc. (Federal-Mogul)
- Dana Incorporated
- Autoneum Holding AG
- ElringKlinger AG
- Lydall Inc.
- Morgan Advanced Materials
- Henkel AG & Co. KGaA
- Laird Performance Materials (DuPont)
- Schaffner Holding AG
- Parker Hannifin Corp
- 3M Company
- Marian Inc.
- Tech-Etch Inc.
- PPG Industries
- Chomerics (Parker)
- Modine Manufacturing Company
- Kitagawa Industries Co., Ltd.
- Markel Corporation
- Crenlo Engineered Enclosures
- ERMECH
Frequently Asked Questions
What is the current market size of the Automotive Shielding industry?
The global automotive shielding market is estimated at USD 19.82 Billion in 2025 and is expected to reach USD 34.54 Billion by 2034, growing at a CAGR of 6.4%.
Which segment is the fastest growing in the automotive shielding market?
The EMI shielding segment is the fastest-growing category, driven by the proliferation of electronic components, ADAS sensors, and the transition to electric vehicle architectures.
Why is Asia-Pacific the leading region for automotive shielding?
Asia-Pacific leads due to its massive vehicle production capacity, the presence of major battery manufacturers in China and South Korea, and the rapid domestic adoption of electric vehicles.
How does the shift to electric vehicles impact shielding requirements?
EVs shift the focus from exhaust heat shielding to EMI shielding and battery thermal management, requiring materials that can block electromagnetic noise from high-voltage components while managing battery heat.
What materials are most commonly used in automotive shielding?
Aluminum is the most common for heat shields due to cost and weight, while copper, nickel, and conductive polymers are increasingly used for high-performance EMI shielding in electronic modules.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
