Automotive Electronic Brake System Market
Automotive Electronic Brake System Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711915 | Published On : November 21, 2026 |
Format : 


 | Author : Ashraf Shehata
Automotive Electronic Brake System Market Size
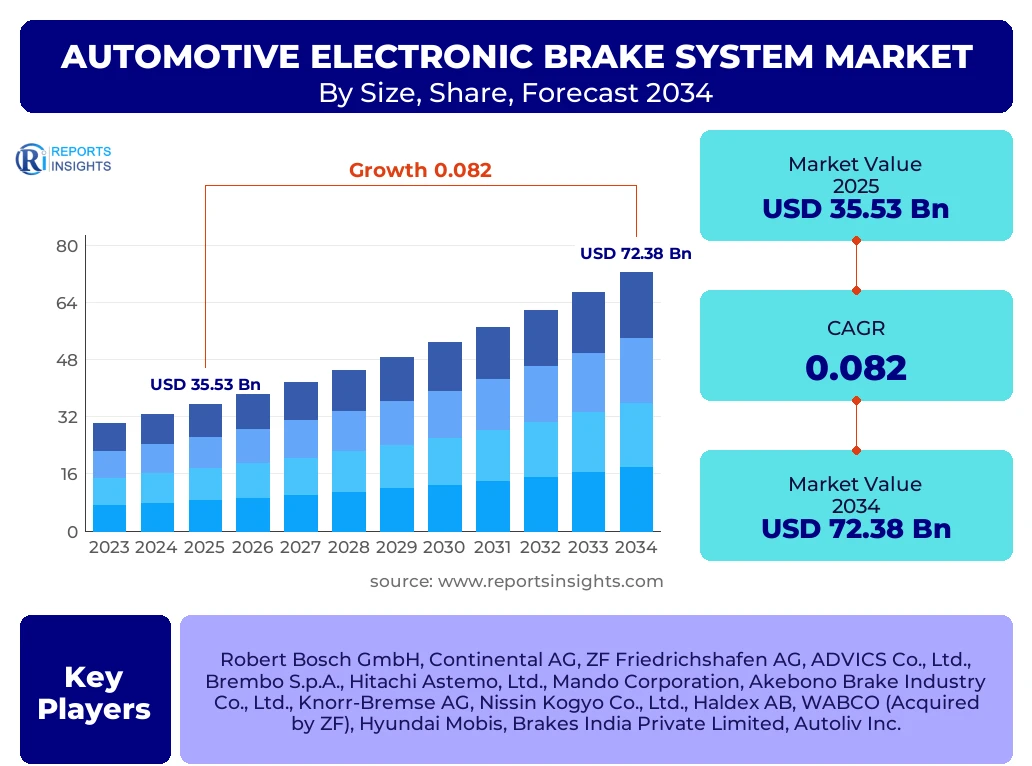
According to Reports Insights Consulting Pvt Ltd, The Automotive Electronic Brake System Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.2% between 2025 and 2034. The market is estimated at USD 38.45 Billion in 2026 and is projected to reach USD 72.38 Billion by the end of the forecast period in 2034.
Key Automotive Electronic Brake System Market Trends & Insights
The global landscape for automotive safety systems is undergoing a paradigm shift, transitioning from traditional mechanical linkages to sophisticated electronic architectures. Current market intelligence reveals that the integration of Advanced Driver Assistance Systems (ADAS) and the aggressive push toward vehicle electrification are the primary catalysts for this evolution. Stakeholders are increasingly prioritizing Brake-by-Wire (BbW) technology, which eliminates the physical connection between the brake pedal and the calipers, offering weight reduction, improved fuel efficiency, and seamless integration with autonomous driving software. Furthermore, the convergence of electronic stability control and regenerative braking in electric vehicles is redefining the competitive benchmarking metrics for tier-1 suppliers.
- Largest Region: Asia-Pacific remains the dominant force, accounting for over 45% of the global market share, driven by massive production volumes in China and India.
- Fastest Growing Region: North America is poised for the most rapid acceleration due to stringent updated safety mandates and high adoption rates of premium electric vehicles.
- Largest Segment by Share: The Anti-lock Braking System (ABS) segment continues to hold the highest market share as it has become a baseline standard across all vehicle categories globally.
- Emerging Technology: Electronic Stability Control (ESC) and Autonomous Emergency Braking (AEB) are seeing the highest year-on-year growth rates in the mid-range vehicle segment.
Key Takeaways Automotive Electronic Brake System Market Size & Forecast
The market trajectory for electronic braking systems is fundamentally tied to the global legislative environment and the consumer shift toward "software-defined vehicles." Analysis suggests that by 2030, nearly 85% of all new vehicles manufactured will be equipped with some form of electronic braking enhancement beyond basic ABS. This transition is not merely a safety upgrade but a foundational requirement for the next generation of mobility, including Level 3 and Level 4 autonomous driving. The synchronization of braking systems with sensor suites like LiDAR and Radar is creating new revenue streams for electronic control unit (ECU) manufacturers and software developers specializing in functional safety.
- Leading Country: China is the global hub for both production and consumption, supported by a robust ecosystem for electric vehicle components.
- Investment Focus: Major players are pivoting R&D budgets toward electro-hydraulic and electro-mechanical braking systems to support the shift away from vacuum-based systems.
- Strategic Outlook: The transition to 48V vehicle architectures is enabling more powerful electronic actuators, facilitating faster response times in emergency braking scenarios.
- Supply Chain Dynamics: Diversification of semiconductor sourcing is becoming a critical strategic priority for brake system integrators to avoid disruptions similar to those seen in the early 2020s.
Automotive Electronic Brake System Market Drivers Analysis
The primary driver for the Automotive Electronic Brake System market is the global escalation of safety regulations. Governments in Europe, North America, and parts of Asia have implemented mandates requiring Electronic Stability Control and Autonomous Emergency Braking in all new passenger vehicles. These regulations are designed to reduce road fatalities and are pushing manufacturers to adopt electronic systems that can react faster than human intervention. As these mandates expand to include heavy commercial vehicles and entry-level cars in developing nations, the volume demand for electronic components is surging.
Another significant driver is the rapid electrification of the global automotive fleet. Electric vehicles (EVs) require specialized braking systems that can handle regenerative braking—recovering kinetic energy to recharge the battery. Traditional hydraulic systems are less efficient at managing this transition between friction braking and energy recovery. Consequently, OEMs are turning to electronic brake systems that offer precise control over this blend, enhancing the driving range and efficiency of EVs. This technological necessity ensures that as EV adoption grows, the electronic brake market grows in tandem.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global Safety Mandates (AEB/ESC) | +3.2% | Global (EU Focus) | 2025 - 2034 |
| Electric Vehicle (EV) Penetration | +2.8% | China, USA, Germany | 2026 - 2034 |
| Consumer Demand for ADAS Features | +1.5% | North America, Japan | 2025 - 2030 |
| Advancements in Brake-by-Wire Tech | +0.7% | South Korea, Germany | 2028 - 2034 |
Automotive Electronic Brake System Market Restraints Analysis
High development and integration costs represent a significant restraint, particularly for the entry-level vehicle segment in price-sensitive markets. The transition from traditional hydraulic systems to sophisticated electronic architectures involves substantial R&D investment and expensive components like high-speed sensors and advanced ECUs. For manufacturers operating in emerging economies, balancing the cost of these safety features with the need to keep vehicle prices affordable for the mass market remains a complex challenge that can slow down the adoption of premium electronic braking technologies.
Additionally, the complexity of cybersecurity in connected vehicles poses a potential threat to market expansion. Electronic brake systems are increasingly integrated into the vehicle's central computer and cloud-based diagnostics. Any vulnerability in the software could lead to catastrophic failures or unauthorized remote interference. Ensuring the functional safety and digital security of these systems requires continuous updates and rigorous testing, which adds to the operational overhead and can deter consumers who are wary of the risks associated with fully electronic vehicle control systems.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High System Complexity and Cost | -1.2% | India, Brazil, SE Asia | 2025 - 2029 |
| Cybersecurity and Software Vulnerabilities | -0.5% | Global | 2026 - 2034 |
Automotive Electronic Brake System Market Opportunities Analysis
The emergence of Level 4 and Level 5 autonomous vehicles presents a massive opportunity for the electronic braking sector. Autonomous systems require redundant braking architectures where two independent electronic systems can bring the vehicle to a safe stop in the event of a primary system failure. This necessity for redundancy effectively doubles the demand for certain electronic components per vehicle. As pilot programs for robotaxis and autonomous trucking expand in the U.S. and China, the demand for these specialized, high-reliability electronic brake systems is expected to skyrocket.
Furthermore, the aftermarket for safety upgrades and the refurbishment of aging fleets in developed nations offers a secondary growth avenue. While the majority of electronic brake systems are installed at the OEM level, there is a growing niche for upgrading commercial vehicle fleets with advanced electronic control units to comply with new safety standards or to reduce insurance premiums. This "safety-as-a-service" model, combined with remote diagnostics and predictive maintenance for braking systems, allows manufacturers to establish long-term service relationships with fleet operators.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Autonomous Driving Redundancy Systems | +2.4% | USA, China | 2027 - 2034 |
| Predictive Maintenance & Fleet Services | +1.1% | Europe | 2026 - 2032 |
| Lightweighting for Fuel Efficiency | +0.6% | Japan, Germany | 2025 - 2034 |
Automotive Electronic Brake System Market Challenges Impact Analysis
Supply chain volatility remains a persistent challenge for the automotive electronics industry. The reliance on specialized semiconductors and rare-earth minerals for actuators makes the market vulnerable to geopolitical tensions and trade restrictions. A shortage in high-performance microcontrollers can lead to production delays at major OEM plants, as seen in recent years. Manufacturers are currently forced to maintain higher inventory levels and seek multi-source procurement strategies, which can strain profit margins and complicate long-term pricing agreements.
Technological standardization is another significant hurdle. Currently, different OEMs and Tier-1 suppliers use proprietary protocols and hardware designs for their electronic braking architectures. This lack of standardization complicates the integration process for vehicle platforms that are intended for global sale. Achieving a unified standard for communication protocols between the brake system, the engine control unit, and the ADAS suite is essential for reducing costs and improving the overall reliability of electronic vehicle safety systems across the industry.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Semiconductor Supply Instability | -1.8% | Global | 2025 - 2027 |
| Interoperability and Standardization Issues | -0.7% | USA, EU | 2026 - 2030 |
Automotive Electronic Brake System Market - Updated Report Scope
The scope of this research encompasses the global automotive electronic brake system industry, analyzing the technological transition from traditional hydraulic systems to advanced electronic control systems across various vehicle categories. The report provides a deep dive into the value chain, from component manufacturers producing sensors and actuators to the integration services provided by Tier-1 suppliers to global OEMs. It covers the deployment of these systems in internal combustion engine (ICE) vehicles, hybrid electric vehicles (HEVs), and battery electric vehicles (BEVs), with a specific focus on the regulatory tailwinds driving adoption in major economic zones.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 35.53 Billion |
| Market Forecast in 2034 | USD 72.38 Billion |
| Growth Rate | 8.2% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, ADVICS Co., Ltd., Brembo S.p.A., Hitachi Astemo, Ltd., Mando Corporation, Akebono Brake Industry Co., Ltd., Knorr-Bremse AG, Nissin Kogyo Co., Ltd., Haldex AB, WABCO (Acquired by ZF), Hyundai Mobis, Brakes India Private Limited, Autoliv Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented primarily by technology and vehicle application to reflect the differing requirements of consumer and commercial transport. The technology segment is currently dominated by Anti-lock Braking Systems (ABS), which have become ubiquitous due to their proven ability to prevent wheel lock during sudden braking. However, the Electronic Stability Control (ESC) segment is expanding rapidly as it incorporates ABS functionality with lateral stability controls, making it a mandatory requirement in many regions. The components segment is seeing a value shift toward Electronic Control Units (ECUs) and high-fidelity sensors as software complexity increases.
- By Technology:
- Anti-lock Braking System (ABS)
- Electronic Stability Control (ESC)
- Electronic Brakeforce Distribution (EBD)
- Traction Control System (TCS)
- Autonomous Emergency Braking (AEB)
- By Component:
- Electronic Control Units (ECUs)
- Sensors (Wheel Speed, Yaw Rate, Pressure)
- Actuators and Modulators
- Electronic Brake Pedals
- By Vehicle Type:
- Passenger Cars (Sedans, SUVs, Hatchbacks)
- Light Commercial Vehicles (Vans, Pickups)
- Heavy Commercial Vehicles (Trucks, Buses)
- By Propulsion:
- Internal Combustion Engine (ICE)
- Battery Electric Vehicles (BEV)
- Plug-in Hybrid Electric Vehicles (PHEV)
Regional Highlights
- Asia-Pacific: The undisputed leader in terms of volume and market value. China’s status as a global automotive manufacturing powerhouse, combined with India's increasing safety regulations (such as mandatory ABS for motorcycles and passenger cars), drives significant demand. The presence of major electronic components manufacturers in Japan and South Korea further strengthens this region's position.
- Europe: The pioneer in safety regulation adoption. The European Commission’s General Safety Regulation (GSR) mandates features like AEB across various vehicle categories, ensuring a high penetration rate of premium electronic brake systems. The region is also at the forefront of Brake-by-Wire development led by German automotive giants.
- North America: This region is characterized by a high demand for advanced safety features in SUVs and light trucks. The rapid growth of the electric vehicle market, led by both domestic and international manufacturers in the U.S., is a major driver for the adoption of integrated electronic braking and regenerative systems.
- Latin America & MEA: Emerging markets with significant growth potential. As vehicle ownership increases and local governments slowly align with global safety standards, these regions are transitioning from basic mechanical systems to electronic braking, primarily in the passenger car segment.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Automotive Electronic Brake System Market.- Robert Bosch GmbH
- Continental AG
- ZF Friedrichshafen AG
- ADVICS Co., Ltd.
- Brembo S.p.A.
- Hitachi Astemo, Ltd.
- Mando Corporation
- Akebono Brake Industry Co., Ltd.
- Knorr-Bremse AG
- Nissin Kogyo Co., Ltd.
- Haldex AB
- Hyundai Mobis
- Brakes India Private Limited
- Autoliv Inc.
- Wilwood Engineering, Inc.
- Bendix Commercial Vehicle Systems LLC
Frequently Asked Questions
What is the current size of the global Automotive Electronic Brake System Market?
The market is estimated to be valued at USD 38.45 Billion in 2026, with a projected growth path reaching USD 72.38 Billion by 2034.
What are the main drivers for the growth of electronic braking systems?
The primary drivers include increasingly strict international safety mandates for ABS and ESC, the global rise in electric vehicle production, and the integration of ADAS technologies requiring automated braking responses.
Which technology segment holds the largest market share?
The Anti-lock Braking System (ABS) currently holds the largest share due to its status as a mandatory safety feature in most global markets, though Electronic Stability Control (ESC) is growing at a faster rate.
How does vehicle electrification impact this market?
Electrification requires sophisticated electronic braking systems to manage the blending of friction braking and regenerative energy recovery, making electronic brakes a necessity for maximizing EV range and performance.
What are the key challenges facing manufacturers in this space?
Manufacturers face challenges such as high R&D costs, semiconductor supply chain instability, and the need for rigorous cybersecurity protocols to protect software-defined braking systems from digital threats.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
