Automotive Data Management Market
Automotive Data Management Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711815 | Published On : November 17, 2026 |
Format : 


 | Author : Ashraf Shehata
Automotive Data Management Market Size
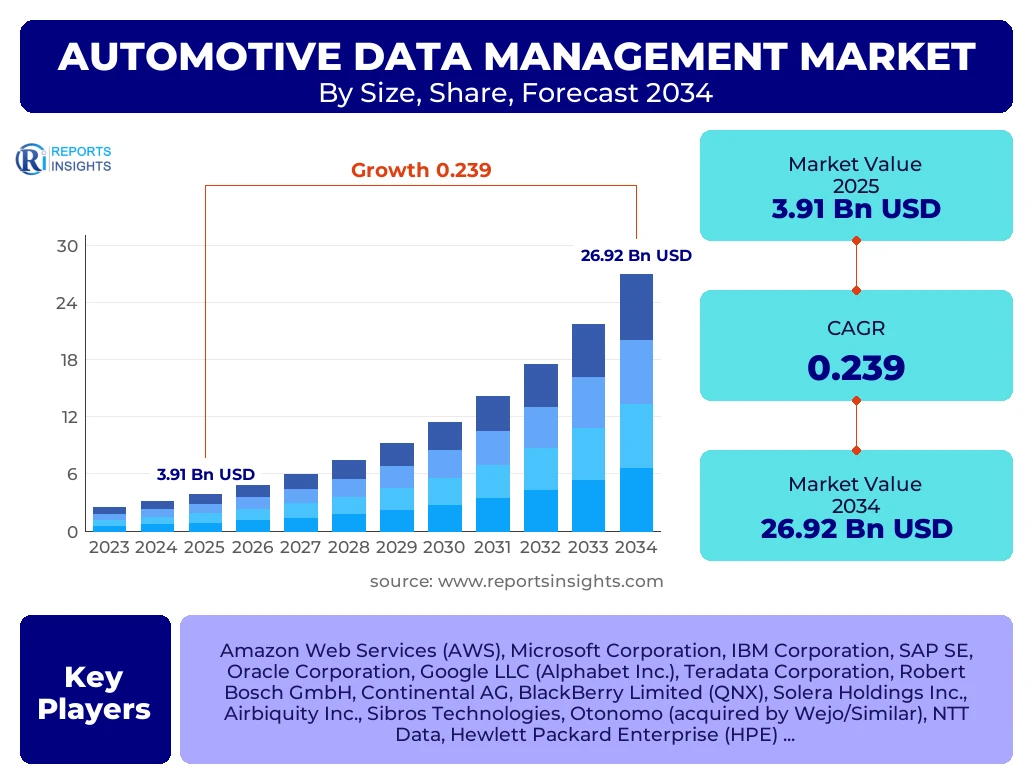
According to Reports Insights Consulting Pvt Ltd, The Automotive Data Management Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 23.9% between 2025 and 2034. The market is estimated at 4.85 Billion USD in 2026 and is projected to reach 26.92 Billion USD by the end of the forecast period in 2034.
Key Automotive Data Management Market Trends & Insights
The global automotive landscape is undergoing a radical transition from hardware-centric engineering to software-defined mobility architectures. This paradigm shift necessitates a robust data management framework capable of handling the massive influx of information generated by connected vehicles, autonomous sensors, and telematics systems. Current market intelligence indicates that the integration of artificial intelligence (AI) and machine learning (ML) at the edge is no longer optional but a core requirement for real-time decision-making. Stakeholders are increasingly focusing on data sovereignty and cybersecurity to mitigate the risks associated with high-speed data transmission and remote vehicle control. Furthermore, the rise of vehicle-to-everything (V2X) communication is driving the demand for standardized data protocols that allow disparate systems to communicate seamlessly across diverse geographical regions.
- Largest Region: North America currently holds the largest market share, driven by the presence of major technology providers and the early adoption of advanced driver-assistance systems (ADAS) among premium vehicle manufacturers.
- Fastest Growing Region: Asia-Pacific is identified as the fastest-growing region, primarily due to the rapid expansion of the electric vehicle (EV) ecosystem in China and India, coupled with massive government investments in smart city infrastructure.
- Largest Segment: The Cloud-based deployment segment dominates the market share as OEMs prioritize scalability and remote over-the-air (OTA) update capabilities to maintain vehicle performance.
- Emerging Trend: The adoption of Edge Computing is surging to reduce latency in autonomous driving functions, allowing data processing to occur closer to the source rather than relying solely on centralized cloud servers.
Key Takeaways Automotive Data Management Market Size & Forecast
The valuation of the Automotive Data Management market is intrinsically linked to the proliferation of autonomous driving levels and the increasing complexity of vehicle electronics. As vehicles evolve into "data centers on wheels," the volume of unstructured data—comprising video feeds, LIDAR point clouds, and radar signals—is expected to grow exponentially. Market participants are shifting their focus toward unified data platforms that can consolidate data from design, manufacturing, and post-sales vehicle telemetry. This holistic approach enables predictive maintenance and personalized insurance models, creating new revenue streams for original equipment manufacturers (OEMs). The forecast period suggests a high degree of consolidation as traditional automotive suppliers partner with big-tech firms to bridge the gap between mechanical engineering and cloud computing.
- Leading Countries: The United States, China, Germany, and Japan remain the primary hubs for automotive data innovation and high-value patent filings.
- Market Driver: Increased consumer demand for personalized infotainment and connected services is a primary catalyst for sophisticated data orchestration.
- Strategic Shift: Transition from proprietary legacy systems to open-source and interoperable data architectures to foster ecosystem-wide collaboration.
- Safety Standards: Stringent government regulations regarding vehicle safety and emissions are mandating more rigorous data logging and reporting mechanisms.
Automotive Data Management Market Drivers Analysis
The primary growth engines for this market revolve around the technological maturity of autonomous systems and the consumer-led demand for connected vehicle features. OEMs are leveraging data to enhance the user experience while optimizing operational efficiencies throughout the vehicle lifecycle.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advancements in Autonomous Driving Levels (Level 3 to 5) | +7.5% | North America & Europe | 2025 - 2034 |
| Proliferation of Software-Defined Vehicles (SDV) | +6.2% | Global | 2026 - 2032 |
| Regulatory Mandates for Black Box Data Recorders | +4.1% | European Union | 2025 - 2028 |
| Rising Demand for Predictive Maintenance & Fleet Analytics | +5.3% | Asia-Pacific & Latin America | 2026 - 2034 |
Automotive Data Management Market Restraints Analysis
Despite the optimistic growth trajectory, the market faces significant hurdles related to data privacy, cybersecurity vulnerabilities, and the high cost associated with upgrading legacy manufacturing infrastructure to support modern data protocols.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Data Privacy Laws (GDPR, CCPA) | -3.2% | Europe & USA | Ongoing |
| High Initial Investment in Cloud Infrastructure | -2.8% | Developing Economies | 2025 - 2029 |
| Interoperability Issues Between Different OEM Platforms | -2.5% | Global | 2025 - 2034 |
Automotive Data Management Market Opportunities Analysis
Significant opportunities lie in the monetization of vehicle data and the development of specialized AI chips designed for in-vehicle data processing. Furthermore, the expansion of 5G networks provides a foundation for more reliable and faster data transmission.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| 5G Network Expansion for Real-Time V2X | +5.8% | China & South Korea | 2025 - 2030 |
| Monetization of Big Data for Insurance & Advertising | +4.4% | Global | 2027 - 2034 |
| Blockchain for Secure Data Sharing in Supply Chains | +3.1% | Europe | 2028 - 2034 |
Automotive Data Management Market Challenges Impact Analysis
The industry must navigate complex challenges including the shortage of skilled data scientists within the automotive sector and the technical difficulty of managing heterogeneous data types across millions of active vehicle nodes.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity Threats Targeting Connected Cars | -2.1% | Global | Ongoing |
| Shortage of Specialized Automotive Data Architects | -1.8% | Global | 2025 - 2030 |
| Bandwidth Constraints for Large Data Uploads | -1.5% | Remote Regions | 2025 - 2032 |
Automotive Data Management Market - Updated Report Scope
This report provides a granular analysis of the global Automotive Data Management ecosystem, covering the entire value chain from data generation and ingestion to advanced analytics and monetization. It investigates the technical transition from on-premise data silos to hybrid cloud environments and the role of edge computing in the future of autonomous mobility. The scope includes a detailed evaluation of various data types including telematics, infotainment, ADAS, and manufacturing data, providing stakeholders with actionable insights into market dynamics and competitive positioning.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | 3.91 Billion USD |
| Market Forecast in 2034 | 26.92 Billion USD |
| Growth Rate | 23.9% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Amazon Web Services (AWS), Microsoft Corporation, IBM Corporation, SAP SE, Oracle Corporation, Google LLC (Alphabet Inc.), Teradata Corporation, Robert Bosch GmbH, Continental AG, BlackBerry Limited (QNX), Solera Holdings Inc., Airbiquity Inc., Sibros Technologies, Otonomo (acquired by Wejo/Similar), NTT Data, Hewlett Packard Enterprise (HPE), Capgemini SE, DXC Technology. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Automotive Data Management market is segmented into several critical categories that reflect the technological and operational needs of the industry. The deployment of cloud-native applications has revolutionized how OEMs manage data, while the distinction between structured and unstructured data determines the complexity of the analytical tools required for processing. As autonomous features become more standard, the "Application" segment is seeing a shift from simple diagnostics toward complex environmental perception and real-time path planning.
- By Component:
- Software: Includes data integration tools, storage platforms, and analytics engines.
- Services: Encompasses consulting, system integration, and support/maintenance.
- By Deployment Model:
- Cloud-based: Facilitates scalability and real-time remote access.
- On-premise: Preferred by some OEMs for highly sensitive R&D data.
- Hybrid: Combining local processing for speed and cloud processing for deep analytics.
- By Data Type:
- Structured: Financial, supply chain, and basic telematics data.
- Unstructured: Complex sensor data (LIDAR, Radar, Video) requiring AI for interpretation.
- By Application:
- Autonomous Driving: High-volume data management for safety-critical systems.
- Predictive Maintenance: Utilizing sensor data to forecast component failure.
- Fleet Management: Optimizing logistics and fuel consumption via real-time tracking.
Regional Highlights
Regional variations in the Automotive Data Management market are shaped by local manufacturing strengths, government regulations, and the maturity of digital infrastructure. North America leads the way in software innovation, while Europe emphasizes data protection and safety standards. The Asia-Pacific region represents the most dynamic theater of growth, fueled by the aggressive adoption of smart technologies and massive production volumes.
- North America: The largest market share holder, dominated by tech giants and advanced automotive R&D centers in the Silicon Valley and Detroit. The focus is on high-level autonomous driving and integrated cloud ecosystems.
- Europe: Characterized by stringent data regulations (GDPR) and a high concentration of premium OEMs like BMW, Mercedes-Benz, and Volkswagen who are investing heavily in secure data processing and V2X technologies.
- Asia-Pacific: The fastest-growing market. China is the powerhouse here, with significant government backing for the New Energy Vehicle (NEV) sector and smart city projects that integrate vehicle data with urban infrastructure.
- Latin America & MEA: Emerging markets with growing interest in fleet management solutions and telematics to improve logistics efficiency and vehicle security in urban centers.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Automotive Data Management Market.- Amazon Web Services (AWS)
- Microsoft Corporation
- IBM Corporation
- SAP SE
- Oracle Corporation
- Google LLC (Alphabet Inc.)
- Teradata Corporation
- Robert Bosch GmbH
- Continental AG
- BlackBerry Limited (QNX)
- Solera Holdings Inc.
- Airbiquity Inc.
- Sibros Technologies
- Hewlett Packard Enterprise (HPE)
- Capgemini SE
- DXC Technology
- Aptiv PLC
- Informatica Inc.
- Cloudera Inc.
Frequently Asked Questions
What is the current and projected size of the Automotive Data Management Market?
The market is estimated at 4.85 Billion USD in 2026 and is projected to expand to 26.92 Billion USD by 2034, growing at a CAGR of 23.9% during the forecast period.
How does Edge Computing impact the Automotive Data Management industry?
Edge Computing enables real-time data processing within the vehicle, reducing latency for critical functions like autonomous braking and obstacle detection, which reduces the reliance on cloud-based latency.
Which region is expected to grow the fastest in the Automotive Data Management market?
Asia-Pacific is the fastest-growing region due to rapid urbanization, increasing EV adoption, and substantial investments in smart traffic management systems in countries like China and India.
What are the main challenges facing data management in the automotive sector?
Key challenges include ensuring robust cybersecurity against hacking, complying with complex international data privacy laws (like GDPR), and managing the immense volume of unstructured sensor data.
How are OEMs monetizing vehicle data?
OEMs monetize data by offering personalized services, improving predictive maintenance to reduce warranty costs, and partnering with insurance companies for usage-based insurance (UBI) models.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
