Automotive Plastic Compounding Market
Automotive Plastic Compounding Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710884 | Published On : September 14, 2026 |
Format : 


 | Author : Ashraf Shehata
Automotive Plastic Compounding Market Size
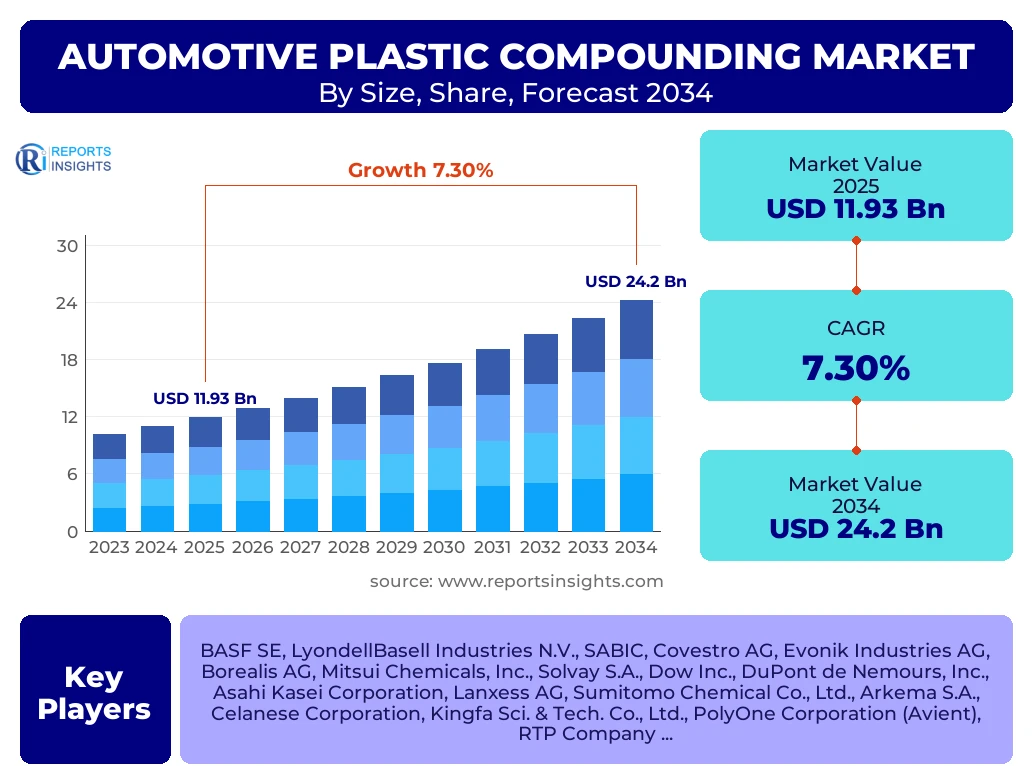
According to Reports Insights Consulting Pvt Ltd, The Automotive Plastic Compounding Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.3% between 2026 and 2034. The market is estimated at USD 12.8 Billion in 2026 and is projected to reach USD 24.2 Billion by the end of the forecast period in 2034.
Key Automotive Plastic Compounding Market Trends & Insights
The global landscape for automotive plastic compounding is undergoing a radical transformation driven by the dual imperatives of vehicle electrification and circular economy mandates. Market participants are increasingly focusing on high-performance thermoplastics that offer superior thermal stability and mechanical strength while facilitating significant weight reduction. Analysis of regional consumption patterns indicates a decisive shift toward Asia-Pacific as the primary manufacturing hub, while European markets lead in the adoption of recycled and bio-based compounded resins. The integration of advanced additives to enhance flame retardancy in Electric Vehicle (EV) battery packs and the development of antimicrobial surfaces for shared mobility interior components represent the most significant technological pivots in the current fiscal landscape.
- Largest Region: Asia-Pacific remains the dominant market, accounting for over 45% of global revenue share due to massive production volumes in China and India.
- Fastest Growing Region: South East Asia and parts of Latin America are witnessing accelerated growth as OEMs diversify their supply chains.
- Largest Segment: Polypropylene (PP) compounds hold the largest market share owing to their versatility, low cost, and extensive use in interior and exterior trim.
- Emerging Trend: Carbon-fiber reinforced plastic (CFRP) compounding is seeing a surge in high-end performance vehicles and premium EV models.
Key Takeaways Automotive Plastic Compounding Market Size & Forecast
The long-term outlook for the automotive plastic compounding sector remains robust, supported by stringent emission regulations such as Euro 7 and CAFE standards which necessitate the replacement of metal components with lightweight plastic alternatives. Stakeholders are prioritizing vertical integration to secure raw material supplies and investing in chemical recycling technologies to meet the growing demand for sustainable materials. The forecast period is expected to see a consolidation of market players as smaller compounders struggle to keep pace with the high R&D requirements for specialized engineering plastics used in autonomous driving sensors and power electronics housing.
- Market Valuation: The total addressable market is expected to nearly double by 2034, driven by an average of 250kg of plastic used per vehicle in modern designs.
- EV Impact: Electric vehicles require specialized compounds for high-voltage connectors and battery enclosures, offering higher margins than traditional ICE components.
- Sustainability: Post-consumer recycled (PCR) content in automotive compounds is projected to become a mandatory requirement in major markets by 2030.
- Leading Material: Polypropylene (PP) and Polyamide (PA) will continue to lead the polymer segment due to their excellent balance of performance and processability.
Automotive Plastic Compounding Market Drivers Analysis
The primary catalyst for market expansion is the global push for vehicle lightweighting to improve fuel efficiency in internal combustion engines and extend the range of electric vehicles. As OEMs strive to meet aggressive carbon neutrality targets, the substitution of heavy steel and aluminum components with glass or carbon fiber reinforced plastic compounds has become a critical engineering strategy. Additionally, the rising consumer demand for premium interior aesthetics and enhanced safety features is driving the consumption of high-grade aesthetic and structural compounds.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Acceleration of EV Production and Battery Housing Needs | +2.4% | Global (Strongest in China and Germany) | 2025–2034 |
| Stringent Fuel Efficiency and CO2 Emission Standards | +1.8% | Europe and North America | 2025–2030 |
| Demand for Advanced Interior Aesthetics and Haptics | +1.2% | Global | 2026–2034 |
Automotive Plastic Compounding Market Restraints Analysis
Market growth is tempered by the volatility of petrochemical feedstock prices, which directly impacts the production costs of base resins. Furthermore, the technical challenges associated with the recyclability of multi-material compounds and the high costs of high-performance engineering plastics compared to traditional materials act as significant barriers. Regulatory scrutiny over microplastics and chemical additives also poses a potential long-term risk to certain plastic types used in the compounding process.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatile Raw Material (Crude Oil) Prices | -1.1% | Global | Ongoing |
| Strict Environmental Regulations on Non-Recyclable Plastics | -0.8% | European Union | 2027–2034 |
Automotive Plastic Compounding Market Opportunities Analysis
The shift toward circularity presents a massive opportunity for companies specializing in the compounding of post-consumer and post-industrial recycled plastics. Innovations in "smart plastics" that can integrate sensors or provide EMI/RFI shielding for autonomous vehicle electronics are also opening new, high-value revenue streams. Furthermore, the expansion of the automotive sector in emerging economies offers untapped potential for standard compounding grades used in entry-level vehicle segments.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Bio-based and Biodegradable Compounds | +1.5% | North America and Europe | 2026–2034 |
| Thermal Management Solutions for EV Power Electronics | +2.1% | Japan, Korea, and China | 2025–2034 |
| 3D Printing/Additive Manufacturing Compounds | +0.6% | Global (Prototyping & Customization) | 2028–2034 |
Automotive Plastic Compounding Market Challenges Impact Analysis
One of the most pressing challenges is maintaining the mechanical integrity of compounded plastics over the long vehicle lifecycle, especially when incorporating high percentages of recycled content. Compounding companies also face the logistical challenge of managing complex global supply chains and the technical difficulty of ensuring consistent material quality across different production batches. Competition from alternative lightweight materials like magnesium alloys and high-strength steel remains a constant pressure point.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Material Degradation in Recycled Feedstock | -0.5% | Global | 2025–2030 |
| Supply Chain Disruptions for Specialty Additives | -0.7% | APAC and North America | Ongoing |
Automotive Plastic Compounding Market - Updated Report Scope
This comprehensive report provides a detailed quantitative and qualitative analysis of the automotive plastic compounding market, covering various polymer types, reinforcement materials, and end-use applications across all major geographic regions. The scope includes a deep dive into the impact of the transition from ICE to EV, the role of sustainability in material selection, and a competitive benchmarking of the top industry players. The report utilizes proprietary data models to forecast market dynamics through 2034, ensuring stakeholders have the most accurate and actionable intelligence for strategic planning.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 11.93 Billion |
| Market Forecast in 2034 | USD 24.2 Billion |
| Growth Rate | 7.3% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, LyondellBasell Industries N.V., SABIC, Covestro AG, Evonik Industries AG, Borealis AG, Mitsui Chemicals, Inc., Solvay S.A., Dow Inc., DuPont de Nemours, Inc., Asahi Kasei Corporation, Lanxess AG, Sumitomo Chemical Co., Ltd., Arkema S.A., Celanese Corporation, Kingfa Sci. & Tech. Co., Ltd., PolyOne Corporation (Avient), RTP Company, Washington Penn Plastic Co., Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is intricately segmented to reflect the diverse functional requirements of automotive components. The polymer type remains the primary differentiator, with Polypropylene (PP) leading the volume share due to its adaptability in injection molding for large interior and exterior parts. The Polyamide (PA) segment is witnessing significant value growth, particularly in under-the-hood applications where thermal resistance is paramount. Furthermore, the segmentation by vehicle type reveals that while Passenger Cars currently dominate, the Electric Vehicle (EV) segment is the fastest-growing sub-sector, requiring specialized high-performance compounds for thermal management and battery safety.
- Polymer Type: Polypropylene (PP), Polyamide (PA), Polyurethane (PU), Polyvinyl Chloride (PVC), Acrylonitrile Butadiene Styrene (ABS), Polycarbonate (PC), Polyethylene (PE), Polystyrene (PS), and Engineering Plastics.
- Reinforcement Material: Glass Fiber Reinforced, Carbon Fiber Reinforced, Natural Fiber Reinforced, and Mineral Filled Compounds.
- Application Area: Interior (Dashboard, Seat Covers, Trim), Exterior (Bumpers, Lighting, Body Panels), Under-the-hood (Manifolds, Cooling Systems), and Electrical & Electronics (Sensors, Connectors, Battery Housings).
- Vehicle Category: Internal Combustion Engine (ICE) Vehicles, Hybrid Electric Vehicles (HEV), Battery Electric Vehicles (BEV), and Commercial Vehicles.
Regional Highlights
- Asia-Pacific: The regional powerhouse, led by China, is the largest consumer and producer. The rapid expansion of the domestic EV industry in China and the growing automotive manufacturing base in India and Thailand make it the most critical region for market volume.
- Europe: This region is at the forefront of sustainability trends. Germany, France, and Italy are leading the transition toward mandatory recycled content in automotive plastics, making Europe the primary market for high-value sustainable compounds.
- North America: Market growth is driven by the demand for lightweighting in SUVs and Light Trucks. The presence of major OEMs and a strong focus on advanced material R&D in the United States sustain steady market value.
- Latin America & MEA: These regions are emerging as secondary growth centers, with Mexico serving as a vital manufacturing hub for the North American market, and South Africa seeing increased automotive assembly investments.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Automotive Plastic Compounding Market.- BASF SE
- LyondellBasell Industries N.V.
- SABIC
- Covestro AG
- Evonik Industries AG
- Borealis AG
- Mitsui Chemicals, Inc.
- Solvay S.A.
- Dow Inc.
- DuPont de Nemours, Inc.
- Asahi Kasei Corporation
- Lanxess AG
- Sumitomo Chemical Co., Ltd.
- Arkema S.A.
- Celanese Corporation
- Kingfa Sci. & Tech. Co., Ltd.
- Avient Corporation
- RTP Company
- Washington Penn Plastic Co., Inc.
- Daicel Corporation
Frequently Asked Questions
What is driving the growth of the Automotive Plastic Compounding Market?
The primary growth drivers include the urgent need for vehicle lightweighting to improve fuel efficiency and EV range, stringent government emission regulations, and the increasing use of plastics in battery housings and electrical components in electric vehicles.
Which polymer type is most commonly used in automotive compounding?
Polypropylene (PP) is the most widely used polymer due to its excellent balance of cost, weight, and versatility, making it ideal for a wide range of interior and exterior automotive applications.
How is the transition to Electric Vehicles (EVs) affecting the market?
The transition to EVs is shifting demand toward high-performance engineering plastics that offer flame retardancy, high thermal conductivity for battery cooling, and EMI/RFI shielding for electronic control units.
What are the key sustainability trends in automotive plastic compounding?
Key trends include the incorporation of post-consumer recycled (PCR) materials, the development of bio-based resins derived from renewable sources, and the design of components for easier end-of-life disassembly and recycling.
Which region holds the largest share of the Automotive Plastic Compounding Market?
The Asia-Pacific region currently holds the largest market share, driven by high vehicle production rates in China, Japan, India, and South Korea, coupled with an expanding consumer base.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted