Assets Under Management Market
Assets Under Management Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711788 | Published On : November 16, 2026 |
Format : 


 | Author : Ram Krishnan
Assets Under Management Market Size
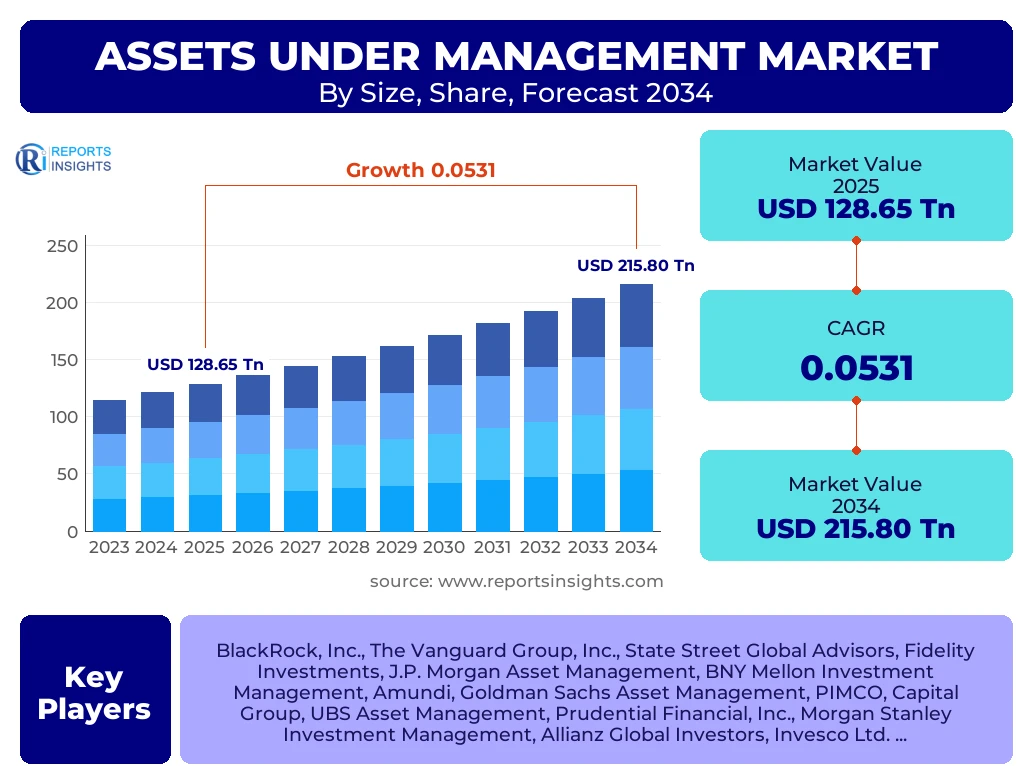
According to Reports Insights Consulting Pvt Ltd, The Assets Under Management Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.31% between 2025 and 2034. The market is estimated at USD 135.50 Trillion in 2026 and is projected to reach USD 215.80 Trillion by the end of the forecast period in 2034.
Key Assets Under Management Market Trends & Insights
The global landscape for Assets Under Management (AUM) is undergoing a systemic transformation driven by the convergence of institutional digitalization, a pivot toward private markets, and the integration of sustainability frameworks. Institutional investors are increasingly moving away from traditional 60/40 portfolios in favor of alternative assets, such as private equity, infrastructure, and real estate, seeking alpha in a volatile macroeconomic environment. Furthermore, the democratization of finance through retail investment platforms and robo-advisory services has significantly expanded the potential investor base. This shift is accompanied by intense fee compression, forcing traditional asset managers to optimize operational efficiencies through artificial intelligence and distributed ledger technologies to maintain profit margins while delivering superior risk-adjusted returns.
- North America remains the largest region globally, underpinned by the robustness of the US retirement market and the concentration of major global institutional funds.
- Asia Pacific is identified as the fastest-growing region, fueled by rising middle-class wealth in China and India and the expansion of sovereign wealth funds across Southeast Asia.
- The Passive Management segment continues to hold a significant and growing share of the market, as low-cost Exchange Traded Funds (ETFs) gain favor over actively managed mutual funds.
- Alternative Assets represent the highest-growth segment by asset class, driven by institutional demand for non-correlated returns and long-term yield.
Key Takeaways Assets Under Management Market Size & Forecast
The Assets Under Management market forecast indicates a steady trajectory characterized by the consolidation of major players and the rise of boutique firms specializing in ESG (Environmental, Social, and Governance) and thematic investing. The forecast period between 2025 and 2034 is expected to see a fundamental restructuring of fee models, where performance-linked structures become more prevalent than traditional fixed management fees. As the global economy navigates inflationary pressures and shifting interest rate cycles, the role of asset managers as strategic capital allocators becomes more critical. Market participants are increasingly focusing on localized strategies to capture wealth in emerging economies while simultaneously scaling global operations to leverage economies of scale.
- The United States maintains its position as the leading country in total AUM value, supported by deep capital markets and a mature pension fund ecosystem.
- Environmental, Social, and Governance (ESG) integration has evolved from a niche preference to a core institutional mandate, influencing nearly 40 percent of new capital allocations.
- Technological integration, specifically the use of Generative AI for predictive analytics and client personalization, is a primary differentiator for market leaders.
- Sovereign Wealth Funds (SWFs) in the Middle East and Norway are emerging as dominant global liquidity providers, significantly impacting cross-border investment flows.
Assets Under Management Market Drivers Analysis
The primary drivers of the global AUM market include the structural shift toward defined contribution pension schemes and the rapid accumulation of private wealth in emerging markets. As governments worldwide transition away from state-funded pension systems, individuals are increasingly responsible for their own retirement planning, leading to a surge in retail capital inflows into managed funds. Additionally, the proliferation of digital brokerage platforms has lowered the barrier to entry for retail investors, creating a new channel for capital growth.
Furthermore, the demand for sophisticated risk management tools in an era of geopolitical uncertainty is driving institutional clients toward professional asset management services. The rise of "thematic investing" — focusing on secular trends like the energy transition, cybersecurity, and aging populations — provides asset managers with opportunities to launch specialized products that command higher margins. The ongoing institutionalization of family offices also provides a steady stream of high-net-worth capital that requires professional oversight and diversified allocation strategies.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Defined Contribution Pension Plans | +1.45% | Global / North America | 2025 - 2034 |
| Digitalization and Fintech Proliferation | +0.95% | Asia Pacific / India / China | 2025 - 2030 |
| Growth in Alternative Asset Demand | +1.10% | Europe / North America | 2026 - 2034 |
| Institutionalization of Private Wealth | +0.75% | Middle East / MEA | 2025 - 2034 |
Assets Under Management Market Restraints Analysis
A significant restraint facing the AUM market is the ongoing compression of management fees, particularly in the active management space. As passive investment vehicles and low-cost index funds become the default choice for many investors, traditional firms are finding it difficult to justify high expense ratios, leading to narrowed profit margins. This pressure is compounded by the rising cost of compliance, as regulatory bodies in the EU and North America introduce stricter transparency and reporting requirements concerning ESG claims and fee disclosures.
Moreover, the volatility of global financial markets and the potential for prolonged periods of low interest rates can hinder the growth of AUM by reducing the valuation of underlying assets. Operational complexities associated with legacy IT systems also pose a risk, as firms struggle to integrate modern data analytics and cybersecurity measures. The threat of "greenwashing" allegations also presents a reputational risk that could lead to capital outflows if investors lose confidence in a firm’s sustainability credentials.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fee Compression and Rise of Passive Investing | -0.80% | North America / Europe | 2025 - 2034 |
| Increased Regulatory Compliance Costs | -0.55% | European Union / UK | 2025 - 2029 |
| Market Volatility and Geopolitical Risk | -0.40% | Global | 2026 - 2030 |
Assets Under Management Market Opportunities Analysis
The integration of Artificial Intelligence (AI) and Machine Learning (ML) into investment processes presents a transformative opportunity for asset managers to enhance performance and lower operational costs. By leveraging big data for sentiment analysis and predictive modeling, firms can identify market inefficiencies more rapidly than traditional research methods. Additionally, the tokenization of real-world assets using blockchain technology offers a path toward increasing the liquidity of traditionally illiquid assets like real estate and private equity, opening these markets to a broader range of investors.
Another significant opportunity lies in the transition toward a low-carbon economy. The massive capital requirements for global infrastructure decarbonization provide a fertile ground for climate-focused investment funds and green bonds. Asset managers who can demonstrate verifiable impact and align their strategies with global climate goals are likely to capture a significant portion of the "wealth transfer" currently occurring as younger, socially conscious generations inherit trillions of dollars in assets.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| AI-Driven Alpha Generation | +1.20% | United States / Japan / UK | 2025 - 2034 |
| Tokenization of Real-World Assets (RWA) | +0.85% | Singapore / Switzerland / UAE | 2027 - 2034 |
| Climate Finance and Energy Transition | +1.50% | Global / EU | 2025 - 2034 |
Assets Under Management Market Challenges Impact Analysis
One of the most pressing challenges is the talent gap in specialized fields such as quantitative finance, data science, and ESG auditing. As the industry moves toward more complex investment strategies, the competition for skilled professionals has intensified, leading to higher labor costs. Furthermore, the threat of cyberattacks targeting financial institutions is at an all-time high, requiring massive investments in defensive infrastructure to protect client data and prevent market manipulation.
Additionally, the fragmentation of global regulations makes it difficult for asset managers to operate seamlessly across different jurisdictions. The lack of standardized ESG reporting metrics often leads to confusion and inconsistency in portfolio evaluation, making it difficult for institutional investors to compare performance accurately. Firms also face the challenge of managing the "liquidity mismatch" in certain funds, where the underlying assets are illiquid but investors expect daily or weekly redemption options, potentially leading to systemic risks during market downturns.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity Threats and Data Privacy | -0.45% | Global / North America | 2025 - 2034 |
| Regulatory Fragmentation in ESG Reporting | -0.35% | European Union / APAC | 2025 - 2028 |
| Liquidity Mismatch in Private Market Funds | -0.50% | Global Institutional Market | 2026 - 2032 |
Assets Under Management Market - Updated Report Scope
This comprehensive report provides a detailed analysis of the global Assets Under Management market, encompassing traditional and alternative asset classes. It examines the strategic shifts in capital allocation between institutional and retail clients while providing granular insights into regional growth drivers. The scope includes an evaluation of management styles (Active vs. Passive), the impact of technological disruption, and the evolving regulatory landscape across primary financial hubs.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 128.65 Trillion |
| Market Forecast in 2034 | USD 215.80 Trillion |
| Growth Rate | 5.31% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BlackRock, Inc., The Vanguard Group, Inc., State Street Global Advisors, Fidelity Investments, J.P. Morgan Asset Management, BNY Mellon Investment Management, Amundi, Goldman Sachs Asset Management, PIMCO, Capital Group, UBS Asset Management, Prudential Financial, Inc., Morgan Stanley Investment Management, Allianz Global Investors, Invesco Ltd., Northern Trust Asset Management, Wellington Management Company, T. Rowe Price Associates, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Assets Under Management market highlights the diverging growth paths of traditional equity funds versus the rapidly expanding alternative investment sector. While equity remains the largest asset class by volume, the fixed-income segment is seeing a resurgence as interest rates stabilize. The client-side segmentation reveals that institutional investors still command the majority of AUM, but the retail segment is growing at a faster rate due to the democratization of sophisticated investment tools. Furthermore, the shift from active to passive management continues to redefine the competitive dynamics of the industry.
- By Asset Class: Equity, Fixed Income, Cash/Money Market, Alternatives (Private Equity, Real Estate, Hedge Funds, Infrastructure, Commodities), Digital Assets.
- By Management Style: Active Management, Passive Management.
- By Client Type: Institutional (Pension Funds, Insurance Companies, Sovereign Wealth Funds, Endowments and Foundations), Retail (High Net Worth Individuals, Mass Affluent, Individual Retail Investors).
- By Distribution Channel: Institutional Direct, Financial Intermediaries, Digital Platforms/Robo-Advisors.
Regional Highlights
- North America: Currently the largest market globally, representing over 45% of total AUM. Growth is driven by the mature 401(k) and IRA landscape and the presence of the world's largest asset managers.
- Asia Pacific: The fastest-growing region with a projected CAGR of 7.2%. The expansion is led by China's pension reforms, India's burgeoning mutual fund industry, and high savings rates across Southeast Asia.
- Europe: A dominant hub for ESG-integrated assets, driven by strict regulatory frameworks like the SFDR. Large institutional markets in the UK, Germany, and France continue to drive innovation in sustainable finance.
- Middle East and Africa: Experiencing significant growth in Sovereign Wealth Fund (SWF) activity, with major capital pools in Saudi Arabia and the UAE diversifying away from oil-related revenues.
- Latin America: Showing resilience through pension fund consolidation in countries like Brazil and Mexico, though growth is susceptible to regional currency fluctuations.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Assets Under Management Market.- BlackRock, Inc.
- The Vanguard Group, Inc.
- State Street Global Advisors
- Fidelity Investments
- J.P. Morgan Asset Management
- BNY Mellon Investment Management
- Amundi
- Goldman Sachs Asset Management
- PIMCO (Pacific Investment Management Co.)
- Capital Group
- UBS Asset Management
- Prudential Financial, Inc.
- Morgan Stanley Investment Management
- Allianz Global Investors
- Invesco Ltd.
- Northern Trust Asset Management
- Wellington Management Company
- T. Rowe Price Associates, Inc.
- Franklin Templeton
- Legal & General Investment Management
Frequently Asked Questions
What are the main factors driving the growth of Assets Under Management (AUM)?
The primary drivers include the global transition from defined benefit to defined contribution pension plans, the expansion of the middle class in emerging markets, and the increasing institutional demand for alternative assets like private equity and infrastructure to hedge against inflation.
How is Artificial Intelligence impacting the asset management industry?
AI is being utilized to enhance alpha generation through predictive analytics, automate middle-office operations for cost efficiency, and provide hyper-personalized investment advice to retail clients through robo-advisory platforms.
Why is there a significant shift from active to passive management?
Investors are increasingly favoring passive management due to its lower expense ratios and the historical difficulty many active managers face in consistently outperforming benchmark indices after fees, leading to massive inflows into ETFs and index funds.
What role does ESG play in modern AUM strategies?
ESG has become a fundamental risk management tool and a fiduciary requirement for many institutional investors. It involves integrating environmental, social, and governance factors into the investment process to identify long-term sustainability risks and opportunities.
Which region is expected to see the highest growth in AUM by 2034?
Asia Pacific is expected to be the fastest-growing region, driven by rapid wealth accumulation, regulatory liberalization in financial services, and the expansion of digital investment platforms across China, India, and Southeast Asia.
Author
R
Ram Krishnan is a Manger Industry Services Research with 7+ years of experience in the Industry Services Industry. He specializes in industrial services market intelligence, service demand forecasting, competitive benchmarking, outsourcing and managed services analysis, operational performance assessment, market sizing, customer behavior analysis, pricing strategy evaluation, and industry trend forecasting across diverse service sectors. His analytical expertise transforms complex market data into actionable insights, enabling organizations to make strategic business decisions, identify growth opportunities, optimize operations, understand evolving market dynamics, and strengthen their competitive positioning in global industry services markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
