Antiparasitic Drugs Market
Antiparasitic Drugs Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711241 | Published On : October 21, 2026 |
Format : 


 | Author : Erika Grotto
Antiparasitic Drugs Market Size
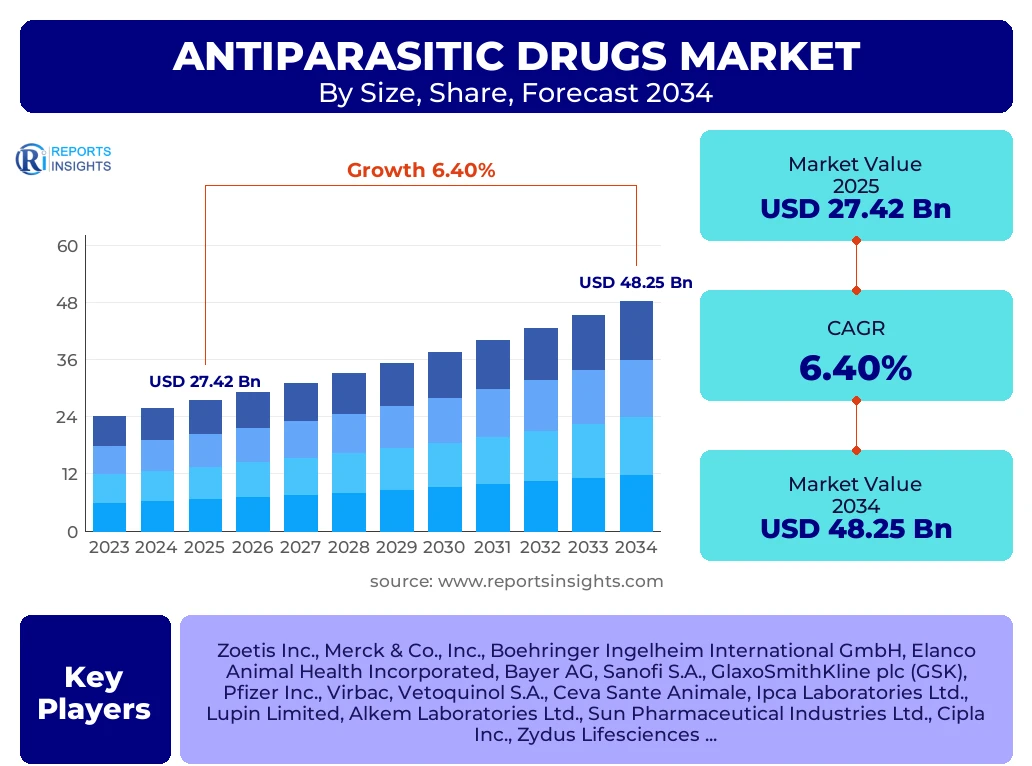
According to Reports Insights Consulting Pvt Ltd, The Antiparasitic Drugs Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.4% between 2025 and 2034. The market is estimated at USD 29.17 Billion in 2026 and is projected to reach USD 48.25 Billion by the end of the forecast period in 2034.
Key Antiparasitic Drugs Market Trends & Insights
The global antiparasitic drugs market is undergoing a significant transformation driven by the dual demand from human healthcare and the expanding veterinary medicine sector. In human health, the persistent burden of neglected tropical diseases (NTDs) and the rising incidence of malaria and intestinal helminthiasis in developing economies remain primary drivers. Conversely, in developed nations, the market is heavily influenced by the humanization of pets and the intensive livestock industry, where preventive care against ectoparasites and endoparasites is a standard protocol. Technological advancements in drug delivery systems, such as long-acting injectables and spot-on treatments, are enhancing patient compliance and therapeutic efficacy. Furthermore, the market is seeing a surge in strategic collaborations between pharmaceutical giants and global health organizations to provide affordable treatments in endemic regions.
- North America is the largest regional market, driven by high pet healthcare spending and advanced pharmaceutical infrastructure.
- Asia-Pacific is the fastest-growing region due to increasing awareness, rising healthcare expenditure, and a large livestock population.
- The veterinary application segment currently holds the largest market share compared to human health applications.
- Anthelmintics represent the largest product segment owing to the high prevalence of worm infections globally.
- Growing resistance to existing antiparasitic agents is pushing the development of combination therapies and novel chemical entities.
Key Takeaways Antiparasitic Drugs Market Size & Forecast
The market forecast indicates a robust upward trajectory, underpinned by a 6.4% CAGR that reflects both steady demand in mature markets and rapid expansion in emerging economies. Strategic shifts toward preventive medicine in animal health and large-scale deworming programs in human health are stabilizing long-term revenue streams. The integration of biotechnology in drug discovery is expected to yield more targeted antiparasitic agents with fewer side effects, further bolstering market valuation through 2034. Stakeholders are increasingly focusing on the "One Health" approach, recognizing the interconnectedness of human, animal, and environmental health in managing parasitic transmissions.
- The United States leads the global market in terms of value, supported by high R&D investments and a well-established regulatory framework.
- China and India are emerging as manufacturing hubs for generic antiparasitic drugs, significantly impacting global supply chains.
- E-commerce and specialized veterinary clinics are becoming dominant distribution channels for over-the-counter antiparasitic products.
- The rise in zoonotic diseases is accelerating government funding for antiparasitic research and surveillance.
- Innovations in "smart" delivery systems are expected to command premium pricing in the forecast period.
Antiparasitic Drugs Market Drivers Analysis
The primary driver for the antiparasitic drugs market is the rising prevalence of parasitic infections globally, particularly in tropical and subtropical regions. According to the World Health Organization, over 1.5 billion people are infected with soil-transmitted helminths worldwide. This immense patient pool necessitates a continuous supply of anthelmintic medications. Additionally, the increasing global temperature due to climate change is expanding the geographical range of disease vectors like mosquitoes and ticks, bringing parasitic threats to previously unaffected regions in Europe and North America.
In the veterinary sector, the trend of pet humanization has led owners to invest significantly in preventive healthcare. Companion animals are now treated as family members, leading to a higher frequency of routine deworming and flea/tick prevention. Simultaneously, the global demand for animal protein is driving the growth of the livestock industry. To ensure high yields and food safety, livestock producers rely heavily on antiparasitic drugs to prevent outbreaks of coccidiosis and other parasitic conditions that can devastate animal populations and cause significant economic losses.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Increased Prevalence of Neglected Tropical Diseases | +1.8% | Africa and Southeast Asia | 2025 - 2034 |
| Rising Pet Ownership and Healthcare Expenditure | +2.1% | North America and Europe | 2025 - 2030 |
| Climate Change Expanding Vector Habitats | +1.2% | Global | 2027 - 2034 |
| Growth in Intensive Livestock Farming | +1.3% | Brazil, China, and Australia | 2025 - 2034 |
Antiparasitic Drugs Market Restraints Analysis
A critical restraint facing the market is the development of multi-drug resistance among various parasites. Overuse and misuse of antiparasitic agents in both humans and livestock have led to reduced efficacy of frontline drugs like ivermectin and artemisinin-based combination therapies. This resistance forces healthcare providers to seek more expensive or complex alternatives, which can limit market growth in cost-sensitive regions. Furthermore, the high cost of drug development and the stringent regulatory requirements for new chemical entities (NCEs) present significant barriers for new entrants.
Environmental concerns regarding the runoff of veterinary antiparasitics into soil and water systems are also leading to stricter regulations. Many ectoparasiticides are toxic to non-target organisms, such as bees and aquatic life, prompting regulatory bodies in the European Union and North America to consider bans or heavy restrictions on certain compounds. These environmental policies can disrupt product availability and increase the cost of compliance for manufacturers, potentially slowing market expansion.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Drug Resistance in Parasites | -1.5% | Global | 2025 - 2034 |
| Stringent Environmental and Safety Regulations | -1.2% | European Union | 2026 - 2034 |
| High Cost of Research and Development | -0.8% | Developed Markets | 2025 - 2030 |
Antiparasitic Drugs Market Opportunities Analysis
Significant opportunities lie in the development of novel drug delivery systems that improve bioavailability and patient compliance. The shift from daily oral dosing to long-acting injectables, transdermal patches, and oral chews (for pets) allows for more effective management of parasitic loads. Furthermore, the emerging markets in Asia-Pacific and Latin America offer untapped potential as their healthcare infrastructures modernize and insurance coverage for veterinary care increases. Companies focusing on these regions with affordable, high-quality generic versions of essential antiparasitics stand to gain substantial market share.
The field of genomics and molecular biology also presents opportunities for "personalized" antiparasitic therapy. By understanding the genetic makeup of parasite strains in specific regions, pharmaceutical companies can develop more targeted and effective treatments. Additionally, there is a growing interest in biological controls and vaccines as alternatives to chemical antiparasitics, which could open a completely new segment within the market focused on sustainable and long-term immunity.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Combination Therapies | +1.6% | Global | 2026 - 2034 |
| Expansion into Emerging Markets (BRICS) | +2.4% | India, Brazil, South Africa | 2025 - 2034 |
| R&D in Antiparasitic Vaccines | +1.1% | Global | 2028 - 2034 |
Antiparasitic Drugs Market Challenges Impact Analysis
One of the foremost challenges is the prevalence of counterfeit and substandard drugs, especially in low-to-middle-income countries. These illicit products not only result in treatment failure and economic loss for legitimate manufacturers but also accelerate the development of drug resistance. Maintaining a secure and transparent supply chain in regions with poor infrastructure remains a logistical hurdle for global pharmaceutical companies. Additionally, the fluctuating prices of raw materials and API (Active Pharmaceutical Ingredient) sourcing can lead to margin pressure for generic manufacturers.
Another challenge is the relatively low profitability of drugs targeting neglected tropical diseases. Since these diseases primarily affect the world's poorest populations, there is a lack of financial incentive for private pharmaceutical companies to invest in R&D without government or NGO subsidies. This leads to a thin pipeline of new drugs for human parasitic infections compared to other therapeutic areas like oncology or cardiology. Balancing commercial viability with global health equity remains a complex challenge for the industry.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Counterfeit Drug Proliferation | -1.1% | Africa and Latin America | 2025 - 2034 |
| API Supply Chain Disruptions | -0.7% | Global | 2025 - 2028 |
| Low R&D Incentives for NTDs | -0.9% | Emerging Economies | 2025 - 2034 |
Antiparasitic Drugs Market - Updated Report Scope
This comprehensive report provides a deep-dive analysis into the global antiparasitic drugs landscape, covering human and veterinary applications, diverse product classes, and all major geographic regions. It evaluates the impact of macroeconomic factors, regulatory shifts, and technological innovations on market dynamics from 2020 through the forecast period ending in 2034. The report aims to equip stakeholders with actionable insights for strategic decision-making and competitive positioning.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 27.42 Billion |
| Market Forecast in 2034 | USD 48.25 Billion |
| Growth Rate | 6.4% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Zoetis Inc., Merck & Co., Inc., Boehringer Ingelheim International GmbH, Elanco Animal Health Incorporated, Bayer AG, Sanofi S.A., GlaxoSmithKline plc (GSK), Pfizer Inc., Virbac, Vetoquinol S.A., Ceva Sante Animale, Ipca Laboratories Ltd., Lupin Limited, Alkem Laboratories Ltd., Sun Pharmaceutical Industries Ltd., Cipla Inc., Zydus Lifesciences, Novartis AG, Abbott Laboratories, Takeda Pharmaceutical Company Limited |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The antiparasitic drugs market is segmented based on product type, application, route of administration, and distribution channel to provide a granular view of the competitive landscape. The veterinary segment currently dominates the application category, fueled by rigorous preventive treatment schedules for companion animals and mandatory health protocols in the livestock industry. In the product category, anthelmintics maintain the largest share due to the universal prevalence of worm-related infections. However, the antiprotozoal segment is witnessing rapid growth due to the persistence of malaria and the emergence of drug-resistant protozoal strains in various regions.
- By Product:
- Anthelmintics: Leading segment due to high demand in both human health (deworming programs) and livestock management.
- Antiprotozoals: Significant growth driven by malaria treatment and increasing cases of giardiasis and amebiasis.
- Ectoparasiticides: High demand in the pet care market for flea, tick, and lice control.
- By Application:
- Human Health: Driven by public health initiatives and the management of infectious diseases in tropical climates.
- Animal Health: The largest revenue contributor, encompassing companion animals (cats, dogs) and livestock (cattle, poultry, swine).
- By Route of Administration:
- Oral: Most common for human treatments and pet chews.
- Injectable: Gaining traction in livestock for long-term protection.
- Topical: Dominant in the ectoparasiticide market (spot-on treatments).
- By Distribution Channel:
- Hospital Pharmacies: Key for acute parasitic infections in humans.
- Retail Pharmacies: Major outlet for over-the-counter antiparasitics.
- Veterinary Clinics: Primary channel for professional animal healthcare.
- Online Channels: The fastest-growing channel due to the convenience of home delivery for pet medications.
Regional Highlights
- North America: The largest market share holder, characterized by sophisticated veterinary services and high awareness of zoonotic diseases. The U.S. is the primary contributor due to high per-capita spending on pet care.
- Europe: A mature market with stringent regulatory standards. Focus is on sustainable livestock farming and advanced human healthcare.
- Asia-Pacific: The fastest-growing region (Expected CAGR of 7.2%). Rising middle-class population, increasing meat consumption, and expanding pet ownership in China and India are key growth drivers.
- Latin America: Significant market for livestock antiparasitics, particularly in Brazil and Argentina, which are major global beef exporters.
- Middle East & Africa: High demand for human antiparasitics due to the endemic nature of malaria and NTDs. Growth is supported by international health funding and government programs.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Antiparasitic Drugs Market.- Zoetis Inc.
- Merck & Co., Inc. (MSD Animal Health)
- Boehringer Ingelheim International GmbH
- Elanco Animal Health Incorporated
- Bayer AG
- Sanofi S.A.
- GlaxoSmithKline plc (GSK)
- Pfizer Inc.
- Virbac
- Vetoquinol S.A.
- Ceva Sante Animale
- Ipca Laboratories Ltd.
- Lupin Limited
- Alkem Laboratories Ltd.
- Sun Pharmaceutical Industries Ltd.
- Cipla Inc.
- Zydus Lifesciences
- Novartis AG
- Abbott Laboratories
- Takeda Pharmaceutical Company Limited
Frequently Asked Questions
What is the projected market size of the Antiparasitic Drugs Market by 2034?
The global antiparasitic drugs market is projected to reach approximately USD 48.25 Billion by 2034, growing at a CAGR of 6.4% from 2026.
Which segment is currently leading the Antiparasitic Drugs Market?
The animal health application segment, specifically within the veterinary sector, currently holds the largest market share due to high demand for preventive treatments in pets and livestock.
What are the main drivers for growth in the Asia-Pacific region?
Growth in Asia-Pacific is driven by increasing healthcare expenditure, a massive livestock population, rising pet humanization trends, and government initiatives to eradicate parasitic diseases in human populations.
How is drug resistance impacting the market?
Drug resistance is a significant restraint that reduces the efficacy of traditional treatments, forcing the industry to invest in more expensive combination therapies and new drug discovery, which can slow growth in price-sensitive markets.
What role does climate change play in the market dynamics?
Climate change acts as a market driver by expanding the geographical range of vectors like mosquitoes, ticks, and fleas, thereby increasing the incidence of parasitic infections in previously unaffected temperate regions.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
