Annual Wellness Visits Market
Annual Wellness Visits Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711678 | Published On : November 12, 2026 |
Format : 


 | Author : Erika Grotto
Annual Wellness Visits Market Size
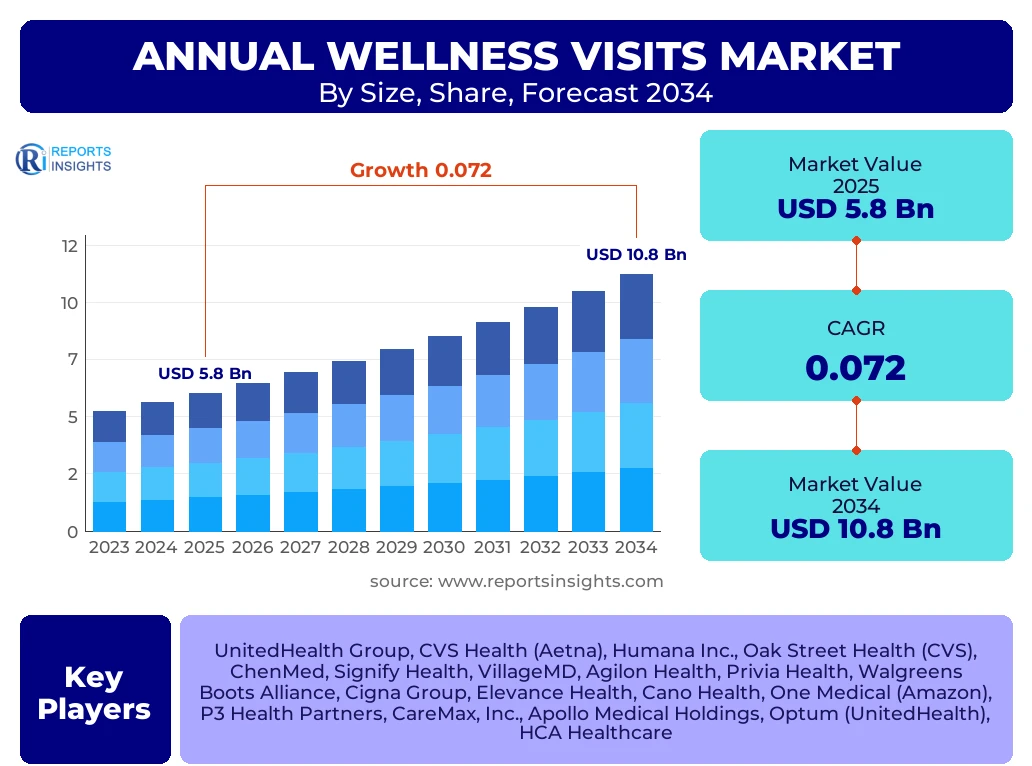
According to Reports Insights Consulting Pvt Ltd, The Annual Wellness Visits Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.2% between 2025 and 2034. The market is estimated at USD 6.2 Billion in 2026 and is projected to reach USD 10.8 Billion by the end of the forecast period in 2034.
Key Annual Wellness Visits Market Trends & Insights
The global Annual Wellness Visits (AWV) market is undergoing a fundamental transformation driven by the transition from volume-based to value-based care models. Stakeholders are increasingly recognizing that preventive screenings and early interventions are the primary levers for reducing long-term healthcare expenditures. Current market trends indicate a significant integration of Advanced Health Risk Assessments (HRA) and Artificial Intelligence (AI) to identify social determinants of health and potential chronic conditions before they escalate. Furthermore, the expansion of Medicare Advantage plans and the inclusion of digital health tools have streamlined the delivery of these visits, making them more accessible to the geriatric population. Competitive benchmarking reveals that leading healthcare providers are focusing on administrative automation to reduce the documentation burden on clinicians, thereby increasing the throughput of wellness visits without compromising patient care quality.
- Largest Region: North America currently holds the largest market share, primarily due to the robust Medicare framework and the established reimbursement structures for Annual Wellness Visits in the United States.
- Fastest Growing Region: Asia Pacific is expected to be the fastest-growing region, fueled by rapidly aging populations in countries like Japan and China, coupled with rising healthcare infrastructure investments.
- Largest Segment: The Subsequent Wellness Visits segment dominates the market by share, as the recurring nature of these visits ensures a steady stream of clinical interactions compared to the one-time Initial Wellness Visit.
- Technological Integration: The adoption of telehealth for conducting remote wellness screenings has emerged as a high-impact trend, particularly for rural and homebound populations.
Key Takeaways Annual Wellness Visits Market Size & Forecast
The market trajectory for Annual Wellness Visits is characterized by steady, resilient growth, underpinned by demographic shifts and regulatory incentives. Analysis of user inquiries suggests a high level of interest in how reimbursement rates for CPT codes G0438 and G0439 are evolving and how technology vendors are closing the gap in patient engagement. The forecast period anticipates a substantial rise in "Hybrid Wellness Models," where data from wearable devices is integrated into the annual clinical review. This evolution is turning the AWV from a simple checklist into a comprehensive, data-driven health strategy. Consequently, organizations that prioritize seamless data interoperability and patient outreach are positioned to capture the highest market value.
- Market Leadership: The United States remains the undisputed leader in market value, driven by federal mandates and high Medicare enrollment.
- Strategic Shift: There is a visible shift from standalone primary care visits to integrated care coordination programs that leverage AWVs as the foundation for chronic care management.
- Demographic Driver: The aging baby boomer population is the primary catalyst for the increasing volume of wellness visits globally.
- Digital Transformation: Electronic Health Record (EHR) integrated HRA tools are becoming standard, reducing the time required for administrative compliance and improving data accuracy.
Annual Wellness Visits Market Drivers Analysis
The primary engine driving the Annual Wellness Visits market is the global shift toward preventive healthcare. Governments and private insurers are increasingly aware that managing health at the asymptomatic stage is significantly more cost-effective than treating advanced diseases. This awareness has led to the implementation of various incentive programs that reward providers for high patient participation rates in wellness screenings.
Another critical driver is the increasing prevalence of chronic diseases such as diabetes, hypertension, and cardiovascular conditions. AWVs serve as a vital touchpoint for early detection and the creation of personalized prevention plans. By identifying risk factors early, healthcare systems can reduce hospital readmission rates and improve overall population health metrics, which is a core objective of modern healthcare policy.
The rapid advancement in health information technology also plays a pivotal role. Modern EHR systems now feature automated alerts and scheduling tools that prompt both providers and patients when a wellness visit is due. This technological support reduces the administrative friction that previously hindered the adoption of these visits, leading to higher completion rates and more comprehensive data collection.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Aging Global Population (Silver Tsunami) | +2.8% | Global (High in Japan, USA, Germany) | 2025-2034 |
| Transition to Value-Based Care Models | +1.5% | North America and Europe | 2025-2030 |
| Government Incentives and Reimbursement Policies | +1.2% | United States (Medicare/Medicaid) | 2025-2034 |
| Integration of AI and Predictive Analytics | +0.9% | Global | 2027-2034 |
Annual Wellness Visits Market Restraints Analysis
Despite the growth, the market faces significant restraints, most notably the high level of administrative burden placed on primary care providers. The extensive documentation required to satisfy reimbursement criteria can often lead to physician burnout or a reluctance to promote these visits. In many cases, the time required to complete a thorough AWV exceeds the allocated clinical time, making it a challenge for high-volume practices.
Patient awareness remains another formidable barrier. Many eligible individuals, particularly in the Medicare population, confuse the Annual Wellness Visit with a traditional physical exam. When patients realize the AWV is primarily a cognitive and risk assessment rather than a hands-on clinical exam, there can be a perceived lack of value, leading to low repeat attendance rates.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Physician Documentation Burden and Burnout | -1.1% | United States and UK | 2025-2028 |
| Low Patient Literacy Regarding Preventive Benefits | -0.8% | Global | 2025-2034 |
| Interoperability Issues Between EHR Platforms | -0.5% | Global | 2025-2030 |
Annual Wellness Visits Market Opportunities Analysis
There is a substantial opportunity in the expansion of telehealth-enabled wellness visits. Virtual AWVs eliminate transportation barriers for the elderly and allow providers to conduct assessments in the patient's home environment, which can often provide better insights into social determinants of health and fall risks. The refinement of remote monitoring technology will likely make virtual visits as effective as in-person ones.
Another burgeoning opportunity lies in the integration of behavioral health screenings within the AWV framework. As the medical community increasingly recognizes the link between mental health and physical outcomes, incorporating standardized depression and cognitive impairment screenings into the annual routine can open new revenue streams for providers while significantly improving patient care trajectories.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Remote Patient Monitoring (RPM) Integration | +1.4% | North America and Asia Pacific | 2026-2034 |
| Mental Health and Cognitive Screening Integration | +1.1% | Global | 2025-2034 |
| Employer-Sponsored Wellness Programs | +0.7% | Europe and North America | 2027-2034 |
Annual Wellness Visits Market Challenges Impact Analysis
A primary challenge is the inconsistent reimbursement landscape across different private payers and international health systems. While Medicare provides a clear pathway, private insurers often have varying requirements for what constitutes a "wellness visit," creating confusion for billing departments and reducing the overall efficiency of practice management.
Data privacy and cybersecurity also present ongoing challenges. As AWVs collect increasingly sensitive information, including cognitive assessments and social risk factors, the platforms used to store and transmit this data become high-value targets for cyberattacks. Maintaining patient trust while scaling digital wellness solutions requires significant and continuous investment in security infrastructure.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Variable Reimbursement Policies across Private Insurers | -0.9% | United States and Latin America | 2025-2029 |
| Cybersecurity Threats and Data Privacy Compliance | -0.6% | Global (Strict in EU due to GDPR) | 2025-2034 |
Annual Wellness Visits Market - Updated Report Scope
This report provides a granular analysis of the global Annual Wellness Visits market, covering the technical, regulatory, and economic factors shaping its growth. The scope includes a detailed breakdown of service types, provider types, and the technological platforms facilitating these visits. It evaluates the impact of government policies and the shift toward preventative medicine on market valuation through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 5.8 Billion |
| Market Forecast in 2034 | USD 10.8 Billion |
| Growth Rate | 7.2% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | UnitedHealth Group, CVS Health (Aetna), Humana Inc., Oak Street Health (CVS), ChenMed, Signify Health, VillageMD, Agilon Health, Privia Health, Walgreens Boots Alliance, Cigna Group, Elevance Health, Cano Health, One Medical (Amazon), P3 Health Partners, CareMax, Inc., Apollo Medical Holdings, Optum (UnitedHealth), HCA Healthcare |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Annual Wellness Visits market reflects the diverse ways in which preventive care is delivered and consumed. The market is primarily bifurcated by service type, where "Subsequent Wellness Visits" represent a significant recurring revenue stream for healthcare providers. As the Medicare-eligible population matures, the volume of these annual follow-ups grows exponentially. Another critical segment is the "Mode of Delivery," which has seen a dramatic shift since 2020. Virtual visits are no longer a niche offering but a mainstream component of wellness strategies, particularly for patients with mobility issues or those residing in underserved rural areas.
- By Service Type:
- Initial Annual Wellness Visit (G0438)
- Subsequent Annual Wellness Visit (G0439)
- Initial Preventive Physical Examination (IPPE)
- By Provider Type:
- Primary Care Physicians (PCPs)
- Nurse Practitioners (NPs)
- Physician Assistants (PAs)
- Medical Assistants and Health Educators
- By Mode of Delivery:
- On-site/In-person Clinics
- Virtual/Telehealth Platforms
- Mobile Health Units
- By End-User:
- Independent Practices
- Hospital-affiliated Clinics
- Federally Qualified Health Centers (FQHCs)
- Managed Care Organizations
Regional Highlights
- North America: The largest market globally, the United States drives growth through the CMS (Centers for Medicare & Medicaid Services) guidelines and the high penetration of Medicare Advantage plans. The focus here is on closing "Gaps in Care" and maximizing Star Ratings for insurers.
- Europe: The market is characterized by strong public health initiatives and a growing emphasis on geriatric care in nations like the UK, Germany, and France. European markets are increasingly adopting standardized screening protocols to manage the healthcare costs of an aging citizenry.
- Asia Pacific: This is the fastest-growing region due to the massive population base in China and India and the sophisticated, preventative-focused healthcare systems in Japan and South Korea. Rising middle-class incomes and awareness of chronic disease management are accelerating adoption.
- Latin America: Growth is driven by the expansion of private health insurance and government efforts to decentralize healthcare services, though economic volatility remains a challenge for consistent market expansion.
- Middle East & Africa: Significant investments in healthcare infrastructure and "Vision" programs in GCC countries are fostering a new environment for preventive wellness services.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Annual Wellness Visits Market. These organizations are at the forefront of implementing innovative patient engagement strategies and advanced data analytics to optimize the wellness visit experience.
- UnitedHealth Group
- CVS Health (Aetna)
- Humana Inc.
- Oak Street Health
- ChenMed
- Signify Health
- VillageMD
- Agilon Health
- Privia Health
- Cigna Group
- Elevance Health
- Cano Health
- One Medical
- P3 Health Partners
- CareMax, Inc.
- Apollo Medical Holdings
- Optum
- HCA Healthcare
- Walgreens Boots Alliance
- Kaiser Permanente
Frequently Asked Questions
What is the primary difference between an Annual Wellness Visit and an Annual Physical?
An Annual Wellness Visit (AWV) is a preventive screening focused on creating or updating a personalized prevention plan and performing a cognitive assessment. Unlike an annual physical, it does not typically include a hands-on physical examination of the body unless deemed necessary by the provider for specific risk factors. The AWV is specifically designed to identify risks and develop a long-term health roadmap.
How is the Annual Wellness Visits market benefiting from AI integration?
AI is being used to analyze Health Risk Assessment (HRA) data to predict patient risks more accurately. It helps providers identify which patients are at a higher risk for chronic conditions or falls, allowing for more targeted interventions during the wellness visit. AI also automates the documentation process, significantly reducing the administrative burden on clinicians.
Which region offers the most significant growth opportunities for wellness service providers?
While North America is the largest market, the Asia Pacific region offers the most significant growth opportunities due to its rapidly aging population and increasing investment in preventive healthcare infrastructure. Countries like Japan and China are seeing a surge in demand for structured geriatric wellness programs.
What are the key reimbursement codes for Annual Wellness Visits in the US?
The primary CPT/HCPCS codes are G0438 for the Initial Annual Wellness Visit and G0439 for Subsequent Annual Wellness Visits. Additionally, the G0402 code is used for the "Welcome to Medicare" visit, which is a one-time introductory preventive exam for new beneficiaries.
What role does telehealth play in the future of the AWV market?
Telehealth is a major growth catalyst, as it allows for the completion of the cognitive and risk assessment portions of the AWV remotely. This increases accessibility for patients with limited mobility and improves efficiency for clinics by freeing up physical exam rooms for more acute clinical needs.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
