Continuoglucose Monitoring Devices Market
Continuoglucose Monitoring Devices Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711095 | Published On : October 06, 2026 |
Format : 


 | Author : Erika Grotto
Continuoglucose Monitoring Devices Market Size
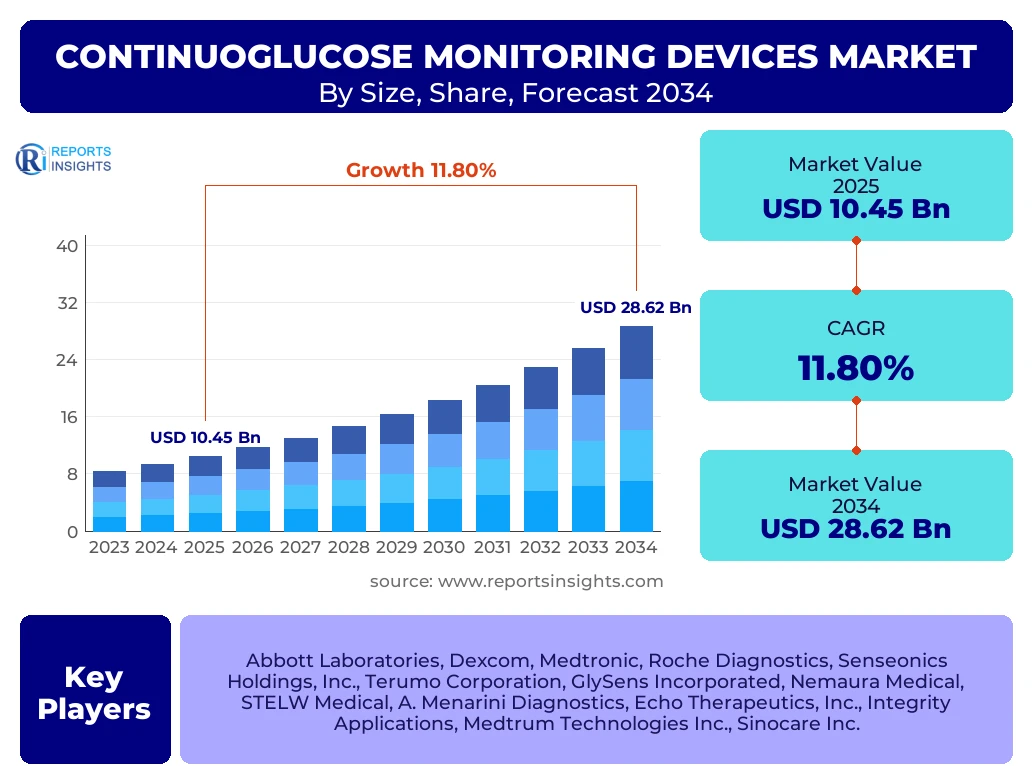
According to Reports Insights Consulting Pvt Ltd, The Continuoglucose Monitoring Devices Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 11.8% between 2025 and 2034. The market is estimated at USD 10.45 Billion in 2025 and is projected to reach USD 28.62 Billion by the end of the forecast period in 2034.
Key Continuoglucose Monitoring Devices Market Trends & Insights
The global continuous glucose monitoring (CGM) landscape is undergoing a radical transformation driven by the convergence of medical technology and digital health ecosystems. Current market inquiries frequently center on the integration of artificial intelligence for predictive glycemic alerts, the shift toward non-invasive sensing technologies, and the expansion of CGM utility beyond Type 1 diabetes into Type 2 and pre-diabetic populations. Competitive benchmarking indicates a fierce race among leading medical device manufacturers to enhance sensor longevity, reduce calibration requirements, and improve the form factor of wearable components for better patient compliance and comfort.
Regional insights suggest that while mature markets like North America and Western Europe maintain high adoption rates due to favorable reimbursement frameworks, the Asia-Pacific region is emerging as a high-growth corridor. This growth is catalyzed by rising healthcare expenditures and an alarming increase in the prevalence of lifestyle-related diabetes in emerging economies. Broader trends emphasize the role of data interoperability, where CGM data is seamlessly integrated with insulin pumps to create automated insulin delivery (AID) systems, often referred to as artificial pancreas systems.
- Largest Region: North America remains the dominant market, accounting for approximately 42% of global revenue share.
- Fastest-Growing Region: Asia-Pacific is expected to register the highest CAGR due to increasing healthcare infrastructure and a massive patient pool.
- Largest Segment: Sensors currently represent the largest revenue-generating segment within the component category due to their disposable nature and recurring purchase cycles.
- Key Trend: Transition from professional-led monitoring to consumer-driven, self-management platforms facilitated by smartphone connectivity.
- Technology Shift: Growing preference for factory-calibrated sensors that eliminate the need for painful finger-stick blood glucose tests.
Key Takeaways Continuoglucose Monitoring Devices Market Size & Forecast
The market trajectory for continuous glucose monitoring devices is fundamentally anchored in the global shift toward proactive and personalized healthcare. Analysis of user inquiries regarding market forecasts reveals a high interest in the sustainability of growth rates post-pandemic and the impact of wearable health tech on traditional glucose meter sales. The forecast period 2025-2034 anticipates a robust expansion, supported by a transition in clinical guidelines that increasingly recommend CGM as the standard of care for all insulin-requiring patients.
- Market Leadership: The United States holds the leading position globally, driven by high awareness and early adoption of advanced medical devices.
- Value Proposition: CGM devices are proven to significantly reduce HbA1c levels and minimize hypoglycemia incidents, providing a strong clinical and economic rationale for adoption.
- Patient Demographics: While Type 1 diabetes patients remain the core user base, the Type 2 diabetes segment is the fastest-growing demographic for CGM application.
- Product Innovation: The introduction of long-term implantable sensors is expected to disrupt the current dominance of short-term transdermal sensors.
- Economic Impact: Increasing insurance coverage and public health initiatives are lowering the barriers to entry for middle-income populations.
Continuoglucose Monitoring Devices Market Drivers Analysis
The primary drivers of the CGM market include the escalating global prevalence of diabetes and the increasing demand for real-time monitoring to prevent long-term complications. Furthermore, advancements in sensor technology and the integration of medical devices with mobile health applications are significantly enhancing user experience and clinical outcomes. The drive toward value-based care models in developed healthcare systems also incentivizes the use of CGM to reduce emergency room visits related to glycemic fluctuations.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Prevalence of Type 1 and Type 2 Diabetes | +4.2% | Global (Strongest in APAC and MEA) | 2025 - 2034 |
| Technological Advancements in AI-driven Predictive Analytics | +2.5% | North America & Europe | 2026 - 2030 |
| Favorable Reimbursement Policies and Insurance Coverage | +3.1% | USA, Germany, Japan | 2025 - 2028 |
| Integration with Automated Insulin Delivery (AID) Systems | +2.0% | Global | 2027 - 2034 |
Continuoglucose Monitoring Devices Market Restraints Analysis
Despite robust growth, the market faces significant hurdles, particularly regarding the high cost of continuous monitoring compared to traditional blood glucose monitoring (BGM) methods. Additionally, stringent regulatory approval processes for new devices and concerns regarding data privacy and cybersecurity in connected medical devices act as major barriers to market entry for smaller players and slower adoption in certain regions.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Sensors and Receivers | -1.5% | Developing Nations (India, Brazil, South Africa) | 2025 - 2034 |
| Regulatory Hurdles and Strict Compliance Standards | -0.8% | Europe (MDR Compliance), USA (FDA) | 2025 - 2027 |
| Inaccuracy Issues in Extreme Physiologic Conditions | -0.5% | Global | Short Term |
Continuoglucose Monitoring Devices Market Opportunities Analysis
Opportunities abound in the development of non-invasive glucose monitoring technologies and the expansion of the market into the wellness and fitness tracking space. Furthermore, the underpenetrated markets of Asia and Latin America offer significant growth potential as healthcare infrastructure improves and awareness increases. Partnerships between pharmaceutical companies and medical device manufacturers also provide opportunities to offer integrated disease management solutions.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Non-Invasive Wearable Technology Development | +3.5% | Global | 2028 - 2034 |
| Expansion into the Gestational Diabetes Segment | +1.2% | Global | 2025 - 2030 |
| Telehealth Integration for Remote Patient Monitoring | +2.2% | North America, APAC | 2026 - 2034 |
Continuoglucose Monitoring Devices Market Challenges Impact Analysis
Maintaining data security and integrity in an increasingly connected healthcare ecosystem remains a critical challenge. Additionally, the presence of skin irritations and discomfort from wearing sensors for extended periods can lead to patient dropout rates. Ensuring that devices remain affordable while maintaining high precision and reliability is a balancing act that manufacturers must navigate to sustain long-term market growth.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Data Privacy and Cybersecurity Vulnerabilities | -1.0% | High-tech Markets (USA, EU) | 2025 - 2034 |
| Patient Adherence and Skin Sensitivity Issues | -0.7% | Global | Continuous |
| Supply Chain Disruptions for Specialized Components | -0.4% | Global | Short-to-Medium Term |
Continuoglucose Monitoring Devices Market - Updated Report Scope
This report provides an in-depth analysis of the global continuous glucose monitoring devices market, covering all critical dimensions including technological innovations, regulatory landscapes, and competitive dynamics. The scope extends across various components such as sensors, transmitters, and receivers, while providing granular data on end-user segments including hospital settings, homecare, and diagnostic clinics. The study utilizes a mix of primary and secondary research to deliver precise market valuations and growth projections through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 10.45 Billion |
| Market Forecast in 2034 | USD 28.62 Billion |
| Growth Rate | 11.8% CAGR |
| Number of Pages | 264 Pages |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Abbott Laboratories, Dexcom, Medtronic, Roche Diagnostics, Senseonics Holdings, Inc., Terumo Corporation, GlySens Incorporated, Nemaura Medical, STELW Medical, A. Menarini Diagnostics, Echo Therapeutics, Inc., Integrity Applications, Medtrum Technologies Inc., Sinocare Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on component, end-user, and demographics to provide a comprehensive view of the revenue streams. Sensors dominate the component segment due to their high replacement frequency, typically every 7 to 14 days. The homecare segment is the largest and fastest-growing end-user category, reflecting the trend toward self-management of chronic diseases. Demographic analysis reveals that while adults currently represent the largest user base, the pediatric segment is witnessing significant growth due to the critical need for constant monitoring in children with Type 1 diabetes.
- By Component:
- Sensors (Electrochemical, Fluorescence)
- Transmitters
- Receivers/Mobile Applications
- By End-User:
- Homecare Settings (Primary driver of market growth)
- Hospitals and Clinics (Acute care and intensive monitoring)
- Diagnostic Centers
- By Patient Demographic:
- Adults (Age 18+)
- Pediatrics (Ages 2-17)
- By Distribution Channel:
- Retail Pharmacies
- Online Sales Platforms
- Institutional Sales
Regional Highlights
- North America: Holds the largest market share (approx. 42%). Growth is supported by high healthcare spending, presence of major industry players, and high awareness levels regarding diabetes management technology.
- Europe: The second-largest market, with countries like Germany, France, and the UK leading in terms of public reimbursement for CGM devices.
- Asia-Pacific: The fastest-growing region with a projected CAGR of over 14%. Driven by the rising middle class, increasing prevalence of diabetes in China and India, and improving medical infrastructure.
- Latin America: Developing market with significant potential in Brazil and Mexico as awareness regarding chronic disease management grows.
- Middle East & Africa: Steady growth expected as regional governments prioritize digital health initiatives and tackle high rates of obesity and diabetes.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Continuoglucose Monitoring Devices Market.- Abbott Laboratories
- Dexcom, Inc.
- Medtronic PLC
- F. Hoffmann-La Roche Ltd
- Senseonics Holdings, Inc.
- Terumo Corporation
- Ascensia Diabetes Care Holdings AG
- Nemaura Medical Inc.
- GlySens Incorporated
- Medtrum Technologies Inc.
- Sinocare Inc.
- A. Menarini Diagnostics S.r.l.
- Integrity Applications Ltd.
- Echo Therapeutics, Inc.
- WaveForm Diabetes
Frequently Asked Questions
What is the current market size and future growth potential of the CGM market?
The market is valued at approximately USD 10.45 Billion in 2025 and is expected to grow to USD 28.62 Billion by 2034, representing a CAGR of 11.8%. This growth is driven by increasing diabetes prevalence and technological advancements.
Who are the major players leading the Continuous Glucose Monitoring market?
Key market leaders include Abbott Laboratories (FreeStyle Libre series), Dexcom (G-series), and Medtronic (Guardian series). These companies dominate the market through continuous innovation and established distribution networks.
How do reimbursement policies affect the adoption of CGM devices?
Reimbursement is a critical factor; markets with comprehensive insurance coverage, like the US and Germany, see significantly higher adoption rates compared to regions where patients must pay out-of-pocket.
What is the difference between professional CGM and personal CGM?
Personal CGM is owned by the patient for long-term daily use, whereas professional CGM is owned by a healthcare provider and used for short periods (3-14 days) to gather data for clinical assessment and therapy adjustment.
Are non-invasive glucose monitoring devices currently available in the market?
Most commercially successful CGM devices currently require a tiny filament under the skin (minimally invasive). While several companies are developing fully non-invasive technologies (using optical or thermal sensing), they are largely in the clinical trial or early regulatory stages.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
